Africa’s Hottest IPO Broke Fintech Apps, But Jury Is Out On Whether It’s Worth It
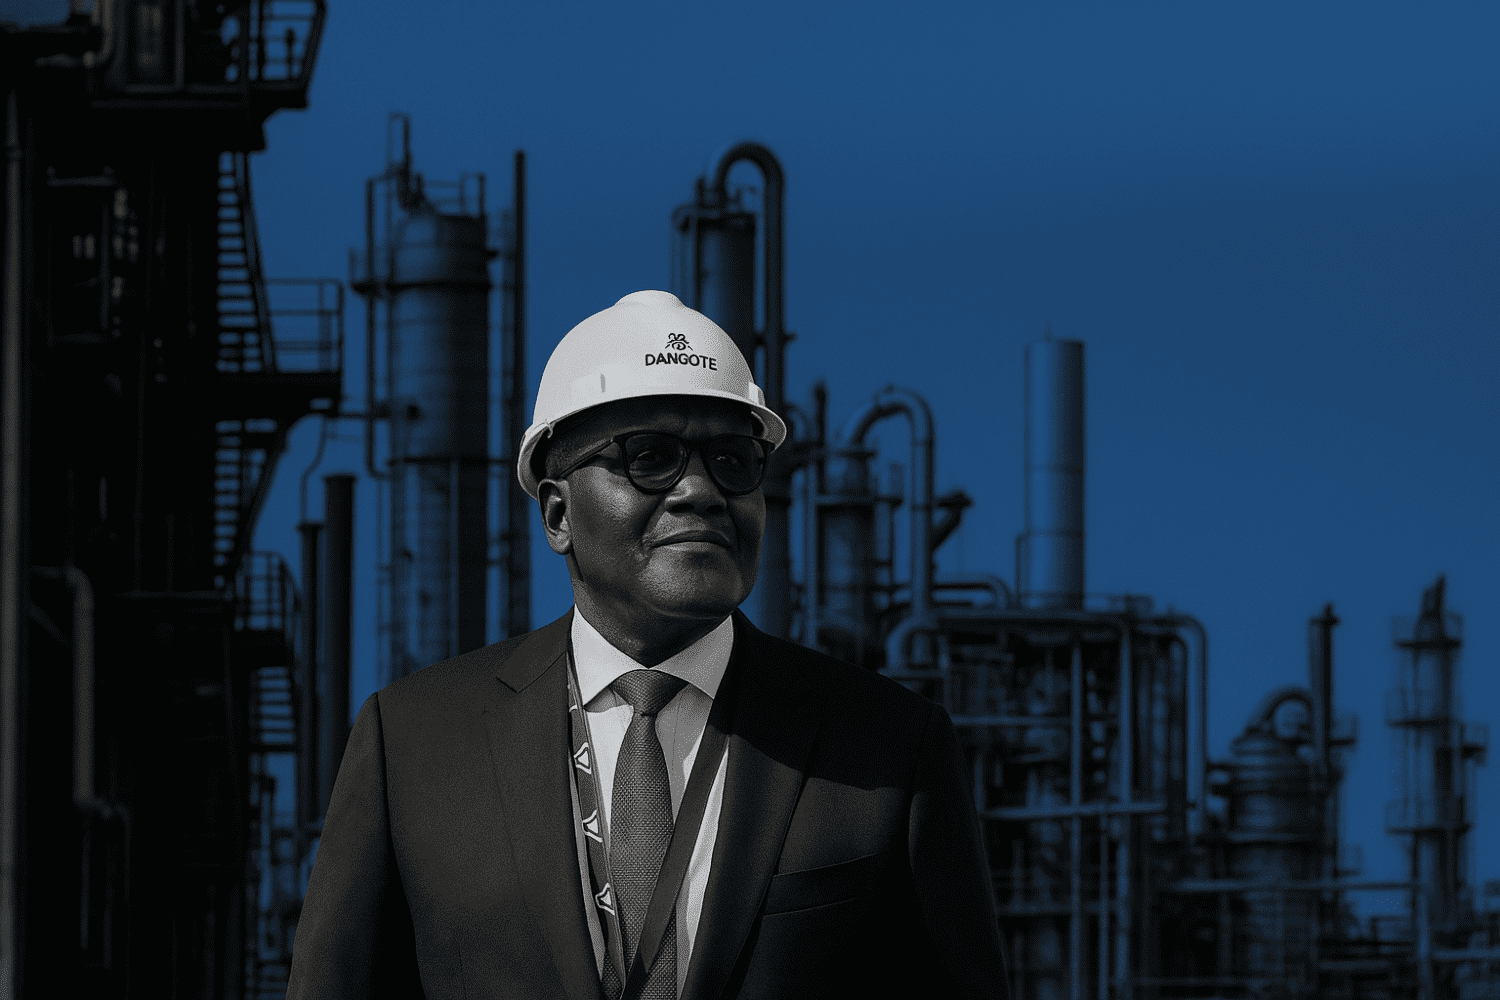
Nigeria’s leading fintechs are high on Africa’s hottest IPO and seeing a surge in users, so much so that some buckled under the weight, but the jury is out on whether the hype is worth it.
Some of the country’s major fintech players, including Bamboo, Cowrywise, Flutterwave, Moniepoint, Paga, and PiggyVest, spent weeks telling their users to buy a piece of Africa’s biggest refinery. When the doors opened on Monday, some of the apps themselves could not get through.
Bamboo, one of the country’s largest digital investment platforms, opened more than 236,000 new accounts in the week before the Dangote Petroleum Refinery’s initial public offering. Traffic on its app surged to ten times normal levels within thirty minutes of the offer going live. “To be very, very honest, our system broke,” Bamboo co-founder Yanmo Omorogbe told Reuters. Cowrywise and InvestNaija reported similar failures.
The disruption has been framed as a success problem. That framing suits the offering’s promoters, who have marketed it as a “people’s IPO” with a minimum buy of ten shares at NGN 525.00, or roughly USD 4.00. Aliko Dangote, Africa’s richest man, told local television he expects ten million Nigerians to buy shares. The Nigerian Exchange recorded NGN 1.5 T (USD 1.12 B) in subscriptions on the first day alone, about 70% of the total offer.
But the numbers in the prospectus tell a more complicated story. For some analysts, the investment case, when separated from the national pride attached to Dangote’s name, raises questions that the app crashes have pushed to the margins. The most detailed public critique comes from Feyi Fawehinmi, a notable accountant and long-time critic of Dangote’s business practices, whose analysis “Is This IPO Halal” has circulated widely among Nigerian market watchers.
***
Fawehinmi’s central argument is that the refinery’s national importance and the merits of buying its shares at NGN 525.00 are separate questions. His findings point to curious discrepancies in reported figures, such that the same six-month period yields materially different pictures of operations, capital spending and financing depending on which section of the prospectus one reads.
The prospectus, Fawehinmi points out, presents USD 1.513 B of cash generated from operations in the reporting accountant’s extract for the first half of 2026, but USD 1.273 B in the historical summary. Cash purchases of property, plant and equipment are shown as USD 162.2 M in one presentation and USD 33.4 M in another.
Furthermore, finance income moves from USD 498.5 M to USD 49.6 M. Both presentations arrive at the same USD 2.106 B profit before tax because the differences are somehow offset elsewhere, but the prospectus does not provide a numerical bridge explaining why the same six months produce materially different pictures of operations, Fawehinmi says.
There’s also the question of whether the profit can last. The refinery swung from a loss in the first half of 2025 to a USD 2.106 B pretax profit in the first half of 2026. But 98.4% of that improvement came from a USD 2.35 B rise in gross profit, driven by product volumes and prices that benefited from exceptional market conditions linked to the Iran war.
Although stable full-capacity operations only began in March 2026, the prospectus estimates a 2026 gross refining margin of about USD 24.20 per barrel but cautions that market conditions can change. Fawehinmi contends investors are being asked to price a company whose recent profitability was forged in a geopolitical crisis, not a steady-state market, tethered to a lofty promise that the refinery would double capacity by 2029, on schedule, through a USD 14.3 B expansion program.
***
Then there is the question of what this refinery means for Nigerians at the pump. On this particular point, which is probably the one Nigerians care about most, Fawehinmi’s broader work on Dangote’s business model is relevant.
The prospectus commits to import-parity pricing, meaning Dangote’s fuel is priced against what it would cost to import, not against the cost of refining it locally. The World Bank found that as of March 2026, imported petrol was about 12% cheaper than Dangote’s ex-depot price. It could thus be deduced that the refinery sold as a solution to Nigeria’s dependence on costly imported fuel is pricing its output in a way that does not necessarily deliver cheaper fuel to the Nigerians buying its shares.
This pattern is especially emphasised by critics who have tracked Dangote’s rise. Academic research on Dangote Cement describes a business built on a Backward Integration Programme that made it possible for him to invest aggressively while competitors faced higher barriers.
Critics have accused the group of predatory pricing and of benefiting from import bans, concessions, and restrictions in sectors where it operates while opting not to transmit the gains of favourable policies to the local market. A study on Dangote’s business model described the relationship between the conglomerate and the Nigerian state as one built on crony capitalism.
Then there is the research supporting the offer. Fawehinmi examined reports from Renaissance Capital, Chapel Hill Denham and CardinalStone, all of which are named in the prospectus as joint issuing houses. CardinalStone’s report discloses that it was communicated to Dangote Refinery and approved for publication by the company, and that the analyst responsible holds personal positions in the refinery’s shares.
Renaissance Capital’s report states it is not independent investment research. Fawehinmi also identifies a calculation error in Chapel Hill Denham’s comparable-company analysis that inflated its peer average from 6.4 to 9.5, reducing its valuation by roughly USD 2.21 B when corrected. CardinalStone’s own comparable-company method values the refinery at USD 27 B, below the IPO valuation, yet it more than doubled its headline target.
The critique also pointed out an overlap of directors and funds across the refinery and multiple other Dangote sister companies as potential governance risks, concluding that none of these means the refinery is a bad investment but that the investment case should be evaluated on its numbers, not on the patriotic appeal of owning a piece of Africa’s biggest industrial asset.
It thus stands to reason that just as some fintech platforms didn’t prove robust enough to handle the demand they spent weeks generating, investors might want to examine whether the prospectus they are subscribing through those apps is any more robust.