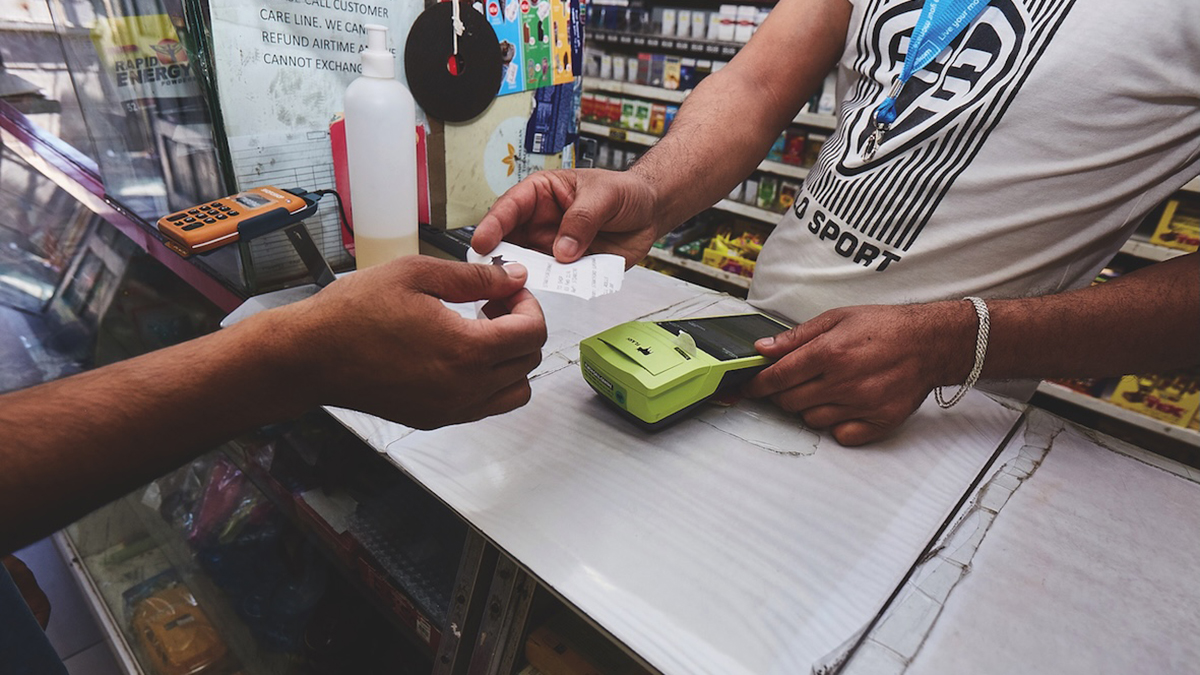
OPay has established its place as Nigeria’s ubiquitous payments app for a good few years now. Its green logo is plastered on the walls of roadside kiosks and the phone screens of millions, with the simple pitch of moving money faster than a bank. But the company’s newly filed IPO prospectus reveals a more consequential transformation. Lending, not payments, is now the engine driving its revenue.
In 2024, transaction-based services accounted for 39% of revenue while lending contributed 35%. By the first half of 2026, that hierarchy had flipped. Loan financing alone generated USD 236.1 M, or 50.6% of total revenue, according to the F-1 filing. Payments revenue fell to 28%. The company originated USD 927.6 M in new loans in Nigeria during the first six months of 2026, roughly three times the amount from a year earlier.
The scale of OPay’s lending machine is such that it now has 6.7 million unique quarterly borrowers, more than seven times the number it had in early 2024. Its non-performing loan ratio stood at 4.3% as of June 30, 2026, down from 4.8% a year earlier.
That improvement is down to the company quietly shifting its credit mix away from riskier consumer loans toward merchant lending. In the first half of 2026, the fintech unicorn disbursed USD 99.0 M in merchant loans across 20,000 transactions, generating USD 8.8 M in revenue. The company said it “tightened risk appetite in consumer loans” and shifted toward merchant loans, which carry a lower risk profile, according to the filing.
Consumer lending in Nigeria is politically sensitive and operationally fragile. Borrowers are often informally employed, repayment discipline is uneven, and regulators are watching. Merchant lending is different. OPay can observe a business’s daily transaction flows through its POS terminals and wallet accounts, giving it real-time visibility into cash flow and a natural collection mechanism.
OPay is also quietly rolling out a buy-now-pay-later product. Its BNPL offering allows active users to access short-term credit for everyday purchases with a two-week billing cycle and a one-week repayment window. For now, the product is small. In the first half of 2026, BNPL transaction volume was just USD 5.0 M across 13.4 million transactions. But the company is clearly testing whether the same infrastructure that powers its lending business can support a consumer credit product that feels more like a payment than a loan.
The timing of this lending pivot is not coincidental. OPay filed for a New York Stock Exchange listing under the ticker OPAY, seeking a valuation that reports suggest could reach USD 4 B. Standard Bank Group’s subsidiary has agreed to invest up to USD 200 M through a concurrent private placement, a signal that institutional capital sees value in OPay’s lending economics.
But the filing also exposes the tension at the heart of the model. OPay’s provision for expected credit losses surged to USD 118.4 M in the first half of 2026 from USD 38.1 M a year earlier. The company is lending more, and it is setting aside more to cover the risk of default. Whether merchant lending genuinely lowers that risk or simply delays it remains the central question for investors. One of its main rivals did run into problems with a startup it had lent a sizeable sum to, for instance.
OPay is betting that the same data advantage that made it a payments giant can make it a lending giant too. The prospectus suggests that bet is already paying off. The risk is that in emerging markets, credit cycles can turn faster than payment networks can adapt.