Deepfake Scandal & Misconduct Findings Fuel Collapse Of Top SA Trading Firm

By Henry Nzekwe  |  December 11, 2025

For many in South Africa, the promise arrived in a familiar, convincing form. A video of Elon Musk, or sometimes local billionaire Johann Rupert, appeared online endorsing a revolutionary new investment platform. The message was that advanced artificial intelligence could generate massive returns, turning a small deposit into life-changing wealth.

This was the gateway for hundreds of people to Banxso, an online trading platform that marketed itself as a democratising force in finance. Today, that gateway has slammed shut, sealed by a record ZAR 2 B (~USD 118 M) fine and a trail of devastation linking cutting-edge deepfake fraud to old-fashioned financial misconduct.

The Financial Sector Conduct Authority’s (FSCA)’s recently declared penalty against Banxso is the largest in South African regulatory history. It caps a catastrophic fall for a firm that, just a few years after its 2021 launch, had secured sponsorships with the national soccer team Bafana Bafana and UFC champion Dricus du Plessis to burnish its legitimacy.

The FSCA investigation found the company and its directors engaged in systematic abuse, involving misappropriating client funds, providing false information, and making unrealistic promises.

“The investigation found that Banxso and its key persons… misappropriated client funds, provided false and misleading information to clients and to the FSCA, promised clients unrealistic returns and failed to act in the best interests of its clients,” the regulator stated. The authority has now handed all evidence to the South African Police Service for a criminal investigation.

The Deepfake Pipeline

Central to Banxso’s rapid client acquisition was a network of deceptive social media and online advertisements. Investigations revealed a sophisticated lead-generation scheme. Deepfake videos of Musk, Rupert, and other tycoons promoted automated trading systems like “Immediate Matrix,” which promised monthly returns of over ZAR 300 K (~USD 17.7 K) from a ZAR 4.7 K (USD 277.79) deposit. Users who clicked were funneled directly to Banxso’s platforms, BanxsoX and AutoBanxso, to trade high-risk contracts for difference (CFDs).

Many victims reported being enrolled automatically, without clear consent. Banxso previously denied authorising these ads, even claiming its systems were hacked by a third party that inserted the leads. However, the sheer volume of victims pointed to a core business strategy. Over 380 people contacted one investigation, claiming combined losses of ZAR 280 M (~USD 16.5 M). In court papers, Banxso indicated it had around 7,000 customers, suggesting total losses could reach the billions.

One investor, who lost ZAR 500 K (~USD 29.5 K), reportedly took the drastic step of applying to court to have Banxso liquidated. Their experience was not unique. The Western Cape High Court placed Banxso under provisional liquidation in August 2025, with Judge Andre le Grange stating he was satisfied the company’s business model was itself illegal.

A Maximum Penalty

Beyond the ZAR 2 B administrative penalty on Banxso and directors Harel Adam Sekler and Warwick David Sneider, other key individuals faced massive fines. Former CEO Manuel de Andrade was fined ZAR 20 M, and others faced multi-million rand penalties. Crucially, Sekler, Sneider, De Andrade, and another key person, Mohammed Bux, were debarred from the financial services industry for 30 years each—the maximum sentence ever imposed by the FSCA.

In a simultaneous move, the regulator finalised the withdrawal of the financial services licence for Afrimarkets Capital, a platform linked to Banxso through common directorships and operating from the same Cape Town office. The FSCA found Afrimarkets guilty of near-identical misconduct. This action closed a loophole that appeared when, following initial negative reports about Banxso, a similar platform emerged under a different name.

In its response, Banxso stated it was exploring “all available mechanisms to address what we believe to be fundamental concerns with this outcome.” Afrimarkets similarly said it was “exploring all available legal options.”

The fallout continues. The FSCA has confirmed it is investigating two new platforms, Protea Markets and UMarketPro, following reports that they operate with a virtually identical model and employ many former Banxso and Afrimarkets staff. This suggests the regulatory crackdown, while historic, may be part of a longer game of whack-a-mole.

Meanwhile, resolution is far from over for the estimated thousands of clients. With Banxso under liquidation and a criminal probe underway, the path to recovering lost funds remains uncertain.
The USD 8 M Bet That Africa Can Win The Space Data Centre Race Without Launching A Single Satellite

By Staff Reporter  |  October 2, 2026

Rama Afullo pitched orbital data centres inside Google and SpaceX. Both said no. So he raised USD 8 M to build what they wouldn’t.

Satlyt, his Sunnyvale and Nairobi-based startup, closed a seed round this week led by Houston’s Non Sibi Ventures, with participation from TLCOM, Antler, Launch Africa Ventures, and others. The company’s software launched Thursday on a SpaceX rocket, riding alongside Google’s first Project Suncatcher prototype.

Most satellites already carry unused computing power. Satlyt’s software turns that idle hardware into a distributed AI network. Instead of building new spacecraft, the company makes existing ones smarter. Afullo compares it to VMware or Snowflake, a software layer that abstracts away the infrastructure. “If SpaceX is the iPhone, we’ll build Android,” he told TechCrunch.

This matters because the orbital data centre race is heating up. SpaceX has pitched investors on up to 1 million AI satellites that could generate trillions in revenue. Google is testing its own hardware. But building data centres in orbit remains brutally expensive.

A 1-gigawatt orbital facility would cost roughly USD 170 B, more than three times a comparable ground-based facility. Space compute currently runs at about four times terrestrial costs. Bain & Company estimates orbital data centres won’t reach commercial scale until the early 2030s and will capture only a modest share of global compute by 2040.

Satlyt sidesteps that capital trap. By focusing on software for satellites already in orbit, the company avoids launch costs, radiation hardening, and thermal management challenges that plague hardware-first approaches. Its earlier deployment of Google’s Gemma model on a Momentus spacecraft cut data transmission sizes by more than 60%, a direct cost saving for operators paying for downlink bandwidth.

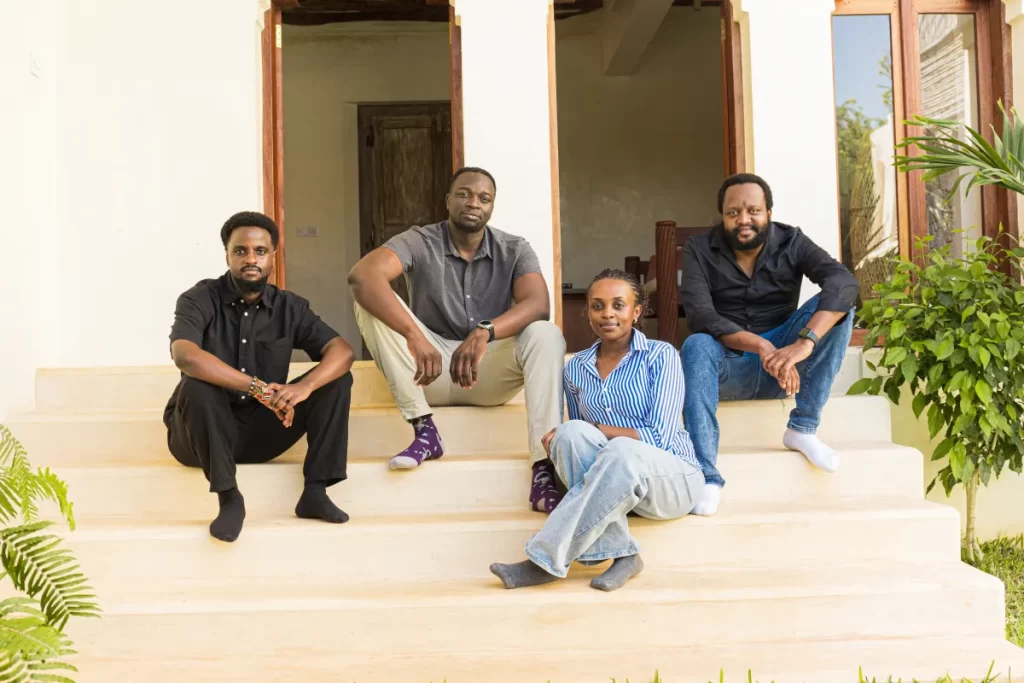
Satlyt team: Leina Moli (Senior Space Software Engineer), Rama Afullo (Founder & CEO), Junn Wangari (Senior Space Systems Engineer), and Nelson Psenjen (CTO)

Satlyt’s leadership team is entirely Kenyan-American, with engineering concentrated in Nairobi. The company has signed memoranda with the Kenya Space Agency and Angola’s GGPEN to deploy AI-driven Earth observation for agriculture, climate monitoring, and disaster response. For a continent that spends billions importing satellite data it cannot process locally, onboard AI offers a path to sovereignty over its own geospatial intelligence.

The risks are real. Satlyt has not yet demonstrated its most ambitious claim, a cloud network spanning multiple satellites. Besides, high-performance GPUs remain scarce in orbit, and the economics of orbital compute may never favour generalised workloads. But Satlyt says it’s going beyond compute to sell efficiency to operators who already own the hardware.

Afullo wants Satlyt’s software on 20% of satellites by 2030. That is an ambitious target. But if the satellite industry follows the trajectory of terrestrial cloud computing, winning will likely be less about building the biggest data centres and more about making the existing ones work harder.

For a continent largely absent from the first space race, that is a more plausible route to relevance than waiting for Starship to deliver a hyperscaler to low Earth orbit.

Electric Bikes Are Quietly Winning Africa’s Delivery Fleets One Battery Swap At A Time

By Henry Nzekwe  |  September 30, 2026

Africa’s delivery riders are making a cold, financial calculation. With petrol prices surging in South Africa and fuel costs consuming up to 40% of a rider’s income in markets like Nigeria, the economics of the internal combustion motorcycle are collapsing. Electric two-wheelers, once dismissed as costly experiments, are now courting the continent’s delivery fleets with a proposition that is less about saving the planet than saving the margin.

The simple pitch is that battery swapping eliminates the upfront cost of ownership and the downtime of charging. ARC Ride, a Kenyan electric motorcycle company, launched its Panther model in South Africa this month at ZAR 22.5 K with a battery-as-a-service model where a full swap costs ZAR 50.00 and delivers up to 110km of range. The company estimates that at the current inland petrol price, its electric bike costs about 30% less to run per 100km than a comparable 125cc petrol motorcycle.

Spiro, Africa’s largest battery-swapping operator, reports that its riders save an average of USD 3.00 per day on fuel and maintenance, while the company earns roughly USD 0.50 per battery swap. In Nigeria, a Spiro rider spends about NGN 125.00 to travel 100 kilometres on electric versus over 3,400 naira on petrol. The company has deployed more than 130,000 electric motorcycles across seven African countries and operates over 2,500 swap stations. “We don’t sell motorcycles; we sell kilometres,” says Spiro CEO Jules Samain.

The model is spreading through commercial partnerships rather than consumer sales. Jumia, Africa’s leading e-commerce platform, has partnered with Spiro in Uganda to electrify nearly half of its delivery fleet in Kampala.

“By introducing electric bikes into our fleet, we are demonstrating that e-commerce can be both convenient and climate-conscious,” says Steven Lamony, Jumia Uganda’s managing director. In Kenya, Roam Air electric motorcycles now power a fully electric cold-chain network with Keep It Cool, cutting fuel and maintenance costs by up to 75% compared to petrol bikes.

But the pivot is not without friction. ARC Ride had to correct launch material that claimed riders would earn “up to 20% more net earnings,” clarifying that the figure refers to a reduction in weekly operating costs, not income. Battery-swapping infrastructure remains concentrated in major cities, and the economics vary by rider. Someone covering 50 kilometres a day will save less than someone covering 150 kilometres.

The direction is evident, regardless. Afreximbank’s development arm has led a USD 75 M equity investment into Spiro, the largest-ever bet on an African electric motorcycle company. Spiro has also partnered with Chinese manufacturer Yadea to expand production and adapt vehicles to African road conditions. In South Africa, Valternative Energy has deployed over 1,000 electric delivery motorcycles and 100 swap stations in under two years, serving Uber Package and Famous Brands.

For fleet operators squeezed by fuel volatility and maintenance costs, the electric motorcycle is becoming more of a lifeline than a green mandate.

Copia’s USD 123 M Collapse Exposes Kenya’s Rural E-Commerce Math Problem

By Staff Reporter  |  September 30, 2026

Kenya’s High Court ordered Copia Kenya into liquidation on September 17, ending a two-year administration process that failed to revive a company that raised USD 123 M to solve one of African e-commerce’s hardest problems. The startup’s realisable assets stand at just KES 206.6 M (USD 1.6 M), against liabilities that “substantially exceed that amount,” according to court filings.

The court found no realistic path for Copia to return to operating as a going concern. “I am satisfied that the Joint Administrators have demonstrated, on a balance of probabilities, that the objectives of administration have been exhausted,” Justice Rhoda Rutto wrote in the ruling. The same administrators, Julius Mumo Ngonga and Anthony Makenzi Muthusi of KPMG, have been appointed joint liquidators.

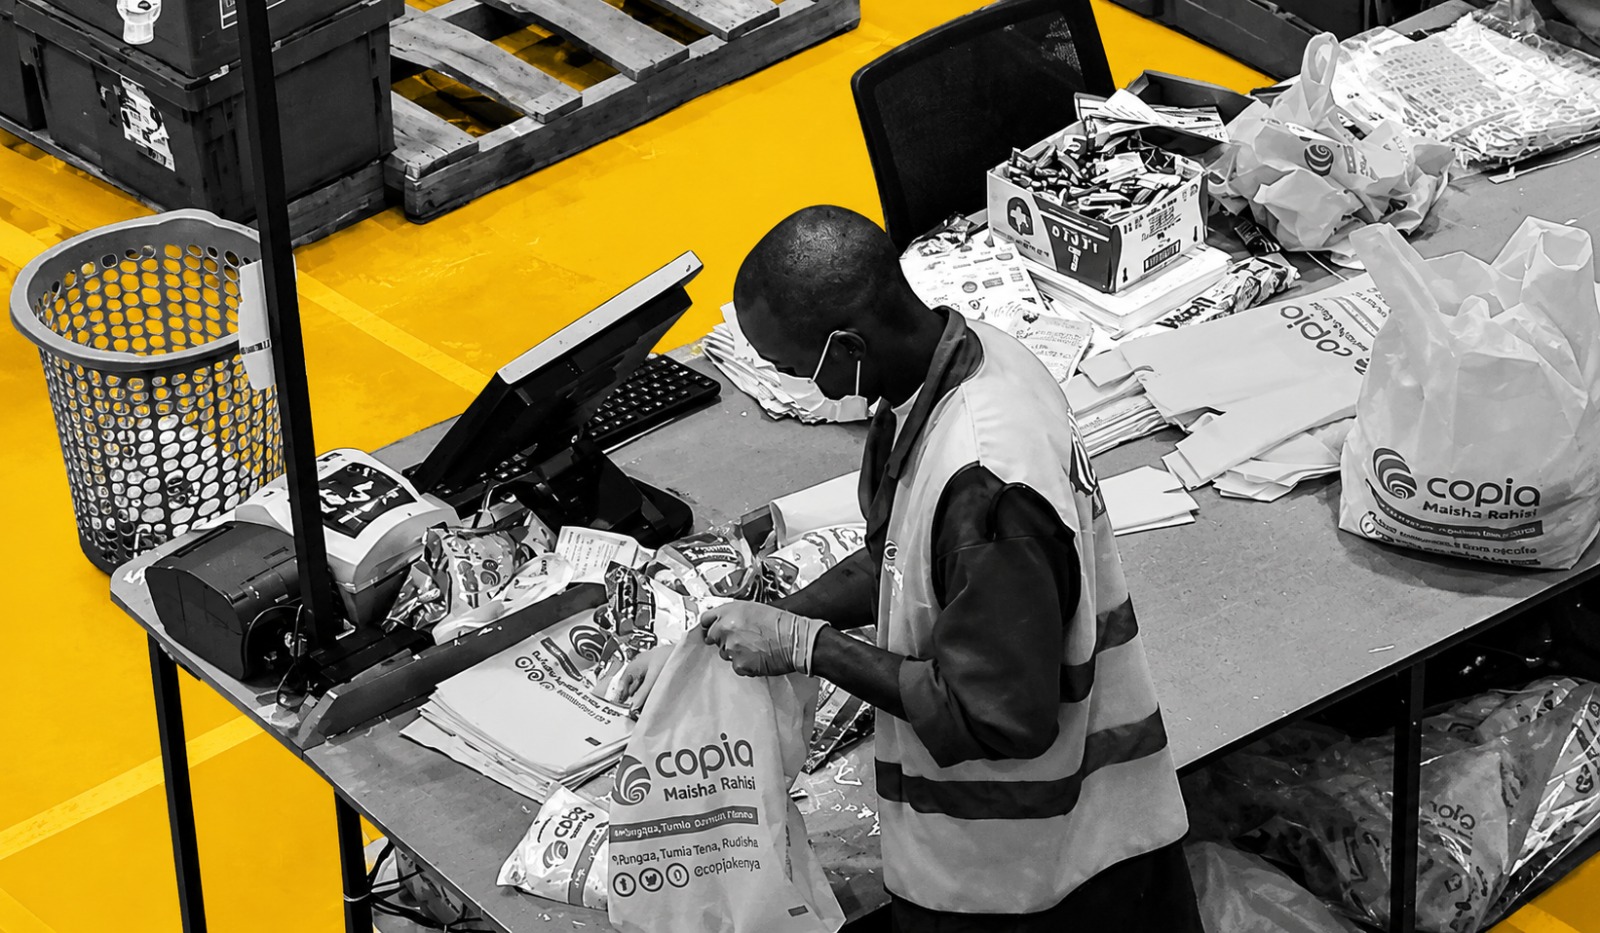
Founded in 2013 by Tracey Turner and Jonathan Lewis, Copia built a 50,000-agent network across Kenya and Uganda, using local shopkeepers as order points and collection centres for rural and peri-urban households. The model was designed for consumers with limited internet access, no formal delivery addresses, and little trust in online-only retail. Copia aggregated orders so that deliveries to a local agent could serve many households at once.

But the underlying arithmetic never worked. Rural last-mile delivery across African markets typically accounts for 35 to 55% of total shipping costs, compared to a global average of about 28%. Copia’s average order value hovered around USD 10.00, while the company carried the full weight of warehouses, depots, delivery vehicles and tens of thousands of agent commissions between manufacturers and consumers.

The startup bet that higher volumes would eventually spread those costs across more orders. That bet never paid off. Copia never turned a profit in its 12-year existence. It laid off 350 employees in July 2023, closed its Uganda business in April, and abandoned expansion plans into Nigeria, Ghana, South Africa and Mozambique before entering administration in May 2024 after its parent company failed to raise fresh capital.

More than 1,000 jobs were cut. Investors including Goodwell Investments, Lightrock, DOB Equity and the US International Development Finance Corporation are unlikely to recover anything. Copia’s failure is now part of a broader pattern in Kenya, where 13 venture-backed startups have collapsed or entered administration over the past five years, erasing at least USD 717 M in investor capital.

Kenya’s startup funding environment has tightened sharply. Startups in the country raised about USD 126 M in the first half of 2026, down from USD 227 M a year earlier, as investors pivoted away from growth-at-all-costs strategies toward profitability and sustainable unit economics.

What makes Copia’s collapse particularly striking is what happened next. Barely a month after the company entered administration, Turner and former CEO Tim Steel registered Stahili, a new e-commerce platform promising cashback, discounts and mobile data rewards.

Corporate filings show Stahili is wholly owned by Copia Holding Company, the same US-registered entity linked to Turner and the now-defunct Copia Global. The new venture is positioned as a leaner, digitally native alternative that does not build expensive last-mile delivery networks

Crypto Regulations Put South Africa’s Top Banks In Conflict Over Payments

By Staff Reporter  |  September 30, 2026

A quiet but consequential battle is unfolding in South Africa over the future of cross-border payments, and the stakes are far higher than the usual regulatory squabble.

At its core, a coalition of crypto firms and now a major digital bank is fighting draft rules from the National Treasury and the South African Reserve Bank (SARB) that would effectively ban South African companies from using crypto assets or stablecoins for cross-border payments.

The coalition, which goes by the acronym CATASTROPHE (Crypto Asset Taskforce for Advancing Sound, Technology-Neutral Regulation for Opportunity, Prosperity and a Healthy Economy), has been joined by GoTyme Bank, a digital bank with over 13 million customers. It argues that regulation should target financial activities, not the technology used to perform them.

The proposed rules are part of a broader overhaul of South Africa’s exchange control system. The draft Crypto Asset Manual, published in August 2026, would require all cross-border crypto transfers to be routed through authorised dealers and reported to SARB’s Financial Surveillance Department. Individuals would retain allowances of ZAR 2 M (USD 122.8 K) and ZAR 10 M (USD 614 K), but companies would get nothing. A salaried professional would have more freedom to move money across borders than an exporter paying a supplier.

The industry says this is already causing damage. VALR CEO Farzam Ehsani told Moneyweb that ZAR 2.2 B ~(USD 134 M) in potential foreign investment has been placed on hold because of the uncertainty. He warns that prohibiting corporate crypto payments “is likely to drive transactions underground or offshore”.

The banks, for their part, are not united in opposition. Absa, one of South Africa’s largest banks, sees the rules as overdue clarity, though it acknowledges they would “naturally limit immediate opportunities”. This split reveals the tension as incumbent banks are comfortable with rules that constrain a competing settlement rail, even as a digital challenger like GoTyme breaks ranks to back the crypto industry.

Reserve Bank Governor Lesetja Kganyago has framed the issue as one of fairness. “If we have these rules, we cannot simultaneously have weak regulatory frameworks for crypto assets alongside a rigorous system of reporting and permissions for everyone else,” he said at the central bank’s annual meeting.

South Africa is among Africa’s largest crypto markets, with an estimated USD 35 B in annual on-chain volume. Nearly 8 million South Africans used crypto platforms in the first half of 2025. The country liberalised parts of its exchange control regime earlier this year, then moved to pull crypto back under strict capital flow rules.

The public comment period closed on September 30. The industry has signalled it may pursue a legal challenge if its objections are ignored. The outcome will determine whether South Africa regulates crypto as a technology or as a financial activity, and whether its businesses can compete globally using the payment rails of the future.

A Nigerian Entrepreneur’s Unusual Bet On A Blockchain Phone No One Knows They Need

By Henry Nzekwe  |  September 28, 2026

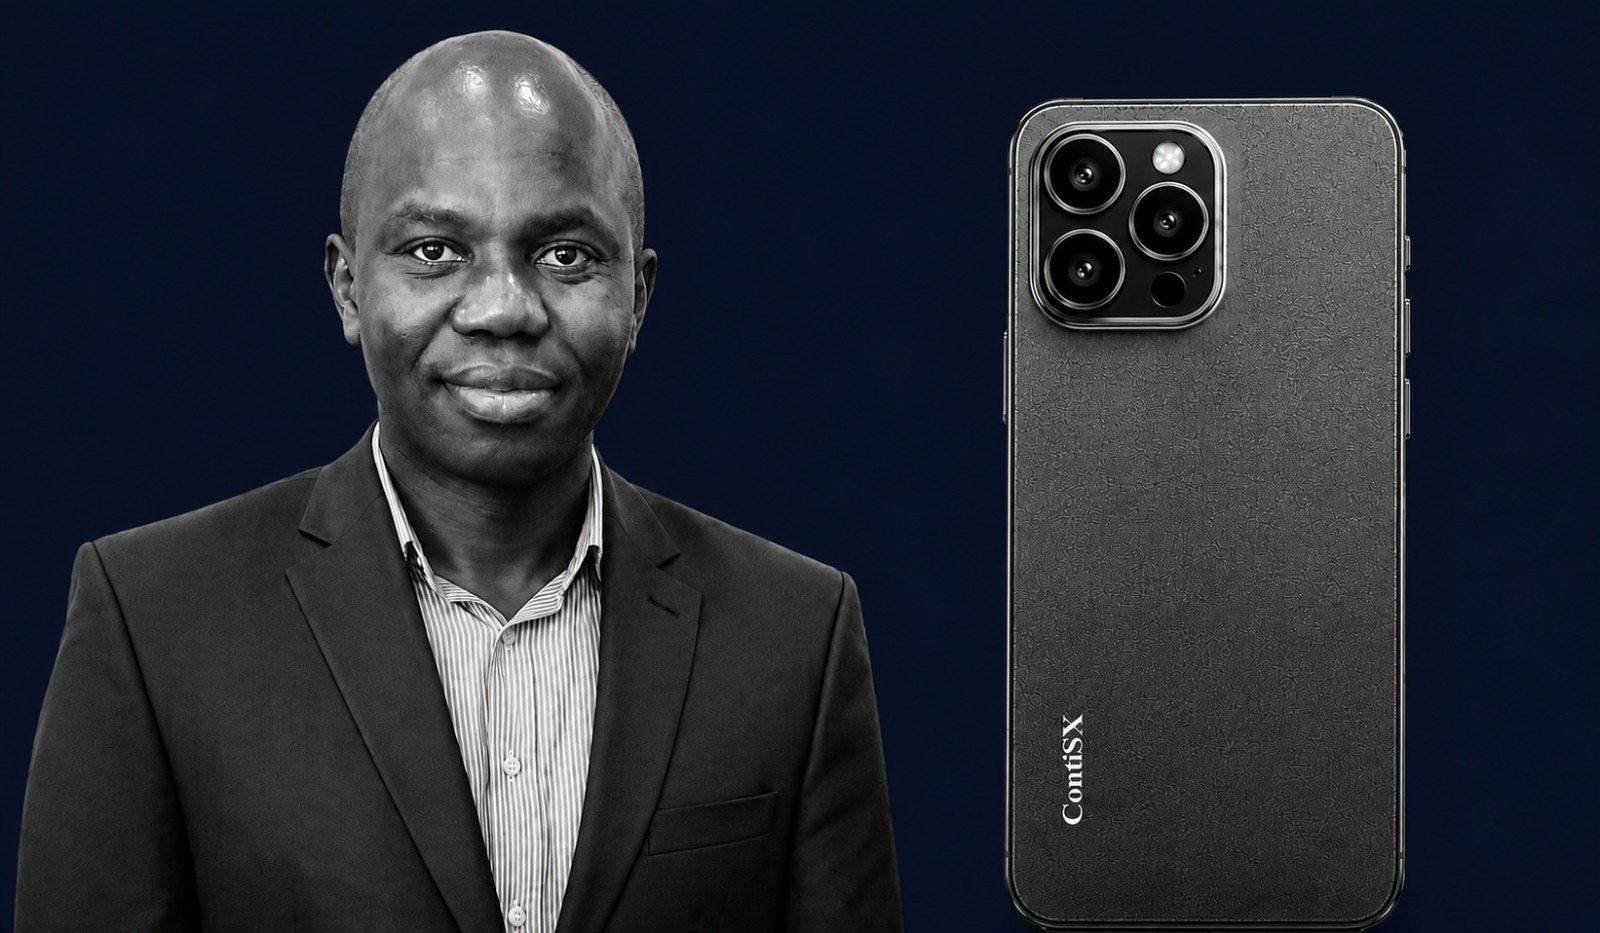
Ndubuisi Ekekwe has spent his career building things that end up inside other people’s products. At Analog Devices, he helped design the accelerometer that went into early iPhones, as his colourful biography captures. Other feats attributed to him include a PhD research project in wafer-level chip packaging that still earns him U.S. government royalties, two doctorates, four master’s degrees, and a patent on medical robotics microchips that the U.S. government acquired rights to.

Now the storied educator cum entrepreneur is rolling out a phone he developed; a peculiar kind which he calls Africa’s first blockchain phone. Ekekwe’s ContiSX Securities Exchange Plc has opened preorders for the ContiSX Phone, a blockchain-native handset priced at NGN 550 K, around USD 400.00 at current rates.

Shipments are scheduled to begin October 19, the same day Ekekwe plans an event at the State House Banquet Hall in Abuja’s Presidential Villa. The phone runs neither Android nor iOS. It cannot install WhatsApp, Instagram, or Facebook. It is a walled garden, and Ekekwe is betting that Nigerian institutions will pay to live inside it.

The pitch

The device’s core proposition includes encrypted messaging, voice, and video calls at the blockchain level, with cryptographic keys isolated in a dedicated secure enclave and biometric authorisation on device. ContiSX says the phone’s encryption is guaranteed against eavesdropping and tampering. The company has not published independent security audit results.

The phone’s real hook is what it connects to. ContiSX received Approval-in-Principle from Nigeria’s Securities and Exchange Commission in April 2026 to establish a full-service securities exchange targeting equities, bonds, ETFs, and commercial paper. The AIP is an early-stage regulatory clearance, and it does not yet permit full operations. ContiSX had initially targeted a September 2026 launch and has since pushed to October.

For one year after purchase, preorder customers get zero-rated data access to ContiSX’s exchange and central securities depository. Ekekwe says the company has prepaid participating Nigerian telecommunications companies to cover those data costs.

“When we launch ContiSX Securities Exchange, you will not need data to buy stocks, FGN bonds and other investment products within our ecosystem,” Ekekwe wrote on LinkedIn. “Our philosophy is Investment Inclusion, and we want to remove barriers that prevent citizens from participating in capital markets.”

The market reality

Nigeria’s smartphone market is brutally price-sensitive. The average selling price in Q1 2026 was USD 134.00, up just 2% year-on-year. Phones below USD 150.00 account for more than 60% of volumes. Roughly 90% of devices sold in the country are imported. Omdia forecasts African smartphone shipments could decline in 2026 amid rising memory costs and currency volatility.

At NGN 550 K, the ContiSX Phone costs roughly four times the average selling price. It is not competing with Tecno and Infinix but with mid-range Samsung and Apple devices, which collectively hold a significant share of the Nigerian market.

But Ekekwe’s target buyer is not the mass market. It is Nigerian institutions, government agencies, and businesses that value sovereignty over cost. The phone ships with ContiSX Shield for security alerts, Boardroom for corporate governance, and a Business Suite covering accounting, payroll, and inventory management.

The regulatory backdrop has shifted in Ekekwe’s favour. In July 2026, President Bola Tinubu signed an executive order establishing a Virtual Asset Council chaired by the Central Bank of Nigeria, with the SEC as vice-chair. The order explicitly aims to close gaps that unregistered operators have exploited, while enabling “responsible innovation” through a CBN regulatory sandbox.

Whether Ekekwe can convert that goodwill into a functioning exchange with actual issuers, investors, and financial institutions is the open question. Ekekwe has spent decades building components that other people put their names on. This time, the name on the box is his, and he’ll be hoping for tailwinds.

AvadaPay: The Best Payment Provider for Digital Platforms in Africa

AvadaPay: The Best Payment Provider for Digital Platforms in Africa

By Partner Content  |  September 28, 2026

You’ve built the platform. Customers can register, place an order, book a service, subscribe, request financing, or use whatever product sits at the center of your business.

Now they need to pay.

Whether you’re building a SaaS product, a marketplace, a mobility platform, a digital lending product, or another online service, payments are essential to the customer experience. But they’re rarely the reason the product exists.

This leaves many digital platforms with a decision to make: spend engineering time connecting payment methods, setting up collections and payouts, and adding transaction notifications. Or work with a payment partner that already has that infrastructure.

Building these capabilities in-house takes development time and ongoing maintenance. Using several providers can create even more integrations and systems to manage.

AvadaPay offers a simpler setup, making it easier for digital platforms to manage collections, payouts, and Bulk SMS via a single integration.

About AvadaPay

AvadaPay is a payment platform helping businesses accept and manage digital payments across African markets. Through a single integration, digital platforms can connect to local payment methods, manage collections and payouts, track transactions, and use Bulk SMS for customer communication.

This makes AvadaPay particularly useful for platforms launching in or expanding across Africa, where payment methods and customer preferences can differ significantly between markets.

As Maurice Bisungo, Key Accounts Manager at AvadaPay, explains:

“Digital platforms already have a lot to build and manage. Having a payment partner that can take care of collections, payouts and the supporting infrastructure gives teams more room to focus on their product and customers.”

With the payment infrastructure taken care of, businesses can focus their engineering resources on the platform and customer experience they’re actually building.

One Integration to Local Payment Methods

Customers pay with the methods they already trust, and those methods change from market to market.

According to the GSMA, around $1.4 trillion moved through mobile money in Sub-Saharan Africa in 2025, roughly two-thirds of the global total.

A platform entering Kenya needs M-Pesa. In other markets, customers may reach first for MTN Mobile Money, Airtel Money, Orange Money, or another local payment method.

‘’One thing we see across African markets is how strongly payment preferences differ from one country to another. Making familiar local payment methods available gives customers an easier experience and helps platforms adapt as they enter new markets,” says Winnie Odede, Regional CEO, AvadaPay East Africa:

AvadaPay offers businesses different ways to make these local payment methods available to customers. For online payments, platforms can integrate AvadaPay’s API directly into their website or app, generate payment links or use STK Push. For in-person collections, merchants can accept mobile money payments using a unique QR code that customers scan, enter the amount and authorize from their phone.

Collections In. Payouts Out.

Plenty of platforms need money to move in both directions.

A marketplace collects from buyers and pays sellers; a mobility platform collects from riders and pays drivers; and a lending platform disburses loans and collects repayments.

AvadaPay supports both collections and payouts, allowing businesses to build payment flows around how their platform actually works.

And because both run through the same platform, businesses get a single view of the money moving in and out.

Payments Need Communication Too

Then there’s everything that happens around the transaction:

Payment received.

Your OTP is 4821.

Your payout has been processed.

Your payment is due.

AvadaPay also offers Bulk SMS for OTPs, payment confirmations, transaction alerts, reminders, onboarding messages, and other customer communication.

That means businesses can set up the payments and the messaging around them without adding yet another provider to the stack.

Build Once. Expand Further.

The value of this approach becomes even clearer when the next market appears on the roadmap.

Without regional payment infrastructure, expansion can mean starting the integration process again: new payment methods, new connections, new technical work.

As Florien Maniraho, CEO of AvadaPay Rwanda, explains:

“Expanding into a new market should not mean rebuilding your payment infrastructure from the beginning. If the foundation already connects you to the local payment methods you need, your team can spend more time on launching and growing the product.”

AvadaPay provides local payment methods, collections, payouts, Bulk SMS, and transaction visibility through one integration across supported African markets.

For a new platform, that’s far less to build before the first payment comes in.

For an existing platform expanding into Africa, it means adding the local payment methods customers expect without starting from scratch.

Airtime Lending Turf War Rocks South African Fintech Quietly Dominant In Nigeria

By Staff Reporter  |  September 25, 2026

A regulatory turf war between two Nigerian agencies briefly cut off airtime credit for an estimated 40 million mobile subscribers in April, exposing how a single South African fintech had quietly become critical infrastructure for Nigeria’s poorest phone users.

The Federal Competition and Consumer Protection Commission (FCCPC) extended its Digital, Electronic, Online or Non-Traditional Consumer Lending (DEON) regulations to cover airtime credit services in April 2026. The Nigerian Communications Commission (NCC), which licenses value-added service providers, was not consulted. Caught between the two regulators, MTN Nigeria, Airtel Nigeria, Globacom and 9mobile suspended their airtime lending products on April 15.

The Federal High Court in Abuja issued an interim injunction on April 24 restraining the operators from cutting off access to Nairtime Nigeria Limited, Optasia’s local subsidiary. Services were fully restored on June 24. But the financial damage was already done.

Nigeria accounted for approximately 14% of Optasia’s group revenue in its 2025 financial year. By the second quarter of 2026, that figure had fallen to under 4%. Optasia’s H1 2026 revenue still grew 58% to USD 185.3 M, driven by expansion in Ghana, Pakistan, Indonesia and Congo-Brazzaville. Chief Executive Salvador Anglada said the group had delivered growth “across all parameters” despite the Nigerian disruption.

The broader investment signal is harder to dismiss. Foreign capital inflows into Nigeria’s telecom sector fell to USD 7.24 M in the first quarter of 2026 from USD 80.78 M a year earlier, according to the National Bureau of Statistics. The Association of Licensed Telecommunications Operators of Nigeria (ALTON) disputes the figure, noting operators invested NGN 2.13 T in capital expenditure in 2025 and plan NGN 1.86 T for 2026. But the timing of the regulatory clash coincides with the sharpest quarterly drop in recorded foreign telecom investment in recent years.

The Federal High Court in Lagos delivered a landmark judgment on July 20, ruling that the FCCPC can regulate competition and consumer protection in airtime lending but cannot issue telecommunications licences. That authority remains exclusively with the NCC. Justice Ambrose Lewis-Allagoa summarised the principle in a single line: “Concurrency means coexistence, not displacement”.

President Bola Tinubu had already moved before the judgment. In June, he directed the FCCPC to dismantle Optasia’s 12-year dominance and approved nine Nigerian fintechs to compete in a market estimated at NGN 3 T in annual transaction value. The FCCPC argued the exclusive arrangement facilitated capital flight while contributing minimally to local tax revenues or employment.

Optasia rejects the monopoly framing. Its Nigerian subsidiary, Nairtime Nigeria Limited, is “fully locally incorporated, locally staffed and locally led,” the company said. Anglada has called the suspension “a little bit aggressive”.

Meanwhile, the Wireless Application Service Providers Association of Nigeria has appealed the July 20 judgment, asking the Court of Appeal to suspend enforcement of the DEON regulations pending determination. ALTON has called for a formal coordination protocol between the FCCPC and the NCC. The NCC has yet to publicly stake out its position.

Airtime credit is not a niche product, offering a lifeline to millions of Nigerians who borrow a few hundred naira in airtime when their balance runs out. It is how traders, artisans and workers at the base of the economy stay connected when formal credit is unavailable. When the service goes dark, they feel it immediately.

In the same vein, when the regulatory environment goes dark, investors feel it for years. and it’s unlikely that Nigeria can afford another regulatory turf war in a sector it wants to lead globally.

Feature Image Credits: Cardtonic

The Kiosk That Taught Kenya To Trust Digital Money Is Dying

By Henry Nzekwe  |  September 24, 2026

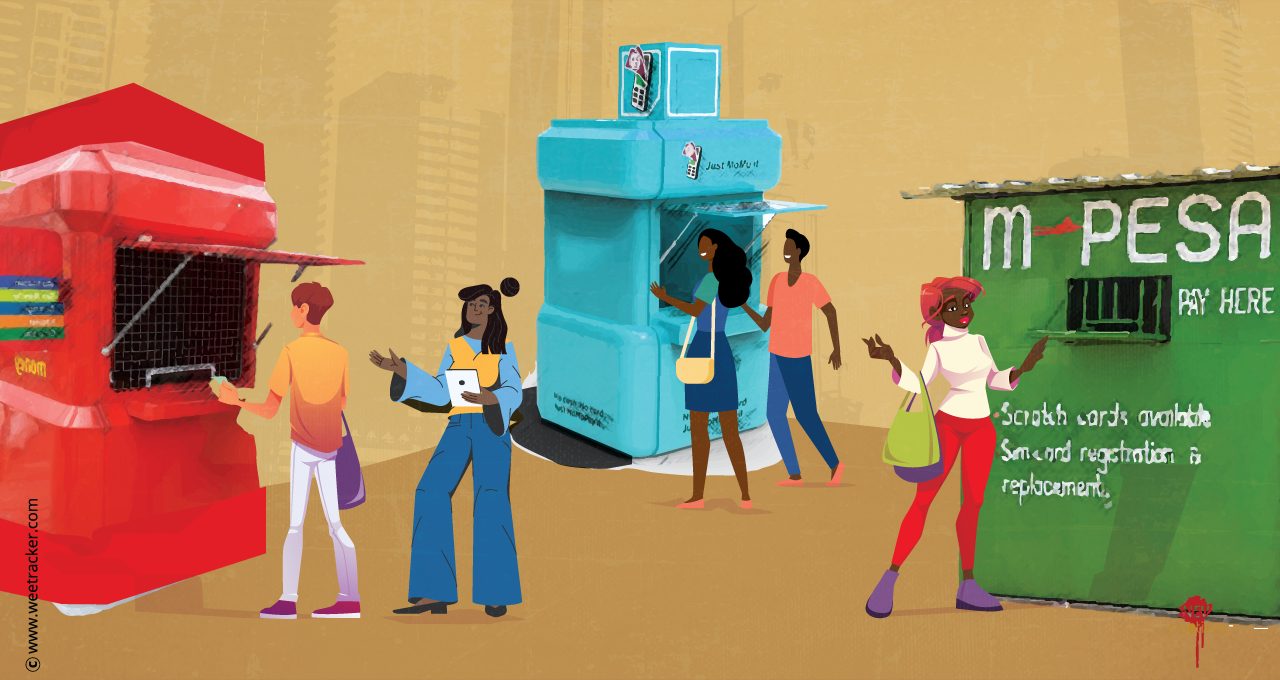
It’s not uncommon to hear that Kenya’s mobile money revolution has about as much to do with technology as with hundreds of thousands of small shops, kiosks, and street corners where a generation of Kenyans learned to trust digital money, one deposit and withdrawal at a time. That network is now shrinking.

Communications Authority of Kenya data show registered mobile money agents fell 5.6% between March and June, from 602,470 to 568,463. The decline came even as mobile money subscriptions climbed to 54.01 million, pushing penetration to 101.3%. More Kenyans are using mobile money than ever, but fewer are using agents to do it.

The two numbers tell the same story from opposite ends. Mobile money is succeeding so thoroughly that it is beginning to make its own physical infrastructure redundant. For nearly two decades, agents were the human API connecting cash to digital wallets, especially where bank branches were scarce. Now smartphones, interoperability, and merchant payment systems are letting customers bypass that step entirely.

Central Bank of Kenya data show active agents processed 212.45 million cash-in and cash-out transactions worth KES 682.46 B (~USD 5.26 B) in June alone. That is still a lot of money moving through the agent network. But the direction of travel is changing.

The value of cash handled by agents fell by a record KES 430.3 B (USD 3.3 B) in the first eleven months of 2025, the sharpest drop in Kenya’s history. The Central Bank attributed the decline to shifting usage patterns rather than reduced relevance, noting that users increasingly consolidated transfers into fewer, higher-value payments and adopted merchant payment channels instead of withdrawing cash.

***

The economics of being an agent are also getting harder at exactly the moment the network has grown more crowded. Safaricom’s M-Pesa agent base expanded 11.4% to 333,011 in the year to March 2026. Total commissions paid to agents rose just 0.3% to KES 37.4 B (USD 288.6 M) over the same period. Average annual commission per agent fell 10% to KES 112.2 K (USD 866.41), or roughly KES 9.353 K (USD 72.20) a month.

The commission pot is growing at 1.3% while the agent count grows at 20%. That dilution is the quiet crisis beneath the headline decline. “The average agent is now generating gross revenue of less than KES 10 K per month,” noted one analysis of Safaricom’s half-year disclosures. “For a standalone shop paying rent and electricity, this is statistically a loss-making venture.”

When M-Pesa launched in 2007, agents were the only way to convert cash into digital value. Interoperability between networks since 2022 has weakened the lock-in that once made a single agent’s location a competitive moat.

Merchant payment systems like Lipa na M-Pesa and Pochi la Biashara now let customers pay directly from their wallets without withdrawing cash first. Pochi la Biashara revenue grew 86% in the year to March 2026, while withdrawal revenue actually declined 0.7% even as total M-Pesa revenue grew 14%.

Agents are processing more transactions for less money. Total M-Pesa transaction volume grew 26.5% in the same half-year period, but transaction value grew only 5%. More small transactions mean more time serving customers and more liquidity rebalancing trips, without a proportional increase in commission income.

Some agents are adapting. A growing number now offer agency banking services for institutions like Equity Bank, KCB, and Co-operative Bank alongside mobile money, and others operate both M-Pesa and Airtel Money outlets to widen their customer base.

The Central Bank’s planned 57% cut in mobile money transfer fees by 2028, part of its National Financial Inclusion Strategy, will further compress the commission pool unless transaction volumes rise enough to compensate. Analysts at FSD Kenya estimate that 90,000 agents could close, mainly in sparsely populated regions.

Phone Costs & Power Cuts Keep 906 Million Africans Offline Despite Coverage Gains

By Henry Nzekwe  |  September 23, 2026

Africa has spent a decade and billions of dollars building mobile networks. The result is a continent where 92% of the population lives within reach of a mobile broadband signal. Yet only 36% of Africans use the internet at all, leaving roughly 906 million people in a strange limbo. They are covered, but they are not connected.

The GSMA and the Partnership for Digital Access in Africa call this the usage gap, and a new roadmap released this week argues it is now the central challenge for the continent’s digital future.

The coverage gap, the 122 million people beyond any network, is shrinking, but the usage gap is not. In Sub-Saharan Africa, the gap between coverage and actual use is more than double the global average, according to the GSMA’s State of Mobile Internet Connectivity 2026 report.

The roadmap, developed by GSMA Intelligence and launched at the United Nations General Assembly, focuses on three priorities. The most immediate is migrating the more than 600 million mobile connections still running on 2G and 3G networks onto 4G and 5G smartphones.

But the cost barrier is significant. An entry-level internet-enabled smartphone now costs the equivalent of 76% of average monthly income in Sub-Saharan Africa, up from 44% for the poorest 20% of people in low and middle-income countries globally. Rising memory and chipset prices have pushed smartphone shipments across Africa down seven 7% year on year, with the crucial sub-USD 100.00 segment collapsing by 34%.

“Africa has already built much of the network foundation for its digital future,” said John Giusti, GSMA Chief Regulatory Officer. “The urgent task now is to close the usage gap by making smartphones and services affordable, equipping people with practical skills, building trust, and ensuring connectivity delivers visible value in people’s daily lives.”

The second priority is energy. Nearly 600 million Africans lack reliable electricity. A network tower without power is useless, and a smartphone without a charge is a brick. The roadmap calls for treating electrification and connectivity as a single investment agenda, using telecom towers as anchor customers for renewable mini-grids that can also power schools, clinics, and community hubs.

Meanwhile, extending networks to sparsely populated areas is commercially difficult, so the roadmap pushes for shared infrastructure, outcome-based universal service funds, and using public institutions like schools and health facilities as anchor demand to make rural buildouts viable.

Halving the usage gap across the 11 countries studied would bring 245 million people online. Closing it entirely by 2030 could add USD 700 B to Africa’s GDP. But the roadmap is clear that no single intervention will get there, as it recommends that governments must cut taxes on entry-level devices, operators must expand device financing and infrastructure sharing, and development partners must fund the adoption side of the equation, not just the build.

“The goal is ambitious, but it is achievable,” said Ellen Johnson Sirleaf, former President of Liberia and PDAA Co-Chair. “If we bring together connectivity, electrification, affordable devices and digital skills, we can ensure that the continent’s digital transformation leaves no community behind.”

The Push To Close The Gap As Africa’s SMEs Embrace AI But Fail To Reap The Rewards

By Henry Nzekwe  |  September 22, 2026

Ask a room of Nigerian business owners how many have genuinely changed how their business runs using AI, Gori Yahaya says, and you might get ten hands. Ask who has used it to write a product caption or tidy up a message to a customer, and most hands go up.

That gap, between using AI and running on it, is the one Yahaya, founder and CEO of UpSkill Universe, is trying to close. HP and his firm are launching the AI Skills for Business Programme, which will put 55,000 SMEs in Nigeria and South Africa through free, practical AI training on HP LIFE, the HP Foundation’s platform. It follows a pilot that reached 40,000 business owners.

Only 9% of small and medium businesses have embedded AI into day-to-day operations, strategy and decision-making, a recent study found, and nearly 70% are still figuring it out. Yahaya doesn’t read that as an access problem. “People are not short of access,” he tells WT. “What they are short of is a clear view of where in their business AI would make the most difference.”

Two things hold people back, according to Yahaya. Fear, because one automated message quoting the wrong price can lose a customer one spent years earning. And relevance, because nobody has shown a tailor in Aba or a trader in Onitsha what this looks like for a business like theirs. Research he cites finds AI adoption at 75% among large firms and just 24% among firms with fewer than ten staff.

Africa has been here before. Mobile internet reached most people long before most people used it. Only 9% of Africans are outside network coverage, but 63% live inside it and still don’t use the internet; a usage gap seven times wider than the coverage gap. Affordability, relevance and confidence appear to be the blockers, not the network. Yahaya argues AI is tracking the same curve.

What separates businesses getting real gains? Yahaya’s read is that they know which steps of their week could be handled by a machine. “You cannot automate something you have never described,” he says. “They adjust quickly when the naira moves or a supplier disappears. And they’re honest about what the tools get wrong.”

Those who get it right save two to four hours a week. But Yahaya says that number means little on its own. His bigger worry is that one person in a business uses AI well and nobody else ever finds out. “The business has gained almost nothing.”

He expects marketing to change first, because a one-person brand can now produce ad copy and images for Instagram, WhatsApp, TikTok and email in an afternoon, in more than one language, without hiring an agency. Then customer messages, since about a third of online shopping in sub-Saharan Africa happens on social platforms. “WhatsApp is the shop, not the marketing channel. Enquiries arrive at 11 pm and on Sunday afternoons,” he quips.

Then the boring, valuable stuff: stock decisions, pricing when the currency moves mid-month, and turning a year of messy records into accounts a bank will actually accept, he predicts, adding that many Nigerian businesses have years of trading history and no paperwork to prove it, which gets read as unbankable when the real problem is undocumented.

Fully automated customer service, he argues, is oversold. Nigerian customers switch between English and pidgin, and the big global models handle that badly. One benchmarking test done by Intron put a leading global model at a 53.8% error rate across African languages, against 34.3% for a model built for the region. “When half of what your customer says is being misread, nobody is saving any time.”

Against the prevailing sentiments, however, a January study by Google and Ipsos found 88% of Nigerian adults had used an AI chatbot, against a global average of 62%. And 80% were using AI to explore a new business idea or career change, against 42% worldwide. Nigerians are using AI at nearly twice the global rate to figure out what to build next.

Language is where Yahaya sees the opening. “ChatGPT recognises only 10% to 20% of sentences written in Hausa, a language with 94 million speakers. Read that as a gap and it looks bleak. Read it as an opening, and it’s the most valuable ground on the continent, because whoever builds tools that hear African languages properly owns the layer everything else sits on. Regional models are already beating the global giants on African speech,” he emphasises.

What would prove Africa has moved past awareness? Yahaya points away from fintech and startups entirely, instead making the case for poultry farms, building materials, printing, haulage, private schools, and pharmacies.

“If in two years it is still concentrated in Yaba and Sandton, we will not have travelled very far.”