The Promise & Peril Of GenAI Presents Puzzle To African Banks & Fintechs

By Henry Nzekwe  |  September 20, 2024

The integration of artificial intelligence (AI) into financial services is not a new phenomenon. For years, traditional AI has been used by banks and fintechs globally to enhance fraud detection, improve customer experience, and personalise services.

Now, with the rise of generative AI (GenAI), the landscape is shifting further. African financial institutions are beginning to explore how this technology can revolutionise their operations, yet many remain cautious of its potential risks.

In a recent interview with WT, Andrew Mori, co-founder and CEO of Deimos, a fast-growing African cloud engineering and DevOps consultancy, provided insights into how African banks and fintechs can both harness and safeguard against the risks of GenAI. His company, Deimos, has built its reputation by helping organisations, largely in financial services, apply technology optimally, and he sees the rise of GenAI as a critical moment for the financial sector.

However, GenAI adoption in Africa and elsewhere faces challenges such as data poisoning, reverse engineering, and deep fakes. Data poisoning can corrupt AI systems, leading to biased outcomes and increased fraud risks. In Africa, nearly one-third of online verification documents are fake or stolen.

Also, AI-generated synthetic media, are becoming more sophisticated and are being used by criminals to defraud businesses. In a recent Hong Kong case, an employee was tricked into transferring USD 26 M after deepfakes of colleagues, including the CFO, were used in a video call. Recently, a notable crypto firm, Luno, was put on high alert after a deepfake scam targeted an employee, highlighting the rising threat of AI-powered fraud and the need to tread with caution.

The Appeal of GenAI in Financial Services

GenAI transforms fintech by using data to personalise customer experiences and automate tasks. The Nigeria Fintech Marketing Outlook 2024 reveals 29% of fintechs used GenAI for content creation and 14% for workflow automation in 2023. In addition, a recent Gartner report forecasts that over 80% of banks will adopt GenAI by 2026, a significant rise from 5% today, while McKinsey notes its potential to revolutionise banking’s risk and compliance functions.

One of the most exciting applications of GenAI is its ability to significantly improve customer experience. Mori explains that Deimos has already begun implementing GenAI internally to streamline workflows and provide better support for developers. For banks, a similar approach could dramatically improve client services.

“Instead of Googling how to perform an EFT for Kuda Bank or any of the wonderful banks in Nigeria, you can query an AI assistant directly, and they can explain it immediately without asking support,” Mori noted. This kind of instant, AI-driven assistance could transform how customers interact with their financial institutions, making services more accessible and reducing the burden on human customer support teams.

Furthermore, AI assistants could perform actions directly on behalf of users, simplifying complex processes. “For a certain request, it can retrieve information, present creative solutions, and you should be able to ask this assistant to execute something for you,” Mori told WT. Such capabilities would be a game-changer for fintechs looking to provide seamless, intuitive user experiences.

Traditional AI and GenAI: Complementary Forces

Although GenAI holds great promise, it is important to remember that traditional AI is already deeply entrenched in financial systems. Technologies like fraud detection algorithms, credit risk scoring, and personalised recommendations have become standard tools for many African banks and fintechs.

Mori points out that “traditional AI is still very good at things like recommending stuff, personalisation, guessing things… there’s some very strong AI that’s now considered traditional, and that’s very good at fraud detection, for example.” Rather than replacing these systems, GenAI is poised to complement them, Mori figures, by offering more dynamic, creative capabilities, while traditional AI continues to handle structured, data-driven tasks with precision.

This hybrid model—where traditional AI takes care of routine tasks and GenAI enhances user interaction—could provide fintechs with a more robust AI ecosystem, allowing them to address both operational efficiency and customer satisfaction.

Barriers to Adoption

Despite its potential, the adoption of GenAI in African financial services is still in its infancy. According to Mori, one of the main barriers is the complexity of securely implementing GenAI at scale. “The benefit we will bring is deploying GenAI securely at scale,” he says. Security, scalability, and cost control are critical concerns for banks and fintechs considering the adoption of this technology.

There is also an underlying challenge in terms of human capital. Mori worries that the rapid rise of AI, particularly GenAI, could displace junior talent. “I feel like the junior engineer is drying up as a role because I would rather pay 50 cents a day to use an AI assistant… that gives me the same code, even better code than a junior,” he says. The fear that GenAI could reduce entry-level job opportunities in tech is real, particularly in Africa, where youth unemployment is a pressing issue.

Mitigating the Risks

To successfully integrate GenAI while managing its risks, financial institutions must take a thoughtful, incremental approach, Mori advises. One way is to focus initially on low-risk, high-reward use cases such as customer service automation and internal workflow optimisation, areas where Deimos has already seen early success.

Mori also stresses the importance of using AI securely, particularly in sectors as sensitive as financial services. “How to do this securely at scale… that’s probably where the most benefit from our company will come from,” he notes.

Ensuring that AI systems comply with regulatory frameworks, especially around data privacy and financial security, will be essential. The Deimos boss also recommends banks and fintechs invest in ongoing AI audits and monitoring to identify and rectify vulnerabilities before they lead to significant issues.

In addition, Mori emphasises that African fintechs and banks must upskill their workforce to coexist with AI systems. As automation becomes more pervasive, companies must provide training and development opportunities that equip employees with new skills in AI management, data analysis, and strategic decision-making, he explains. By doing so, they can avoid the displacement of workers while benefiting from the enhanced productivity that AI promises.

The Role of African Fintech in Leading the Charge

Africa’s fintech industry has a history of embracing innovation to solve the continent’s unique challenges, from mobile money to crypto exchanges. Chipper Cash, one of Africa’s leading fintech platforms, has deepened the use of technology to enhance cross-border payments and identity verification through its Chipper ID product. With nearly 5 million users, Chipper Cash demonstrates how fintechs can thrive by leveraging cutting-edge technology.

NALA, another thriving African fintech, has developed its own B2B payment platform, Rafiki, to ensure payment reliability, a critical issue in a region where payment infrastructure is often unreliable. These examples show that African fintechs are no strangers to technological innovation, and their success with traditional AI bodes well for their ability to integrate GenAI in meaningful, secure, and scalable ways.

The adoption of GenAI in African banks and fintechs offers immense possibilities, from improving customer experiences to streamlining backend operations. However, it is essential to move cautiously, focusing on secure, scalable deployments and the upskilling of the workforce. With the right strategies in place, GenAI could become an invaluable tool in the continued growth and transformation of Africa’s financial services sector.

As Mori succinctly puts it, “It’s very easy to implement technology in the wrong way… but we really want to help companies use technology in the right way.” African banks and fintechs have the opportunity to lead the way in harnessing the power of GenAI, especially if they do so thoughtfully and responsibly.
The Friends-Turned-Founders Building The Missing ‘Paper Trail’ That Haunts Africa’s Remote Workers

By Henry Nzekwe  |  September 14, 2026

Jennifer Echenim was working remotely for international companies not that long ago, earning money that arrived in fits and starts through a patchwork of platforms.

Withdrawing it meant routing funds through a friend, converting to stablecoins, and navigating peer-to-peer exchanges to access naira. Each step cost money, time, and documentation she thought was unnecessarily complicated.

The real trouble surfaced later, when she moved to the UAE. Opening a local bank account required proof of income, and the financial records her employment history had generated were not recognised by the systems she encountered there. The problem was not getting paid, as it turned out, but proving she had been, because while the money had arrived, the pesky paper trail had not.

“The financial records from my employment history were not recognised by the systems I encountered there,” Echenim says. “So I began thinking more deeply about it.”

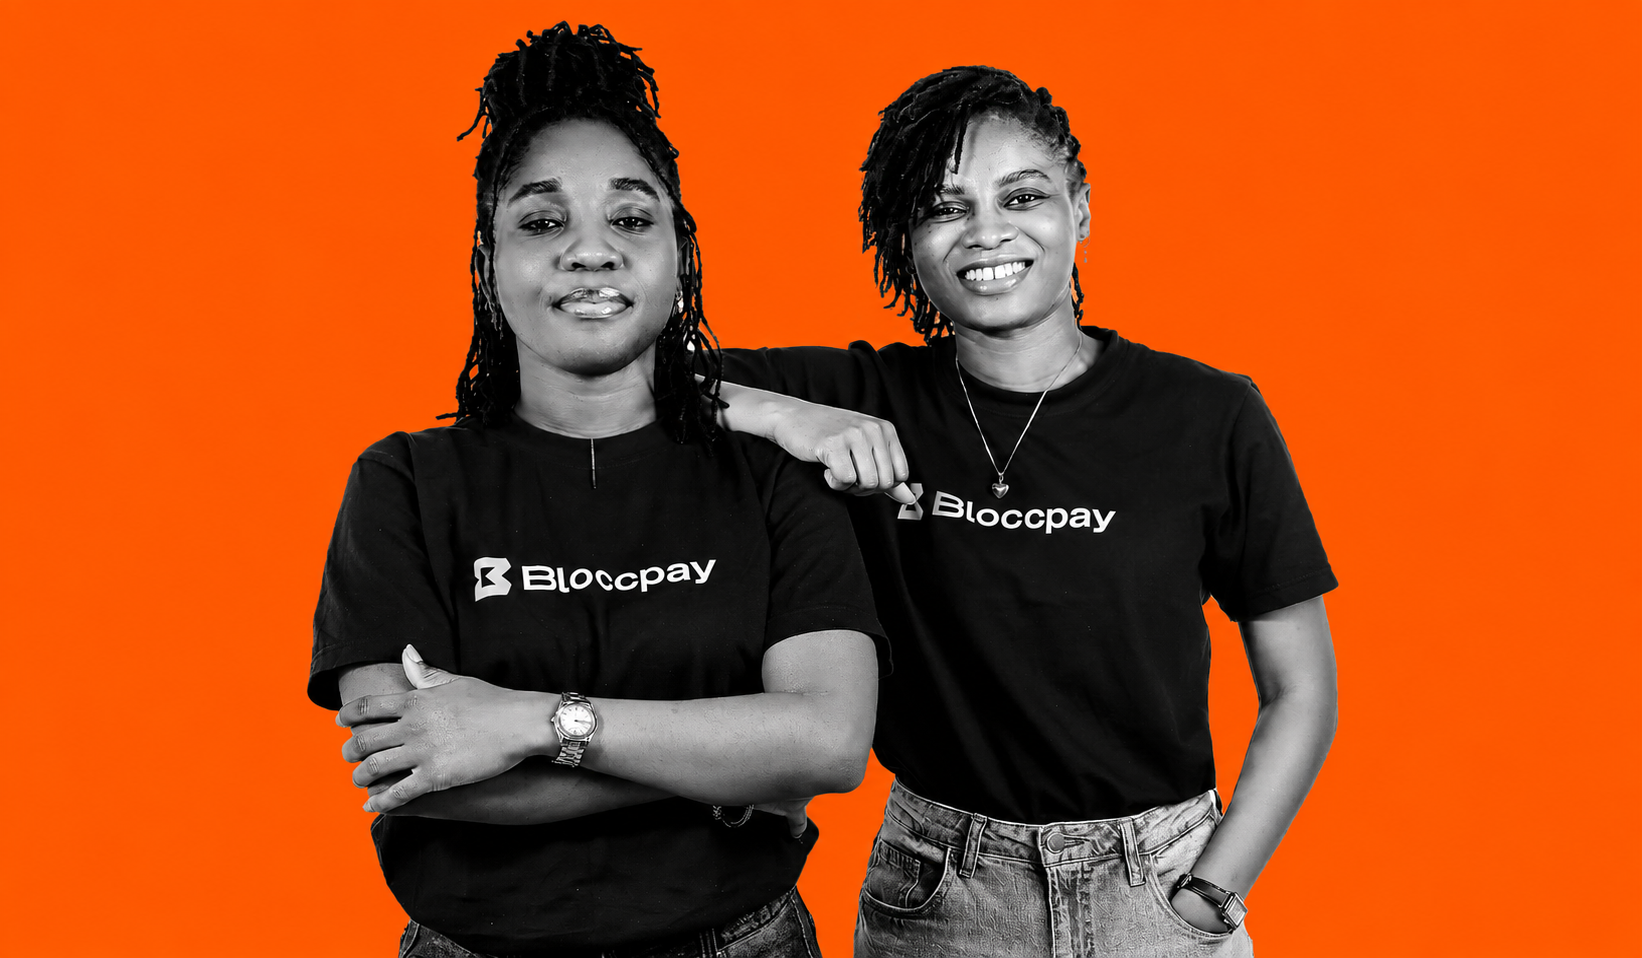
That experience led her, alongside friend-turned-co-founder Ajoke Asunmonu, who had sometimes assisted Echenim with workarounds for her pay headaches, to build Bloccpay, a stablecoin-powered payroll platform for cross-border workers and the businesses that employ them.

The company is now in private beta across Nigeria, Kenya, Ghana, and South Africa, with business customers primarily in the US and UK. Its gross transaction volume grew sevenfold quarter-on-quarter in Q2 2026, and by mid-year it had matched its total volume for all of 2025.

***

An estimated 15 to 20 million African workers now earn across borders. Research from Harvard Business School puts the cost of moving that money at 8.7% to 12.6% of transaction value, well above the 3% target set by the UN. Cutting those costs by half could generate between 900,000 and 1.1 million remote jobs across the continent and add USD 3 B to Africa’s remote work exports.

But Bloccpay’s founders argue the payment itself is only half the problem, emphasising that the other half, what happens after the money lands, is equally critical.

“Traditional employment produces that record as a byproduct,” Asunmonu says, referring to the payslips, tax documents, and recurring credits that salaried workers accumulate. “Independent and cross-border work produces nothing equivalent.”

Ajoke Asunmonu

Asunmonu calls this missing layer “financial identity.” Every invoice raised and payment received on Bloccpay generates a trail showing who paid whom, how much, when, in what currency, and through what channel.

Over time, those records build into a documented history of a worker’s earnings that can be used to apply for a loan, rent a home, apply for a visa, or file taxes. The platform is also planning a feature that lets users upload invoices generated outside Bloccpay, so their history lives in one place.

It is a straightforward idea with an uncomfortable implication. Existing payment platforms, including the ones Echenim used, are designed to move money from point A to point B. Once the transaction clears, the job is done.

“What they weren’t building was the layer underneath,” Echenim says. “The record of the transaction, the documentation it creates, and the financial history it builds over time for the person receiving the money.”

***

The technical machinery behind Bloccpay is more complicated than the pitch suggests. The platform settles transactions in stablecoins like USDC and USDT and runs multichain across Stellar, Base, BSC, and Solana, routing around the high Ethereum fees that made Echenim’s own payments expensive.

Stablecoins are digital tokens pegged to currencies like the US dollar, designed to hold a steady value. They allow money to move across borders without the foreign exchange losses that traditional rails impose.

Africa already has the highest stablecoin ownership rate globally at 79 percent. But while the rails are mature and the cost problem is largely solved on the sending side, the receiving side is where it gets hard.

“Moving that into a bank account or mobile money is where the real work sits,” Echenim says. “Every corridor is its own piece of work. Local partners, local settlement times, local failure modes. Nigeria doesn’t work like Kenya.”

Jennifer Echenim

That operational reality has changed how the company thinks about expansion. “We used to talk about adding countries,” Echenim says. “Now we talk about corridors, because a country isn’t live until money lands the way people there actually get paid.”

The founders are equally blunt about what they got wrong early on. Echenim, had lived with the problem and spent six years building on blockchain, says her engineering instinct was to map every point of friction and abstract it away. What she did not map was where compliance sat. Some of those friction points, she says, “exist for a reason, and you have to design around them rather than through them.”

Asunmonu’s correction came at 3am on December 2, 2025, when a customer needed to pay contractors for the previous month. Bloccpay only supported future-dated payroll. The customer was ready to go back to spreadsheets and manual transfers.

“We had built for the version of payroll that exists in a diagram, not the one that exists in a company,” says Asunmonu, who spent years at Flutterwave managing enterprise payments accounts, seeing where cross-border flows break at scale.

The team shipped backdated payroll and automatic prorated calculations off the back of that call. “They aren’t edge cases,” she says of the messy realities of real-world payroll. “They’re most of it.”

***

The hardest assumption to prove wrong, both founders agree, is institutional recognition. A bank or consulate will not accept a new kind of income record because the company explaining it is persuasive. “They accept it when it’s familiar, when enough of it exists, and when it resembles documentation they already trust,” Asunmonu says. “Recognition follows the record, not the other way around.”

That is a function of time and volume, and Bloccpay is early on both. The platform is a recipient of a USD 100 K Stellar Community Fund Build Award and a member of the Circle Alliance Program. 

It has matched a full year of 2025 volume in the first half of 2026. One customer started at around USD 1.5 K a month and now runs USD 22 K, growing roughly fourteenfold as they moved more of their payroll onto the platform.

“Aggregate growth can be new sign-ups,” Asunmonu says. “Expansion like that only happens when a business decides to trust you with more.”

For Echenim, the more pointed lesson is about the market itself. “The thing I’ve felt most isn’t about being a woman,” she says. “It’s about building for a market people have already decided isn’t commercially interesting.”

That assumption, she says, shapes everything. How much capital is available. How much explaining you have to do before anyone engages with the product. How often you are asked whether the volumes are really there.

“We’ve had to prove the market exists before we could argue we’re the right people to serve it,” she says. “Most founders only have to do the second part.”

Asunmonu frames the challenge differently. “It has shown me how uneven access can be. Funding, networks, and access to the rooms where decisions are made are not equally distributed, and you feel that as a woman building in a technical space.”

Bloccpay’s bet is that as hiring becomes more global, the financial systems of the countries where workers live will eventually have to recognise income earned across borders.

Time will tell whether that recognition arrives because the records become too voluminous to ignore, or whether the founders run out of runway waiting for institutions to catch up. For now, they are building the records and hoping the recognition follows.

MNT Halan’s Cairo Listing Flies In Face Of African Fintech IPO Exodus

By Staff Reporter  |  September 11, 2026

On Tuesday, MNT Tech Holding for Financial Investments, an arm of Egyptian fintech unicorn MNT-Halan, submitted a formal application to list 1.6 billion shares on the Egyptian Exchange’s main market. The filing caps months of speculation about the company’s public market ambitions and sets up a potential IPO that could value its domestic operations at between USD 900 M and USD 1 B.

The move comes as Africa’s largest fintech players race toward public listings in a remarkable synchronised wave. OPay has hired Citigroup, Deutsche Bank and JPMorgan for a US IPO targeting a USD 4 B valuation, while also weighing a secondary listing in its primary market, Nigeria. PalmPay is preparing a Hong Kong listing. Airtel Money has chosen London, where it could be valued at roughly USD 10 B. All three are Nigerian-linked businesses, and all three are listing abroad. MNT-Halan is the only one heading to a local bourse.

It raises questions that should worry policymakers from Lagos to Nairobi as to why Africa’s most successful fintech companies, built on African consumers and transaction volumes, taking their equity stories to New York, Hong Kong and London instead of staying home,

MNT-Halan’s decision to list in Cairo offers one possible answer. The company, founded in 2018, has grown into a vertically integrated fintech platform offering micro-business lending, payments, consumer finance, and e-commerce. It now serves more than 7 million customers in Egypt alone and has disbursed over USD 10 B in loans since inception.

In June, Al Ahly Capital, the investment arm of the National Bank of Egypt, led a funding round that lifted the company’s overall valuation to USD 1.4 B. The IPO would cover only the Egyptian business, leaving operations in the UAE, Turkey and Pakistan private.

The listing is also a test for the Egyptian Exchange. The benchmark EGX index is up over 23.6% year-to-date, and local fintech Valu saw its shares jump 852.4% on its first day of trading last year. But the exchange still lacks the depth to compete with global venues.

Moreover, considering MNT-Halan’s peers elsewhere, for instance, a survey found that 76.5% of Nigeria-funded startups hold dollar capital, making exchange rate instability a critical factor in listing decisions. Companies generating revenue in naira but seeking dollar exits face a currency mismatch that local markets cannot easily resolve. The Nigerian Exchange has recorded zero startup IPOs.

MNT-Halan is betting that Egypt can offer something different. The company holds more than 25% of the country’s microfinance market and has positioned itself as the seventh-largest financial institution in Egypt by reach. Its deep local roots, combined with a domestic investor base that has already demonstrated appetite for fintech stocks, may make a Cairo listing more viable than it would be for a Nigerian counterpart. The Egyptian government, meanwhile, has been actively supporting digital transformation and broadening access to financial services through technology-driven platforms.

Terra Industries’ First Commercial Deals Stoke Race For Nigerian Lithium Amid Concerns

By Staff Reporter  |  September 11, 2026

Terra Industries’ commercial division is barely a week old and already paying for itself. The Nigerian defence-tech startup disclosed today that it has closed USD 2 million in contracts to protect lithium mining operations in Nigeria.

The company will deploy 20 sentry towers and four Iroko drones across two mining sites, providing surveillance, real-time threat detection, and response through ArtemisOS, its autonomous command-and-control layer. More sites are expected to come online as the operators expand. 

The contracts are a quick validation of Terra’s new commercial push, led by Todd Stiefler, the Palantir alumnus appointed director of commercial in August. The division was built to sell autonomous security systems to private infrastructure operators across Africa, the Gulf, South America and South Asia.

Until now, Terra’s work has been split between government clients and commercial operators, but the new unit formalises the push into private sector security. The company says its systems already protect assets worth about USD 11 B, mostly in energy and mining.

Lithium is a strategic mineral for Nigeria. In May, authorities arraigned 15 Chinese nationals and nine Nigerians over alleged illegal mining in Nasarawa State. The government is trying to attract investment into battery-material processing, but artisanal and organised illegal operations have made securing these assets a national priority.

Terra is selling itself as the technological answer to a problem the state has struggled to police. The company says its in-house manufacturing of airframes, propellers, battery packs, and software allows it to cut hardware prices by up to 55% compared to international competitors.

The new contracts, however, put the sovereignty debate in sharper relief. Terra often reiterates that its mission is to give the Global South the technological edge needed to secure its future. But its funding comes from 8VC, the firm with ties to foreign intelligence actors founded by Palantir co-founder Joe Lonsdale, and its commercial division is now led by a Palantir veteran.

The lithium mines Terra is now protecting sit at the centre of Nigeria’s resource sovereignty ambitions. Who controls the data flowing through those sentry towers and drones could be consequential. Mining security data includes movement patterns, operational vulnerabilities, and real-time surveillance feeds, intelligence that could be as valuable as the lithium itself.

Terra has not disclosed the names of the two mining companies, nor the specific locations of the sites. The company says deployments will expand as each operator brings additional sites online. For now, the contracts are a commercial win and a political test. Terra has proven it can sell. Whether it can deliver sovereignty, on its own terms, is still unproven.

South African VC Returns Rival Developed Markets As Exits Surge Counters Scepticism

By Staff Reporter  |  September 11, 2026

One of the perennial gaping holes in African venture capital’s growth story, exits, is finally starting to close in South Africa.

New data shows 226 realised exits since 2009, returning more than ZAR 2.9 B (~USD 175 M) to investors at a 2.45x multiple. That performance matches or exceeds US and European benchmarks, upending a decade of LP reluctance based on a perceived lack of exit history.

For years, global backers passed on African markets, branding them too risky with no track record for getting money out. They often cite a lack of exit history and, as a result, are hesitant to commit. The data, however, tells a different story.

A pair of new studies from the SA SME Fund, Endeavor South Africa and SAVCA have pulled together a comprehensive picture of South African venture capital exits. The numbers tell a story that doesn’t match the narrative that has dominated LP due diligence calls for the better part of a decade.

Between 2009 and 2026, South African fund managers reported 226 realised exits. The capital-weighted realised returns ranged from 2.01x to 2.45x invested capital. For every rand invested in exited deals, the reported portfolio returned ZAR 2.45 in realised cash proceeds before fund-level costs, fees and taxes.

Compare that to the numbers the industry treats as gospel. The US sits at 2.0 to 2.3x. Europe at 1.7 to 2.1x. The UK at 2.2x. South Africa matches or beats every one of them.

“African VC does not have an exits problem,” said Wura Kayode, founder and CEO of FundFlow.VC, in her analysis reacting to the findings. “It has a perception problem.”

The data bears that out. Of the 226 exits analysed, the majority were profitable. Losses and write-offs occurred at expected levels for venture capital investing. The median realised investment was modestly profitable. And like venture markets everywhere, a relatively small number of high-performing investments drove a significant share of total value creation, mirroring the power-law return profile observed internationally.

The South African story is particularly interesting in how the exit landscape has shifted. For most of the past decade, a South African tech founder looking to sell had to hope a foreign buyer came knocking. That has changed.

Domestic mergers and acquisitions, led by the country’s banks, have emerged as a major exit route. Nedbank bought payments fintech iKhokha in a ZAR 1.65 B deal. Capitec acquired WalletDoc. TymeBank swallowed SME lender Retail Capital. Lesaka Technologies took over payments group Adumo. Mastercard is pursuing a deal for BVNK. Motorola Solutions bought RapidDeploy. Ticketmaster acquired Quicket. And Optasia listed on the JSE.

“Between 2015 and 2020, the businesses that exited were all sold to international companies,” said Endeavor South Africa managing director Alison Collier at a briefing on the research. “That changed in the early 2020s. Now we’re seeing many more local corporates looking to acquire”.

SAVCA investment data suggests the emergence of a second investment cycle from 2019 onwards, characterised by a marked increase in new deal activity. More than 1,100 companies have received VC funding since 2016. With a median holding period of around six years, much of the capital deployed in recent years has yet to reach typical exit maturity. The first wave of related exits is only beginning to emerge from 2024 onwards.

There are caveats, however. The research reports only the portion of exit value attributable to the reporting fund manager’s equity stake, meaning the actual market valuations at exit were often larger. Data collection relied on fund manager self-reporting, and 43 confirmed profitable exits did not disclose exit values, meaning the reported aggregate proceeds almost certainly understate actual realised value.

But the broader point stands that South Africa’s venture capital ecosystem is producing realised returns comparable to more mature international markets.

How A ‘Tiny’ Trade Four Years Ago Shook Africa’s Biggest Bitcoin Company

By Staff Reporter  |  September 4, 2026

Africa Bitcoin Corporation, the continent’s first listed company to adopt bitcoin as a treasury reserve asset, was days away from a landmark secondary listing on London’s Aquis Growth Market. Instead, its founder and CEO Warren Wheatley, his wife Tatum Keshwar-Wheatley, and chief investment officer Akshay Karan are now banned from South Africa’s financial services industry for 20 years.

The Financial Sector Conduct Authority dropped its enforcement action on 30 August 2026, revealing that the three executives coordinated trades over just four days in September 2022, when the company was still called Altvest Capital and listed on the Cape Town Stock Exchange.

According to the FSCA, they created an artificially inflated share price and a false impression of demand. The regulator imposed a combined ZAR 10 M in penalties: ZAR 5 M on Wheatley and his company WGW Capital, ZAR 3 M on Keshwar-Wheatley and her firm, and ZAR 2 M on Karan. All three have been debarred for two decades.

The trades happened in September 2022, just four months after Altvest’s initial listing. At the time, the stock was thinly traded, meaning relatively modest transactions could swing the price significantly. The executives have disputed the findings, arguing the amounts involved were tiny and that they were merely testing whether tax was being applied correctly. The FSCA rejected this, saying the issue was not the amounts but the harm caused and the intent behind the trades.

The company’s board learned of the FSCA decisions on 30 August. By the next day, Wheatley and Karan were on precautionary leave, Keshwar-Wheatley’s consulting services were suspended, and Stafford Masie, an existing executive director, was installed as interim CEO. The company has been at pains to clarify that the FSCA made no findings against any entity within the group, only the individuals.

Masie struck a measured tone in his first public remarks. “We are sympathetic to what Warren, Akshay and Tatum are experiencing,” he said. “They have played an important role in building an incredible business.” But his priority, he added, is to “hold the line, providing stability, protecting what has been built” while the three challenge the FSCA’s decision.

The irony is that the company’s entire pitch to London investors was built on the credibility of its leadership. Africa Bitcoin Corporation holds 5.53 bitcoin on its balance sheet, worth about ZAR 6.68 M, and lends to African small and medium-sized businesses. It is listed on the JSE, A2X, the Namibian Stock Exchange, and the OTCQB in the US.

The London listing was meant to be the capstone of an ambitious expansion, giving UK and European investors direct access to what the company calls the world’s first bitcoin-backed SME growth accelerator. That pitch now has a hole in it.

South Africa has licensed more than 300 crypto asset service providers and is building one of the continent’s more robust regulatory frameworks for digital assets. The regulator has been conducting supervisory inspections and establishing engagement forums with the crypto industry. Debarment is one of the most consequential tools in its arsenal, and it has now used it against the founding team of Africa’s most visible bitcoin company.

Wheatley, through his company email, told ITWeb that he will not litigate the matter in public. But the Financial Services Tribunal will hear his case. For now, the company is in damage control mode, trying to convince investors that the entity itself remains sound even as its founders are cast out of the industry they built.

As Uber Quits Nigeria, A Plucky Startup Just Launched A Timely Alternative

By Henry Nzekwe  |  September 4, 2026

Barely days after Uber shut down its operations in Nigeria, a local mobility company launched a service that looks a lot like what Uber left behind, but with a twist.

Shuttlers, the technology-enabled shared mobility platform known for its bus service, announced the launch of Shuttlers Pod on Friday, a scheduled door-to-door car service for commuting to work, events and other destinations across Lagos.

The service matches three to four riders travelling the same route, picking each up from their doorstep and dropping them at their exact destination, with the option to book the vehicle privately. Every trip comes with a named driver, a fixed fare and a guaranteed pickup, with no surge pricing or roadside negotiation.

The timing is hardly coincidental. Uber’s exit after 12 years in Nigeria left a vacuum in the market for scheduled, predictable urban transport. The company’s departure was part of a global restructuring that saw it also exit Uganda, as it pivots aggressively toward autonomous vehicles and robotaxis. But in Lagos, where the average commuter spends more than 30 hours a week trapped in traffic, the need for reliable mobility has not diminished. Shuttlers Pod looks like an attempt to fill that gap on its own terms.

The service applies Shuttlers’ scheduled bus model to private vehicles, replacing the traditional bus stop with door-to-door pickups and drop-offs. Shuttlers claims each Pod trip costs roughly 50% less than typical ride-hailing fares, enabled by its advance-booking and fixed-pricing model.

The company says its existing bus service already saves commuters between 60% and 88% on transport costs compared to ride-hailing, while reclaiming eight to 12 hours from gridlock every month. Pod extends that logic to smaller vehicles and more personalised trips.

Shuttlers is no newcomer. Founded in 2016, the company recently surpassed 10 million completed journeys and became Nigeria’s first private mobility operator to be listed on Google Maps Transit. It serves more than 600,000 monthly trips across more than 1,000 itineraries in 400 routes, operating more than 430 buses daily across Lagos, Abuja and Port Harcourt. The company reports a 99% trip completion rate and a 99.94% incident-free record since launching.

Nigeria’s ride-hailing sector is valued at around USD 450 M and projected to reach USD 879 M by 2031, with over 200,000 drivers. Uber left a growing market it could not profit in on its own terms. Every remaining platform inherits the same fuel, maintenance and affordability squeeze that made Uber’s position untenable.

Bolt has emerged as Nigeria’s most downloaded mobility app, overtaking Uber and inDrive, while inDrive and local platform LagRide continue to operate. But none of them offer a scheduled, fixed-price ride from door to door, booked in advance, which is what Shuttlers Pod promises.

Nigeria’s cost of living is rising faster than incomes. With that reality, the smartest way to move people is through shared mobility, said Damilola Olokesusi, CEO and co-founder of Shuttlers.

“We’ve spent the last decade making scheduled, shared transport reliable and affordable, and Shuttlers Pod brings that same thinking to scheduled private and shared trips that are safe, premium and affordable, from your doorstep to exactly where you need to be,” she said.

For now, Shuttlers Pod is open for waitlist sign-ups. Whether Lagos commuters, still adjusting to life without Uber, will embrace a service that asks them to plan ahead rather than summon a ride on demand is the ultimate question. But in a city where traffic is the only certainty, advance planning might be exactly what works.

Fintech Founders’ Arrest Rocks Kenya With 200,000+ Customers & Retailers Stranded

By Staff Reporter  |  September 3, 2026

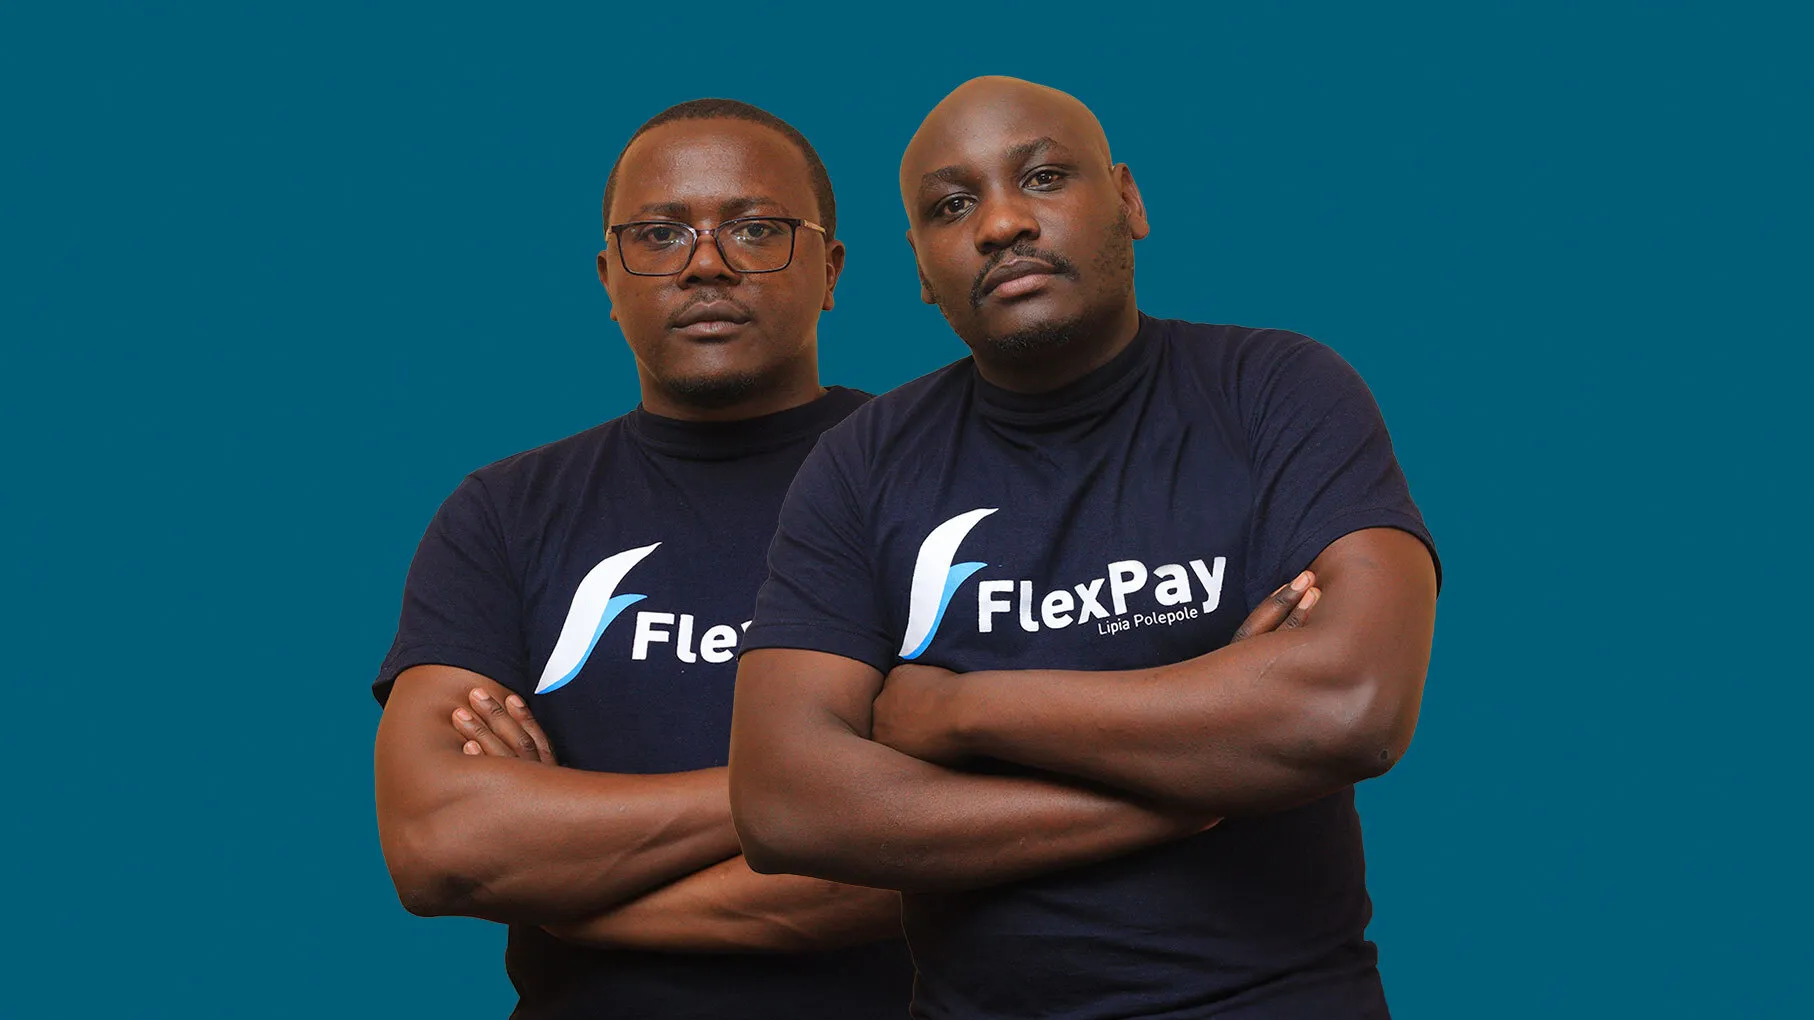
For three years, FlexPay sold Kenyans a fintech fairy tale, offering a save-now-buy-later platform built on the promise that Kenyans did not need more debt, only more discipline, and that the company holding their money in the meantime could be trusted with it.

That promise collapsed on 1 September when detectives from the Directorate of Criminal Investigations walked into Roysambu and walked out with two of Flexitech Group Limited’s own directors in handcuffs. Martin Kariuki Maina and Johnson Gituma Mwangi, the latter a co-founder and the company’s long-serving chief operating officer, are accused of stealing over KES 30 M (nearly a quarter of a million dollars) belonging to an unnamed major retail chain.

According to the DCI, the pair were acting as collection agents for the retailer, receiving funds from customers who had purchased and picked up goods from several branches. Instead of forwarding this money to the company, they allegedly diverted it for personal use.

FlexPay’s entire model relies on trust. The platform offers a digitised version of the old East African lay-by system, letting shoppers pay for a fridge or a school uniform in instalments and collect it once the balance is cleared. It identified as a payment facilitation and savings platform, not a lender. The company offers goal-based savings products and a group savings feature known as FlexPay Chama.

That framing did real work for FlexPay. It let the company sit outside the perimeter that usually catches deposit-takers and digital lenders in Kenya, even as its products did precisely what banks and saccos do: collect money from ordinary Kenyans and promise to give it back at a later date.

By September 2023 the company was telling TechCrunch it had signed more than 600 merchant partners and served over 200,000 customers, part of the pitch that carried it into TechCrunch’s Startup Battlefield 200 and, later, into the second cohort of Safaricom’s Spark Accelerator in October 2025.

Long before the DCI arrived, customers were already expressing their frustrations. In July, one customer reached out to a Kenyan blogger, desperate for assistance after waiting six weeks for a KES 13 K (USD 100.00) refund. He had contacted the company repeatedly, but was continually met with promises that his refund was being processed without any clear timeline. By August, another customer shared a similar experience: KES 24.7 K (USD 190.00) had not been returned since July. Because of this delay, she was unable to send her child back to school.

These breakdowns in trust became evident through customer reviews on Google Play, especially leading up to mid-2026. Feedback consistently mentioned withdrawal requests taking much longer than anticipated, and customer support being noticeably lacking. One customer shared their experience of waiting for a KES 15 K (USD 115.00) refund from June, which still hadn’t arrived by July. According to FlexPay’s terms, refunds are supposed to be processed within 14 working days, yet many customers reported waiting for months without any resolution.

FlexPay is not the first Kenyan buy-now-pay-later alternative to run into trouble. The sector has seen some turbulence and also been under pressure over alleged predatory lending, fueling the push for regulation. But this case is less about aggressive lending practices or high interest rates, and more about a company that positioned itself as a trustworthy steward of customer savings, a platform that promised financial empowerment without debt, and whose founders now stand accused of simply taking money that was never theirs to keep.

How A Fabricated Notice Nearly Broke A Nigerian Fintech Giant

By Henry Nzekwe  |  September 2, 2026

On Sunday, August 30, a message began circulating across Nigerian social media and messaging platforms, quickly getting serious mileage. It looked official, an “Official Note” from OPay Digital Services announcing that the company would suspend all transactions and account-related services from September 1, 2026, for a “long indefinite break.” Customers were advised to withdraw their funds “as soon as possible.”

Within hours, panic set in and withdrawals spiked. A fintech that serves an estimated 46 to 50 million users across Nigeria, supports over one million merchants and employs more than 7,000 people, was suddenly facing something that looked alarmingly like a bank run.

OPay moved fast. On Monday, it took to X to declare the notice false and inserted app banners notifying users of the falsehood. By Tuesday, it had released a video debunking the rumour. On Wednesday, the company held a press conference in Lagos, its top executives flanked by lawyers, making it abundantly clear that OPay was not going anywhere.

“Dem say we dey shut down September 1, today na September 2, we still dey veri active and transactions still dey go on normal,” said Dotun Adekunle, OPay’s chief operating officer and chief technology officer, speaking in Pidgin. “We dey here, we no dey run wit your money, we dey gidigba.”

But the company’s response went beyond reassurance. OPay has engaged the Department of State Services and the Nigeria Police Force to investigate the source of the false information. It has already commenced legal action against at least one individual.

“Anyone who deliberately engages in similar conduct should expect decisive legal action and the full consequences provided by the law,” said Akinfolabi Rokosu, OPay’s chief legal counsel.

This is not an isolated incident. OPay has faced similar rumours before, in 2024 and again in November 2025, when false claims circulated that it had shut down or that customer deposits had been wiped out. Other major Nigerian corporations, including MTN, Wema Bank and pharmaceutical company May & Baker, have also been targeted by fake shutdown announcements in recent months.

***

Earlier this year, the Central Bank of Nigeria upgraded OPay’s operating licence to national status, along with those of Moniepoint, Kuda Bank and other major fintechs. The upgrade formally recognised that these companies had expanded far beyond their original licence scopes and now operate across all 36 states. OPay, backed by SoftBank and Sequoia Capital and valued at USD 2 B, is preparing for a potential US initial public offering, while also weighing a secondary listing in Nigeria.

Yet for all its regulatory validation and institutional backing, a single piece of fabricated information shared across WhatsApp and X was enough to send millions of customers rushing to withdraw their money.

Olalekan Disu, executive at eTranzact and financial secretary of the Association of Licensed Payment Operators of Nigeria, said the threat goes beyond OPay. “Trust is the foundation of digital payments,” pointing out that when false information about a major player spreads, it does not just undermine one company but discourages adoption of digital payments across the board.

OPay has spent the years since its 2018 launch building a platform that helped millions of Nigerians navigate everything from daily transfers to the cash crisis of 2022 and 2023. Its green agent terminals have become a ubiquitous sight across the country. That infrastructure, and the trust it represents, is now being tested, not by usual regulatory or competitor adversity, but by the speed and reach of misinformation.

The company’s response, involving both state security agencies and the courts, signals that it views this as an existential threat. Rokosu said the action was necessary to ensure accountability and customer protection. But the deeper question is whether any amount of legal enforcement can keep pace with how easily fake news can be manufactured and spread.

OPay is still standing. The false shutdown date has passed, and transactions are flowing. But the episode has exposed a vulnerability that no amount of venture capital or regulatory approval can fully insulate against. In a country where digital finance has become essential infrastructure, the rumour mill is a systemic risk that the industry has only begun to confront.

Uber Pulls Out Of Nigeria, Its Last Major African Frontier, Having Fallen Behind

By Staff Reporter  |  September 2, 2026

Uber officially shut down its ride-hailing operations in Nigeria today, September 2, ending a 12-year presence in Africa’s most populous nation. The company also exited Uganda on the same day, part of a global restructuring that will cut roughly 3,300 jobs, or about 10 percent of its workforce. In a statement, Uber said the decision followed “a thorough review of our business” and thanked Nigerians for trusting the platform since it launched in Lagos in 2014.

It is the latest in a pattern of retreat from African markets where the economics of ride-hailing have become increasingly untenable. In January, Uber shut down in Tanzania after nearly a decade, citing a regulatory environment that made profitability difficult. Last year, it closed operations in Côte d’Ivoire. The withdrawals come as Uber pivots aggressively toward autonomous vehicles, planning to invest more than USD 10 B in robotaxis and aiming to offer driverless rides in 15 cities by the end of 2026.

For Nigeria, the departure is a significant blow to a digital economy that had developed with the platform in an often fraught landscape. Uber estimated in 2023 that it generated an additional NGN 6.1 B (USD 9.6 M) in annual income for Nigerian drivers compared to traditional alternatives.

Yet drivers have long complained that the math does not work in their favour. They face rising fuel costs, vehicle maintenance expenses, and commissions as high as 25 to 30 percent. In March, hundreds of drivers in Lagos went on a three-day strike over low fares and high commissions, logging off platforms including Uber, Bolt, and inDrive. “Drivers operating on platforms such as Uber, Bolt, inDrive, and Lagride face rising operational costs, including high fuel prices and vehicle maintenance,” one union leader said at the time.

The tensions have fuelled a conversation about local alternatives. After the March strike, drivers began discussing the creation of homegrown apps to regain control over pricing and commissions. Those conversations now take on new urgency. Bolt, which has overtaken Uber as Nigeria’s most downloaded mobility app, remains the dominant player. InDrive and local platform Lagride also continue to operate. But Uber’s exit leaves a gap that’s now up for grabs.

Regulatory friction has also mounted. In August, the Federal Airports Authority of Nigeria suspended Uber and Bolt from operating at airports, causing fares to surge and passengers to face long delays. The ban was later partially resolved, but it underscored the uneasy relationship between global platforms and local authorities.

Uber says it remains committed to Sub-Saharan Africa and that the withdrawals from Nigeria and Uganda will not affect its operations elsewhere on the continent. But the company is also reducing fully remote roles to about 1 percent of its workforce and flattening its corporate structure. CEO Dara Khosrowshahi has said the rapid expansion over the past five years created organisational complexity that slowed decision-making. The restructuring is meant to redirect resources toward areas with greater growth potential, including autonomous mobility.

The Hidden Cost Of Kenya’s YouTube Tax Stings The Smallest Creators Hardest

By Staff Reporter  |  September 2, 2026

When Google started sending notifications to Kenyan YouTubers in late August asking for their KRA Personal Identification Numbers by October 1, the reaction was swift. Media personalities shared screenshots of said notification across social media, prompting heated discussions among followers. Actor and content creator Abel Mutua voiced what many were thinking: “You can tax us, but we don’t see where the money is going.”

The tax itself is not new. Kenya’s Finance Act 2023 introduced a 5% withholding tax on digital content monetisation for resident creators, down from an originally proposed 15%. At the time, it was framed as a concession. Kimani Kuria, who chaired the Finance and Planning Committee, said the reduction aligned digital creators with other professionals like lawyers and accountants who also attract a 5% withholding rate. The law took effect on July 1, 2023.

What changed is enforcement. For three years, the tax existed mostly on paper. Creators were expected to self-declare and settle at year-end, a system that relied heavily on voluntary compliance. Now Google is doing the deduction at source, automatically withholding 5% from monthly YouTube earnings before creators see the money. The first deduction applies to September 2026 earnings paid out in October. Creators who don’t submit a verified PIN by October 1 will have their payments held.

The Digital Content Creators Association of Kenya (DCCAK) has asked the National Treasury and KRA to suspend enforcement, calling the rollout an “ambush.” The association argues that creators have been given weeks to comply with an obligation that has existed in law since 2023, with no meaningful consultation on how it would be administered.

The deeper grievance is structural. The 5% is deducted from gross earnings, not net profit. A creator earning KES 100 K loses KES 5 K before accounting for internet data, cameras, editing software, studio hire, or crew payments. For small and emerging creators with thin, irregular margins, that deduction can make it harder to recover production costs. Established creators with predictable incomes may absorb it more easily, but the sector’s growth depends on the newcomers, not the few who have already made it.

There is also confusion about how the withheld amount interacts with annual income tax. KRA describes withholding tax as an advance credit against a creator’s final income tax liability, not a final tax. But DCCAK says creators haven’t received clear guidance on how that credit will appear on their KRA accounts, how to claim it, or how long refunds will take if the withheld amount exceeds what they ultimately owe. That uncertainty leaves creators guessing whether they’re paying 5% or possibly more.

Kenya’s approach puts it ahead of most African markets. Google does not withhold local tax from AdSense payments in Nigeria or South Africa, where creators are expected to declare platform income independently. Tanzania introduced a similar 5% withholding tax on digital content creators through its Finance Act 2024. Nigeria’s withholding tax regulations also apply a 5% rate to royalties paid to creators. But in those countries, enforcement remains patchy. Kenya is the first where a major platform is actively deducting at source.

Despite ongoing protests, the October 1 deadline stands for now, and creators who don’t comply won’t get paid. The tax is coming, whether they are ready or not.