Tech Giants’ Retreat From Africa Continues As Microsoft Guts Kenyan Engineering Hub

By Staff Reporter  |  October 13, 2026

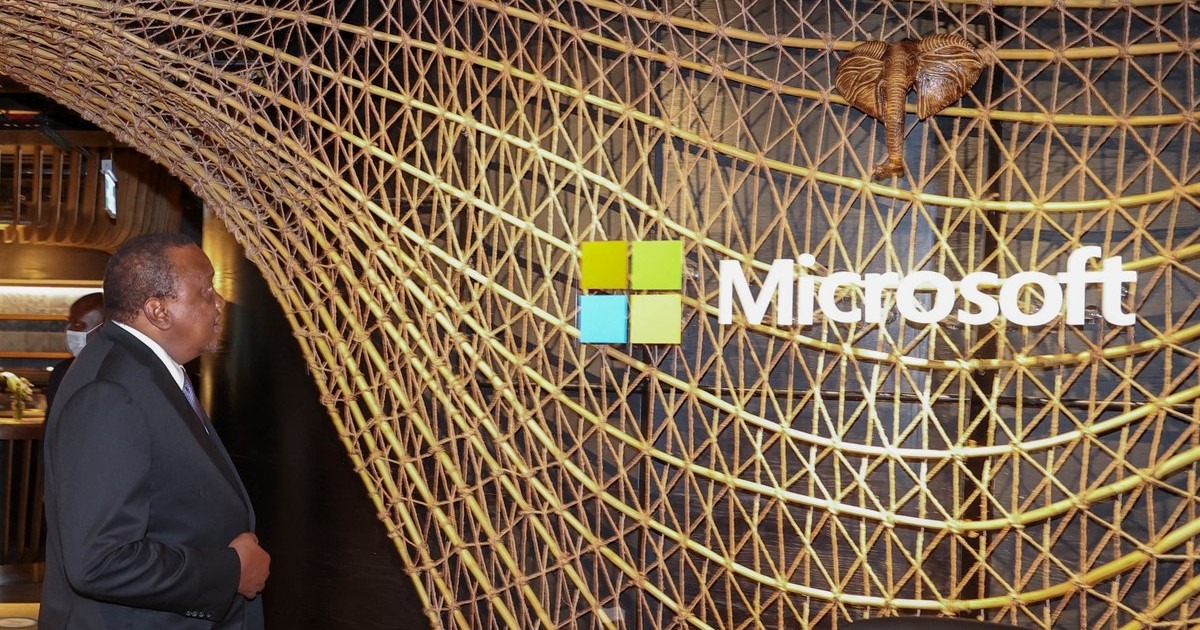
Microsoft has told staff at its Africa Development Centre in Nairobi that the engineering hub will close, ending a seven-year, USD 100 M bet on building global products from Africa and putting nearly 400 jobs at risk.

The decision, communicated to employees on Monday, marks the second retreat from a dedicated engineering presence on the continent after Microsoft shut its Lagos ADC in 2024. Coming just months after a USD 1 B data centre project with Abu Dhabi’s G42 stalled over payment guarantees, the closure signals a broader recalibration of how US tech giants engage with Africa.

The pattern extends beyond Microsoft. X, formerly Twitter, briefly opened an office in Accra, Ghana, in November 2022, then laid off nearly all of its roughly 20 employees just four days later. Former staff said they were “ghosted” without severance pay for more than seven months, and the company reached a settlement only after about a year of negotiations. Kenya has since given X three months to open a physical office in Nairobi, a demand that remains unmet.

Oracle has taken a different path. The company has not closed its Nairobi office but has cut roughly 21,000 jobs globally, about 13% of its workforce, as it redirects capital toward AI and cloud infrastructure. Oracle’s Nairobi operation, which serves as a hub for East African cloud and AI sales, has not been immune.

The company has not disclosed how many Kenyan staff were affected, but termination emails sent in September 2026 gave employees same-day notice, with severance capped at 26 weeks of base salary. Oracle has simultaneously been advertising roles in Kenya for data centre technicians and AI infrastructure sales, a signal that the cuts are a reallocation rather than a full retreat.

Ride-hailing giant Uber has also pulled back sharply from Africa. The ride-hailing giant shut down operations in Nigeria and Uganda in September, capping a year in which it exited four African markets in roughly twelve months, having earlier withdrawn from Tanzania in January 2026 and Côte d’Ivoire in September 2025. Meanwhile, Meta’s termination of a content moderation contract triggered 1,108 job cuts at Sama’s Nairobi hub in April.

The combined effect is a continent increasingly treated as a market for consumption rather than a site for production. The depth of Western involvement raises questions about whose priorities shape Africa’s digital future.

***

Microsoft’s cash spending on property and equipment, mostly data centres, rose from USD 23.9 B in FY2022 to USD 115.9 B in FY2026. Its workforce, meanwhile, fell by 5,000 to 223,000. Capital is flowing into compute infrastructure, not engineering headcount. The Nairobi ADC, whose teams built global products rather than Africa-specific ones, was exposed. Its work could be done from Redmond or Hyderabad. Median entry-level pay for a Microsoft engineer in Kenya stood at roughly USD 52 K a year, against USD 30 K in Bengaluru.

Kenya’s ICT Cabinet Secretary William Kabogo met a Microsoft delegation on Monday and said he “stressed the importance of retaining local talent, protecting jobs at Microsoft’s Nairobi engineering centre and sustaining investor confidence.” The government and Microsoft agreed to develop a joint action plan covering AI adoption, digital government services and cybersecurity.

For Kenya, the closure undercuts a decade-long effort to position itself as a regional technology hub. It follows the stalled Olkaria data centre, which was to be anchored by a geothermal-powered facility and mentored by ADC engineers. Talks broke down in May over Kenya’s reluctance to commit to fixed annual capacity payments.

Africa accounts for 18% of the world’s population but holds less than 1% of global data centre capacity. The continent’s four largest tech economies have each drafted AI strategies acknowledging dependence on US infrastructure as a security concern.

The Nairobi ADC was launched in May 2019 with a pledge of 500 engineers by 2023. By December 2022 it reported more than 500 engineers in Nairobi. Employees were asked to meet with managers by Friday to discuss exit options, including severance terms. Microsoft has not disclosed the timeline for the wind-down or whether Microsoft Research Africa and the Microsoft Garage, both housed at the ADC’s Dunhill Towers office, are included.
OPay’s Lending Business Has Quietly Overtaken Its Payments Empire As IPO Nears

By Henry Nzekwe  |  October 13, 2026

OPay has established its place as Nigeria’s ubiquitous payments app for a good few years now. Its green logo is plastered on the walls of roadside kiosks and the phone screens of millions, with the simple pitch of moving money faster than a bank. But the company’s newly filed IPO prospectus reveals a more consequential transformation. Lending, not payments, is now the engine driving its revenue.

In 2024, transaction-based services accounted for 39% of revenue while lending contributed 35%. By the first half of 2026, that hierarchy had flipped. Loan financing alone generated USD 236.1 M, or 50.6% of total revenue, according to the F-1 filing. Payments revenue fell to 28%. The company originated USD 927.6 M in new loans in Nigeria during the first six months of 2026, roughly three times the amount from a year earlier.

The scale of OPay’s lending machine is such that it now has 6.7 million unique quarterly borrowers, more than seven times the number it had in early 2024. Its non-performing loan ratio stood at 4.3% as of June 30, 2026, down from 4.8% a year earlier.

That improvement is down to the company quietly shifting its credit mix away from riskier consumer loans toward merchant lending. In the first half of 2026, the fintech unicorn disbursed USD 99.0 M in merchant loans across 20,000 transactions, generating USD 8.8 M in revenue. The company said it “tightened risk appetite in consumer loans” and shifted toward merchant loans, which carry a lower risk profile, according to the filing.

Consumer lending in Nigeria is politically sensitive and operationally fragile. Borrowers are often informally employed, repayment discipline is uneven, and regulators are watching. Merchant lending is different. OPay can observe a business’s daily transaction flows through its POS terminals and wallet accounts, giving it real-time visibility into cash flow and a natural collection mechanism.

OPay is also quietly rolling out a buy-now-pay-later product. Its BNPL offering allows active users to access short-term credit for everyday purchases with a two-week billing cycle and a one-week repayment window. For now, the product is small. In the first half of 2026, BNPL transaction volume was just USD 5.0 M across 13.4 million transactions. But the company is clearly testing whether the same infrastructure that powers its lending business can support a consumer credit product that feels more like a payment than a loan.

The timing of this lending pivot is not coincidental. OPay filed for a New York Stock Exchange listing under the ticker OPAY, seeking a valuation that reports suggest could reach USD 4 B. Standard Bank Group’s subsidiary has agreed to invest up to USD 200 M through a concurrent private placement, a signal that institutional capital sees value in OPay’s lending economics.

But the filing also exposes the tension at the heart of the model. OPay’s provision for expected credit losses surged to USD 118.4 M in the first half of 2026 from USD 38.1 M a year earlier. The company is lending more, and it is setting aside more to cover the risk of default. Whether merchant lending genuinely lowers that risk or simply delays it remains the central question for investors. One of its main rivals did run into problems with a startup it had lent a sizeable sum to, for instance.

OPay is betting that the same data advantage that made it a payments giant can make it a lending giant too. The prospectus suggests that bet is already paying off. The risk is that in emerging markets, credit cycles can turn faster than payment networks can adapt.

The Unlikely Fintech Breakthrough Of Africa’s Biggest Clothing Retailer Rocked By Dispute

By Staff Reporter  |  October 12, 2026

The unlikely thriving fintech arm of Africa’s biggest clothing retailer has investors clashing in a dispute over governance that threatens to overshadow a strategic pivot into financial services.

Pepkor Holdings, the owner of the Pep and Ackermans discount chains, has built a fintech business that is growing far faster than its core retail operations. Revenue from the fintech segment jumped 25.4% to ZAR 4.8 B (~USD 290 M) in the quarter to December, while financial services revenue surged 47.6% to ZAR 2.4 B (USD 144 M). For a company known for selling affordable clothing to millions of low-income shoppers, the numbers are striking. Credit sales now account for 18% of total group sales, up from 16% a year earlier.

That growth explains why Pepkor in July agreed to combine its Flash subsidiary, a payments platform serving 170,000 informal traders, with rival Shop2Shop, which has more than 210,000 users. The deal creates a fintech company valued at about ZAR 21 B (USD 1.3 B), with Pepkor holding a 57.1% stake. Pepkor says the combination will expand its payments, lending and merchant-commerce operations and broaden distribution for a planned digital bank it aims to launch in April 2027.

But the transaction has exposed a governance rift. Some directors voted against the deal, and a top 30 investor, Aeon Investment Management, says shareholders should have voted on a transaction where Pepkor Chief Executive Officer Pieter Erasmus also has a financial interest. Erasmus held a minority position in Shop2Shop before the deal and will own a 13.2% stake in the combined entity, valued at about ZAR 2.8 B (USD 169 M) based on the transaction’s implied valuation.

The transaction does not require shareholder approval under Johannesburg Stock Exchange rules because it falls below the threshold for a related-party transaction. Erasmus recused himself from board deliberations, according to Pepkor.

Even so, seeking shareholders’ views would have demonstrated better corporate governance, according to Asief Mohammed, chief executive officer of Aeon, which holds a 0.4% stake in Pepkor. “It would have gone down better had they done it,” Mohammed said. “Seeking shareholder approval would have been good governance”.

Pepkor says it obtained independent valuations of both businesses and a voluntary independent fair-and-reasonable opinion. The retailer declined to disclose how many directors voted in favour of the deal, citing the confidentiality of board proceedings.

The dispute comes as Pepkor’s shares have dropped 31% this year, compared with a 25% decline on the eight-member FTSE/JSE Retailers Index. The governance concerns also arrive as the company pushes deeper into financial services to find growth beyond its core discount retail operations, a strategy that has delivered tangible results but now faces heightened scrutiny over board process and shareholder rights.

The planned listing of the combined fintech business, provisionally called FintechCo, in the medium term adds another layer of complexity. Pepkor is betting that its informal market platform and merchant network can become a standalone fintech powerhouse. Whether investors will reward that bet depends partly on how the company manages the governance questions the deal has raised.

Beyond A Button: SeerBit Takes On The Real Gap In African Cross-Border Payments

By Henry Nzekwe  |  October 12, 2026

In Accra, a beauty brand built its following on TikTok and Instagram, reaching customers in the UK who liked the products enough to buy. The merchant had done the hard part, creating something people wanted and finding them online. But when a British customer reached checkout on the brand’s website, the payment experience was unfamiliar, and the sale slipped away.

That scenario, described by Omoniyi Kolade, founder and CEO of the pan-African payments company SeerBit, captures the shift now underway in African digital commerce.

In August 2026, SeerBit announced it had integrated PayPal into its checkout infrastructure, allowing merchants across its 10 African markets to accept payments from PayPal’s more than 400 million users. The integration runs alongside the local payment methods SeerBit already supports, including cards, bank transfers, and mobile money, and gives merchants a single dashboard to manage local and international transactions.

The announcement was framed as a milestone for African businesses seeking global customers. But the more revealing story lies beneath the press release, in what the partnership exposes about PayPal’s complicated history on the continent, the limits of a single integration and where the real bottlenecks in African cross-border commerce have shifted.

PayPal’s relationship with Africa is marked by two decades of exclusion. In 2004, the company restricted inbound payments to Nigeria, citing fraud and chargeback risks, a policy that locked out a generation of freelancers and online businesses. A 2014 partnership with First Bank allowed outbound payments only, and a 2021 Flutterwave link served businesses while ignoring individual users. Those restrictions remained in place for 22 years.

During that absence, Nigerian fintechs including Paga, Flutterwave and Paystack built the infrastructure PayPal had declined to provide, capturing a domestic digital payments market that reached NGN 1.07 Q (USD 702.6 B) in 2024.

***

Kolade is careful not to frame the SeerBit integration as a correction of that history. He describes a different set of changes that made the partnership possible now. African businesses became more digitally discoverable, consumers grew more comfortable buying across borders, and local payment infrastructure matured enough for global networks to connect to something reliable.

“The shift isn’t simply that African merchants suddenly want PayPal,” Kolade told WT. “It’s that the commercial relationship between an African business and a customer somewhere else in the world is becoming much more normal.”

What that relationship requires, however, is not simply a payment button, the founder emphasised. When SeerBit integrated PayPal, the company had to build additional merchant verification layers, because PayPal was extending its network to businesses it did not know directly.

It also created dedicated support and escalation processes, cutting resolution times for merchant issues from as long as 90 days to 24 hours. And it had to account for the fact that Africa is not a single payments market. Regulatory environments, banking infrastructure and settlement realities differ across every country SeerBit operates in. The complexity is not the integration itself, Kolade said, but everything around it.

Even after those layers are addressed, the merchant’s work is not finished when a payment notification arrives. Kolade argues that accepting payment is becoming less of a bottleneck, and that the harder problem now is what happens after the customer has paid.

A cross-border transaction must still be settled, often across multiple currencies and institutions. The merchant has to understand what they have actually earned after fees and foreign exchange costs, reconcile it against orders, and then access those funds where the business needs them. “For me, the next frontier is less about, can I accept this payment, and more about, can I make the money useful,” Kolade said.

That post-payment journey is where fragmentation becomes expensive. If a business sells into several markets and collects through different currencies, methods and providers, the money can pass through several institutions before it becomes usable. That ties up working capital, creates reconciliation work and makes it harder to understand true margins. It is a problem that a checkout integration does not solve, he reiterated.

***

There is also a quieter dynamic at play. Kolade points out that the merchant does not have to be an exporter for cross-border payments to matter.

“Someone in Canada might want to order food for their parents in Nigeria. Someone in the diaspora might pay for groceries or a pharmacy purchase for a family member back home. An international visitor in Ghana or Kenya might want to use the payment method they already know,” he volunteered as examples.

In these cases, the merchant remains local while the customer is international. And the founder asserts that the boundary between a local business and a global customer is becoming less important, and that changes what merchants expect from their payment infrastructure.

PayPal’s broader strategy, PayPal World, is designed to connect global payment networks with local wallets and infrastructure rather than building the entire stack itself. Kolade sees this as a recognition that the foundational work has already been done by African companies. “This isn’t one company coming in to solve African payments,” he said. “A lot of that foundational work has already been done by African companies.”

Still, the integration raises questions that the announcement does not answer. Cross-border payments in Africa remain expensive, with the World Bank estimating that sending USD 200.00 to Sub-Saharan Africa costs more than 8% on average, compared with a global average of around 6%. Currency volatility and central bank restrictions on hard currency can delay or complicate settlements. Merchants will need to understand how PayPal transactions are priced, how quickly funds settle and how disputes are handled.

For PayPal, the African market is a growth opportunity at a time when its core markets are maturing. For SeerBit, the partnership strengthens its position as a checkout aggregator that handles both local and global payment methods. For African merchants, the integration removes one obstacle at the point of sale. Whether it changes the economics of selling across borders depends on what happens after the customer clicks pay.

Moove Quits Nigeria, Its Birthplace, As Global Ambitions Trump Difficult Home Market

By Staff Reporter  |  October 8, 2026

Moove, the mobility fintech founded in Lagos in 2020, announced on Thursday it will conclude operations in Nigeria, the market that incubated its business model and launched its global trajectory. The company will transfer vehicles worth approximately NGN 35 B (USD 22 M) to eligible Nigerian customers free of charge from October 1, 2026.

The exit comes just over a month after Uber Technologies ended its operations in Nigeria on September 2, a departure that rendered Moove’s core model in the country untenable. Moove built its Nigerian business by financing vehicles for Uber drivers, with repayments tied to daily earnings. When Uber left, that data pipeline collapsed, leaving drivers uncertain and Moove’s local unit without a platform partner to anchor loan recovery.

Moove, now headquartered in Dubai, reached a USD 2.1 B valuation in August after raising USD 250 M in a Series C round led by Abu Dhabi sovereign wealth fund Mubadala. Its annual recurring revenue climbed from roughly USD 275 M in 2024 to about USD 400 M in 2025, before hitting USD 420 M following acquisitions including Brazil’s Kovi and Tokyo Taxi in Japan. The company operates about 42,000 vehicles across 29 cities in 13 countries and employs roughly 3,300 people.

Yet the Nigerian market that produced this global platform became a drag. A currency mismatch defined the problem. Moove raised dollar-denominated debt to buy vehicles while drivers earned naira, a disparity that widened sharply after Nigeria’s 2023 fuel subsidy removal drove up pump prices and compressed driver margins. The company had already weathered a repayment crisis, repossessing vehicles from drivers who could not earn enough to meet obligations.

“While Nigeria remains deeply important to our story, the operating environment has become increasingly challenging,” Moove said in a statement announcing the exit, framing the vehicle transfer as a “thank you” to customers.

The company’s pivot toward autonomous mobility has reshaped its strategic centre of gravity. Through a partnership with Alphabet’s Waymo, Moove manages autonomous vehicle fleets in Phoenix and Miami, with London planned next. It is the largest global fleet partner for Uber and is positioning itself as a neutral infrastructure layer for robotaxi operations, a role that has attracted investment from Toyota’s growth fund Woven Capital.

Co-founder Ladi Delano, now based in Dubai, has spoken of building a business that solves problems his parents’ generation faced in Nigeria, but the company’s current growth is driven by markets far from Lagos.

Moove did not disclose a timeline for completing the wind-down or the number of employees affected. The company said eligible customers would take full ownership of their vehicles with no further payment required for the vehicles themselves from October 1. Remaining obligations, if any, were not specified.

The transfer of NGN 35 B in assets to drivers is an unusual exit gesture, one that may cushion the immediate blow for Moove’s Nigerian customers. But it does not change the broader signal that a company built to democratise vehicle ownership in Africa has concluded that ownership of its own future requires leaving Africa’s largest market behind.

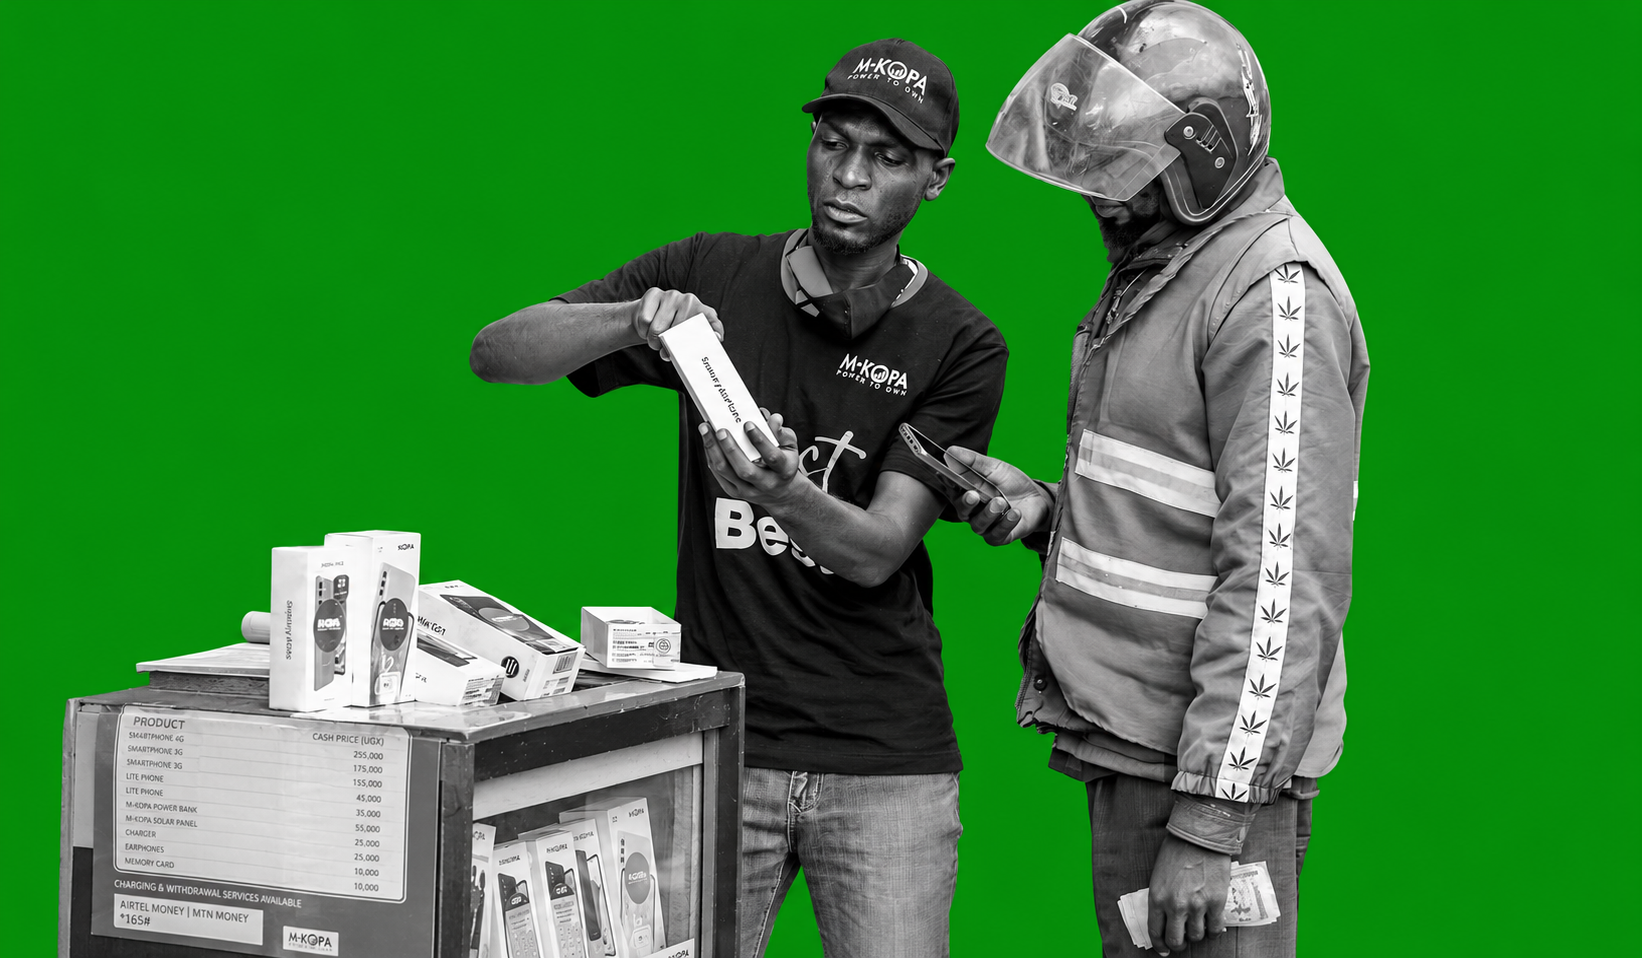
M-KOPA Built Its Name On Solar—Now Smartphones & EVs Drive A USD 600 M Boom

By Henry Nzekwe  |  October 8, 2026

Africa-focused fintech M-KOPA reported a 45% surge in revenue to USD 600 M for its 2025 financial year, a milestone that underscores how the Kenya-based company’s decisive shift from solar financing to smartphone and electric vehicle asset financing has reshaped its business and its balance sheet.

The company, which marked its 15th anniversary this month, said it added three million customers in the past year, bringing its total to 10 million across Kenya, Nigeria, Ghana, Uganda and South Africa.

The growth was driven less by its original solar home systems and more by credit-financed smartphones, a category M-KOPA entered only in 2020. Since that pivot, revenue has compounded at an annual rate of 50%, transforming what was once an impact-driven energy company into one of Africa’s largest consumer-financing platforms.

The shift reflects a hard economic reality across its markets. The vast majority of everyday earners lack formal salaries or credit histories, yet demand for smartphones and income-generating electric vehicles has outstripped the addressable market for financed solar panels.

“We maintained profitability while reinvesting as much as possible in our products, technology and distribution to scale our reach across Africa’s massive, underserved market of everyday earners,” Chief Financial Officer Faraimose Kutadzaushe said in a statement.

That reinvestment is now visible in two areas. First, the company says its Nairobi assembly plant is the largest smartphone factory in Africa by volume, producing over two million devices since its opening in 2023 and employing more than 400 workers.

On the other hand, the company has financed more than 10,000 electric motorcycles and three-wheelers in Kenya, with rider data showing average daily savings of KES 530.00 (USD 4.10) from lower energy and maintenance costs. M-KOPA is now expanding that pay-as-you-go model to electric tuk-tuks, targeting a broader segment of Kenya’s commercial transport sector.

M-KOPA says it onboards approximately 10,000 new customers per day and processes micropayments at a rate of 23 times per second, showing operational heft underpinning its expansion. It employs over 2,500 full-time staff and supports nearly 50,000 sales agents, making it one of the largest private distribution networks in African consumer finance.

Yet the USD 600 M revenue figure masks a strategic vulnerability that management has moved to address. M-KOPA’s entire financing model depends on its ability to remotely lock financed smartphones when customers fall behind on repayments.

In March 2026, the company acquired Finnish software firm KilpiTek for approximately USD 8 M, bringing that device-locking capability in-house rather than relying on a third-party provider. The transaction included about USD 2.67 M in cash and the remainder in M-KOPA shares and deferred consideration, according to its financial disclosures.

“The transaction is intended to strengthen the group’s control over a critical component of its technology stack and support ongoing product and sourcing strategy,” the company said in its disclosure.

The broader question for investors is whether M-KOPA’s smartphone-led model can sustain its growth rate as it expands across five markets with varying regulatory and currency environments. The company has been recognised on the Financial Times Fastest Growing Companies in Africa list for five consecutive years, but its customer base remains heavily concentrated in East Africa, and its newest markets in Nigeria and Ghana present different competitive and macroeconomic challenges.

For now, the numbers point to a company that has found a more durable product axis than the one it was founded on. While solar gave M-KOPA its first decade and its patient-capital base, smartphones and electric mobility appear to be giving it its next one.

Africa’s Traditional Savings Groups Quietly Emerge As New Payments Battleground

By Henry Nzekwe  |  October 7, 2026

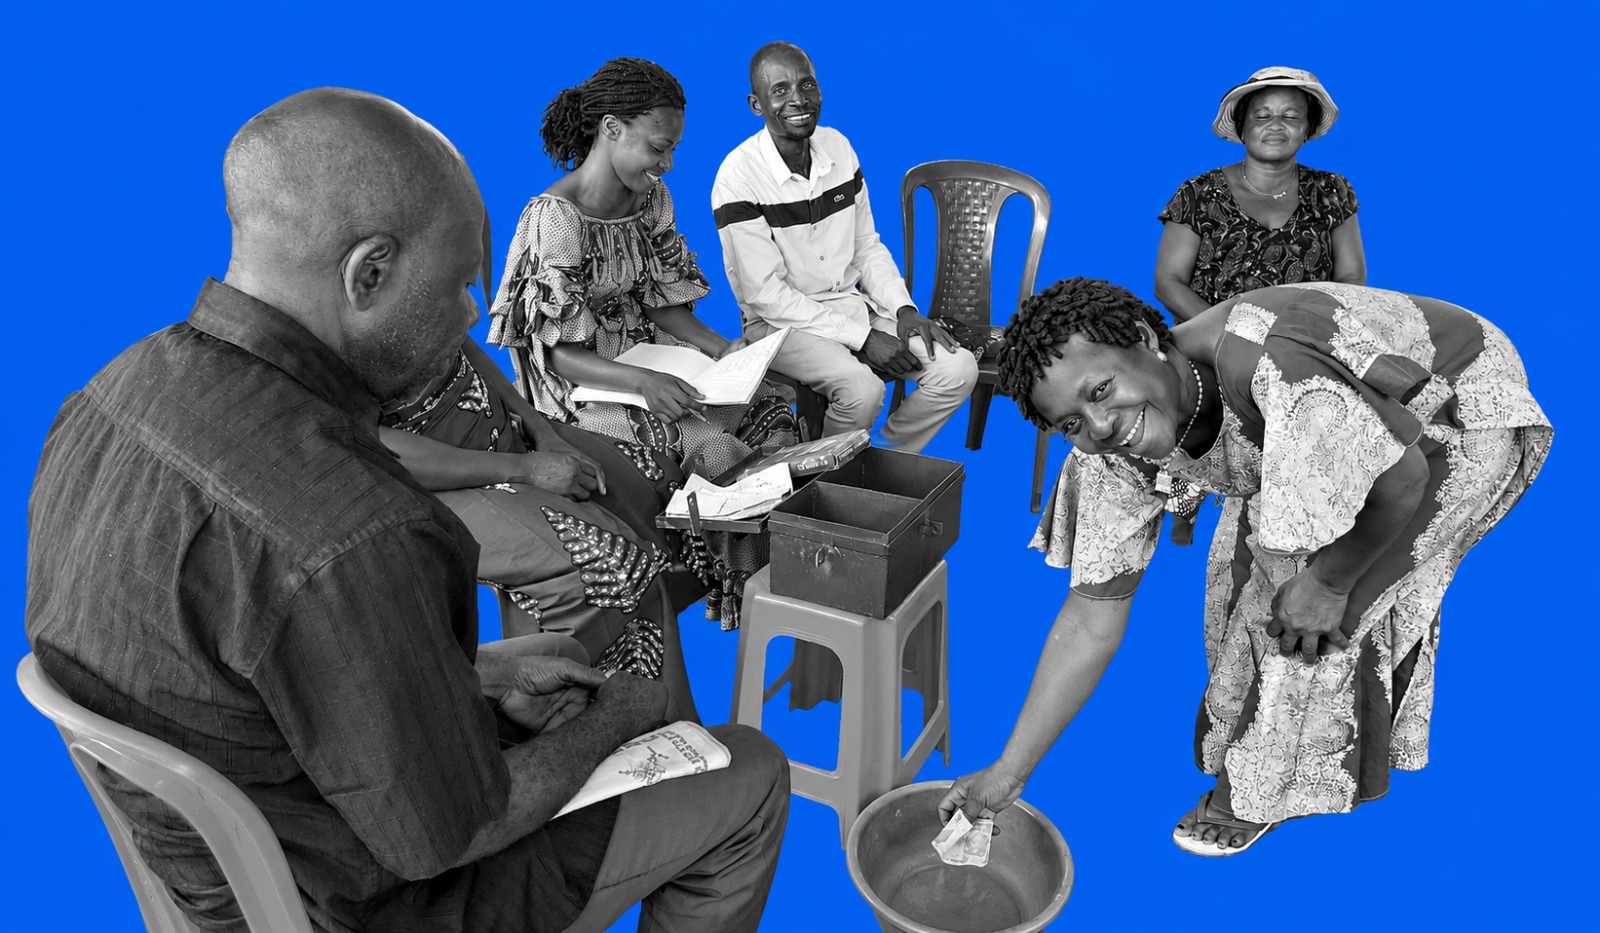
Across Africa, an old financial habit is becoming a new frontier for banks, fintechs, and mobile money providers. Community savings groups, long dismissed as the informal domain of cash-stuffed envelopes and handwritten ledgers, are being pulled into the digital economy at speed. The prize is not just the deposits they hold, but the transaction flows they generate.

The numbers explain the sudden interest. Kenya’s regulated savings and credit cooperative organisations held KES 1.21 T (USD 9.4 B) in assets in 2025, up 12.5% from a year earlier, according to the Sacco Societies Regulatory Authority. South Africa’s 800,000 stokvels manage about ZAR 50 B (USD 2.7 B) annually and count roughly 11 million members. Egypt’s MoneyFellows, which digitises the traditional gameya savings circle, says it has onboarded more than 8 million users.

These pools of money once sat largely outside the banking system. Now they are becoming the connective tissue for a payments market that banks cannot afford to ignore.

The competitive dynamic is most visible in Kenya. Commercial banks are racing to handle cheque clearing, ATM access, and real-time transfers for deposit-taking SACCOs, which are barred from direct access to the national payment infrastructure. Co-operative Bank of Kenya served 110 SACCOs with ATM connectivity in 2025, but Family Bank, KCB, and Equity Bank are expanding their footprints. Safaricom and payment provider Interswitch have entered the Pesalink instant transfer market for SACCOs, a sign that the settlement landscape is widening beyond traditional lenders.

SASRA reported that the number of SACCOs offering digital financial products rose to 267 in 2025 from 236 a year earlier. But the same report warned of cyber risks, and 107 regulated SACCOs still had no USSD connectivity at all. The digitisation race is real, but it is uneven.

***

In South Africa, the battleground is account opening. First National Bank completed the full digitisation of its stokvel accounts in early 2026, removing a long-standing requirement for three signatories to visit a branch together.

“We’ve completed the digital stokvel account journey and now everything, from account opening through to transactions and payouts, can now be done digitally,” said Himal Parbhoo, FNB’s CEO of cash investments. Standard Bank, Nedbank, and Absa offer stokvel accounts, but none have matched FNB’s end-to-end remote onboarding.

The broader significance lies in what happens to the money once it is inside a bank. Stokvel balances are stable and predictable, building through the year before seasonal payouts. For lenders, they are a low-cost source of funding. For members, formal accounts offer security. The trade-off is that community savings are being slowly absorbed into the same institutional structures they were designed to bypass.

Egypt offers a different model. MoneyFellows, which raised USD 13 M in 2025, has built a profitable business by digitising the gameya without requiring users to join pre-formed social circles.

“We’ve managed to crack this model and achieve profitability,” said founder and CEO Ahmed Wadi. “What makes this even more transformative is that we’ve facilitated billions in loans without using working capital.” The platform’s ability to generate credit scores from savings behaviour has turned a cultural tradition into a data asset.

Nigeria is also in the picture as new vigour seeps in after some previous stop-start endeavours. Rank, a fintech formerly known as Moni, launched Money Circles in 2026, a digital version of ajo and esusu rotating savings schemes. The company says it has paid out more than USD 100 M to users in the past year.

“For generations, Africans have relied on communal financial structures to build wealth,” said CEO Femi Iromini. “We are bringing these trusted traditions into the modern age by layering cutting-edge technology.”

The race is not without friction. Digitising savings groups requires trust, and trust is not easily coded. Many groups still prefer cash because it is visible. Others worry that formal accounts will expose them to fees or taxes. Regulators, meanwhile, are caught between encouraging financial inclusion and managing new risks.

What is clear is that the infrastructure behind community savings is becoming a market in its own right. Banks want the deposit base, fintechs want the transaction data, and mobile money providers want the payment rails. The savings groups themselves want convenience and security. Whether those interests align or collide will shape how hundreds of millions of Africans save, borrow, and build wealth in the years ahead.

Feature Image Credits: WVI

Cash-Back At Supermarket Tills Surge As South Africans Ditch ATMs Over Fees

By Staff Reporter  |  October 7, 2026

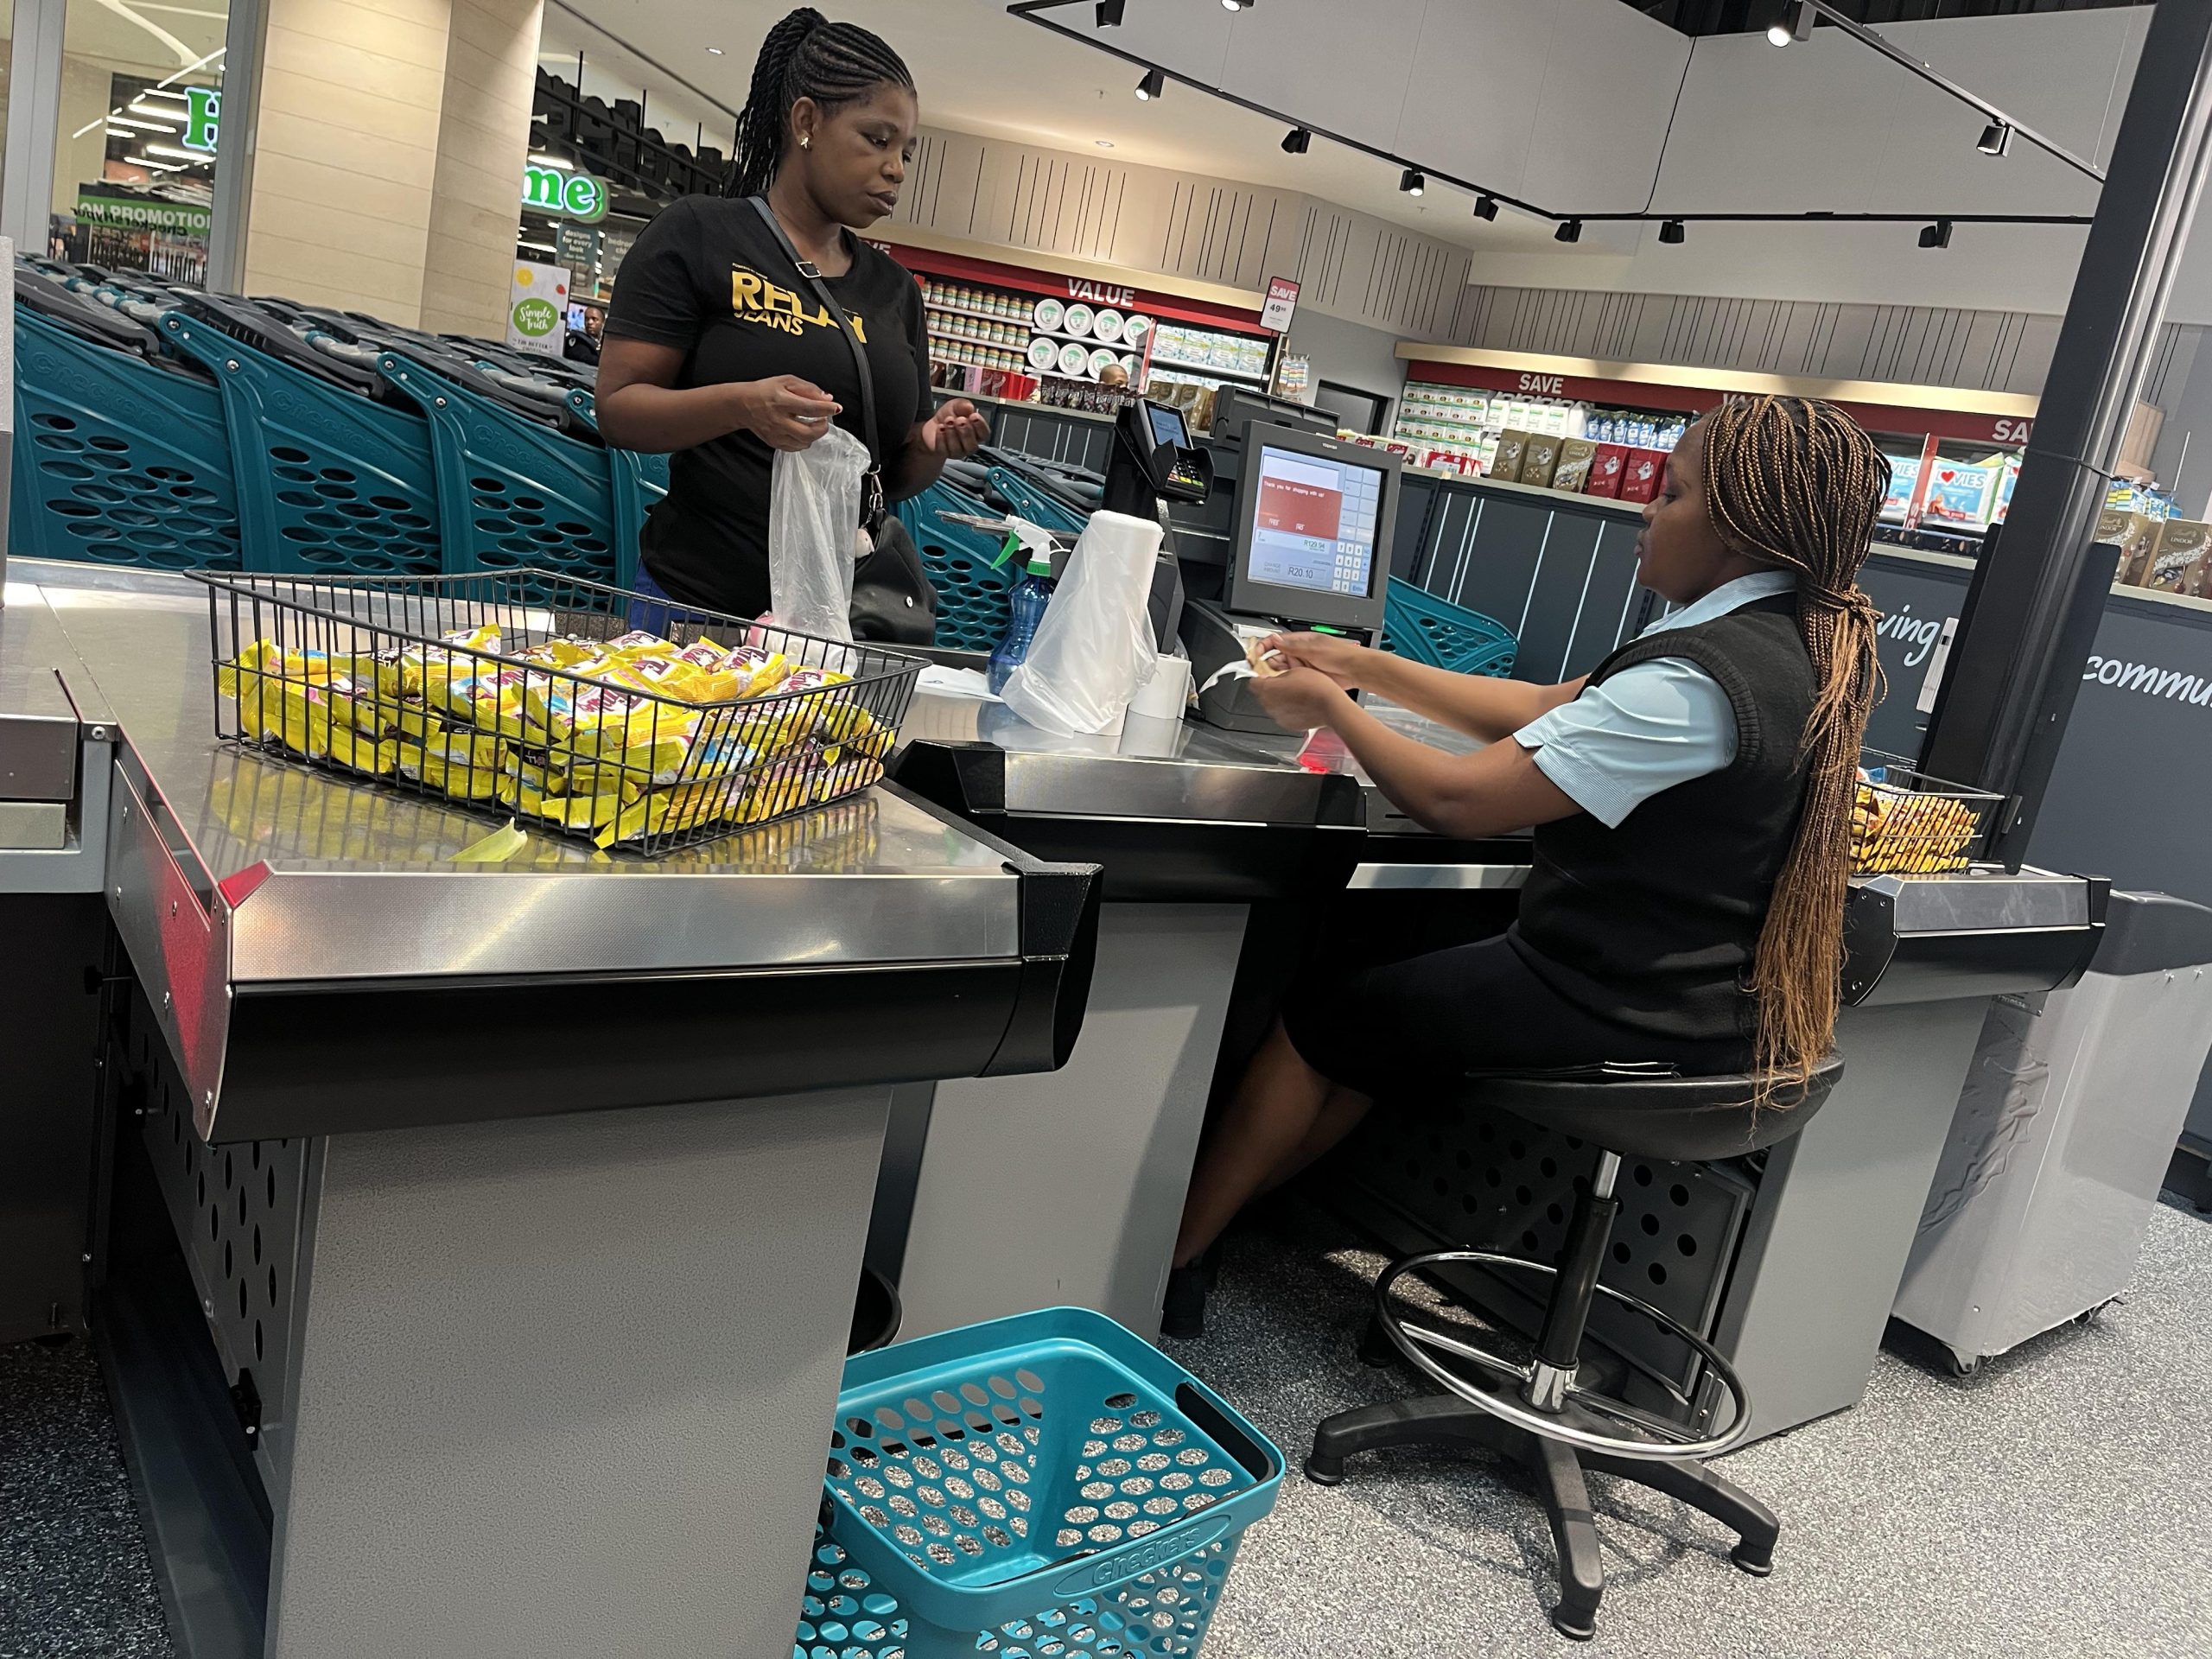
South Africans are abandoning automated teller machines (ATMs) for an unlikely alternative. They are withdrawing cash at supermarket checkouts, and the shift is forcing a rethink of how the country’s cash system works.

Data from the South African Reserve Bank’s Cost of Cash Industry Report 2026 shows retail tills now process about ZAR 326 B (USD 19.5 B) in cash-back withdrawals annually across 663 million transactions, with an average withdrawal of ZAR 492.00 (USD 25.25). The SARB describes point-of-sale cash-back as the most cost-efficient channel in the country, costing about 12 cents per ZAR 100.00 (USD 6.01) handled compared with 68 cents at ATMs and ZAR 1.53 at bank branches.

South Africans pay about ZAR 17.7 B (USD 1.06 B) a year in cash withdrawal fees, with ATM withdrawals typically costing between ZAR 10.00 (USD 0.60) and ZAR 20.00 (USD 1.20), while tillpoint withdrawals range from ZAR 1.00 (USD 0.060) to ZAR 3.00 (USD 0.18). Consumers also spend an estimated ZAR 12.5 B (USD 751.4 M) on taxi fares and fuel to travel to ATMs and bank branches, and lose another ZAR 27.8 B (USD 1.6 B) in productivity from queuing and travel. For many households, the supermarket till is simply closer and cheaper.

The country operates about 30,634 ATMs, but three of the five largest banks have reduced their ATM footprints since 2023. Nedbank’s network has shrunk by 4.4% and Absa’s by 2.3%, while Capitec has expanded aggressively. The average ATM costs about ZAR 307.59 K (USD 18.4 K) a year to operate, a burden that gets passed to consumers.

Banks are actively steering customers toward retail tills. Standard Bank says cash-back at point-of-sale has surged more than 100% since 2019, and 11% of all its cash withdrawals now happen at retail checkouts.

“Emerging channels like cashback at point-of-sale and cash deposits at retailers are gaining traction as alternatives to ATMs and branches,” said Kabelo Makeke, Standard Bank’s head of personal and private banking in South Africa.

Retail tills solve a problem ATMs cannot. ATMs dispense high-value ZAR 100.00 and ZAR 200.00 notes and cannot issue coins, which creates friction for consumers who need smaller denominations for taxi fares and informal traders. SARB field research found shoppers deliberately buy low-cost items with large notes to obtain change in smaller denominations.

The shift has broader implications. Retailers can recycle cash from sales directly to customers, reducing their own banking and cash-in-transit costs. But it also raises questions about whether the retail sector is becoming an unofficial banking infrastructure without the regulatory framework that comes with it.

The SARB’s Cash Smart Strategy, outlined in a position paper earlier this year, proposes white-label ATMs operated by a national cash utility rather than individual banks, with the aim of lowering fees and expanding access to underserved areas. Deputy Governor Rashad Cassim said the central bank is aware that many businesses operate under current regulations and that engagement on the proposals is ongoing.

Nevertheless, the supermarket till remains the most practical option for millions of South Africans.

Viral Simulator Games On Browser Tabs Make A Splash In Nigeria’s Scale-Starved Gaming Scene

By Henry Nzekwe  |  October 6, 2026

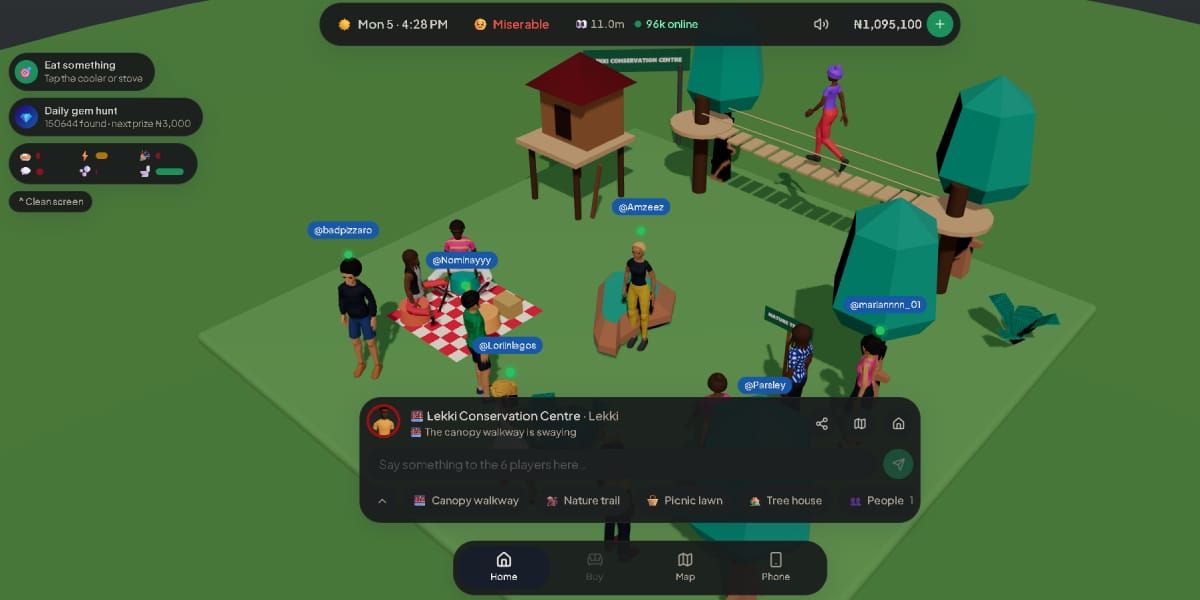
A browser game that lets Nigerians simulate life in Lagos, complete with traffic, power cuts, and the struggle to make rent, has drawn more than 2 million players in under a week, marking a breakout moment for a local gaming industry that has long struggled to turn cultural familiarity into scale.

Lagos Life, built by UK-based Nigerian developer Shalom Mathew, went live on October 1, Nigeria’s Independence Day. Within three days, it had crossed one million players.

By October 5, its public dashboard showed more than 2 million total players, over 145,000 concurrent users and 16.5 million all-time visits, having added two other major cities, Abuja and Port Harcourt, to the virtual world. The game generated USD 46.9 K in revenue in its first four days, according to figures Mathew shared on X, where she posts as @Shalom_HeyEliy.

The game is quite simple. Players create a character and are assigned a starting financial position: either “Nepo,” a reference to wealth and connections, or “Lapo,” a nod to the microfinance loans and financial hustle that define life for many young Nigerians. From there, they work jobs, manage energy, buy food, pay rent, and socialise in a shared online Lagos that includes landmarks like Amala Shitta and Quilox. The game runs in real time, so its virtual day follows the actual day.

Mathew has said the idea grew from her childhood spent playing The Sims 3. “I grew up playing The Sims 3 and always wondered what it would be like if the Sims lived in a world inspired by ours,” she wrote on X.

She credits another Nigerian browser game, Lagos Run, with providing motivation. Lagos Run, built by Berlin-based engineer Opeyemi Adeniran, puts players behind the wheel of a danfo, the yellow minibuses synonymous with Lagos transport. Released in late September, it drew more than 20,000 players within days.

***

What separates Lagos Life from the wave of Nigerian games that have come before it is not the cultural references is the distribution model. The game requires no download, no app store listing and no console. A phone or computer with a browser is enough. That matters in a market where the cost of data, device storage and gaming hardware has historically kept participation low.

About 87% of African gamers play on smartphones, and mobile titles account for nearly 90% of the continent’s gaming revenue, but credit card penetration in Nigeria sits at around 3.5%, making paid downloads and in-app purchases difficult. A free browser game sidesteps all of that as the link is effectively the product.

The speed of adoption reflects how little it takes to reach Nigerian players when the barrier to entry is removed. Google Trends data shows Nigerian search interest in “Lagos life” broke out by more than 5,000% in the week after launch, peaking at about 10 p.m. on October 4.

Interest was strongest in Ekiti, Ogun, Osun and Lagos, but the game’s reach extended well beyond the southwest. Nigeria now has over 46 million active gamers, more than South Africa’s 26 million, and its gaming market is growing at roughly 12% annually, well above the global average.

***

The commercial model is equally notable. Unlike most viral Nigerian games, Lagos Life has been generating revenue from day one, renting out virtual billboards to real advertisers. The game charges NGN 5 K (USD 3.77) per week for one of 38 roadside billboards and NGN 18 K (USD 13.56) for a larger lagoon plot. It also offers artists the chance to have their music played in virtual clubs for NGN 50 K (USD 37.74).

That revenue is important as running a free game with tens of thousands of concurrent users is expensive. Moreover, Lagos Life suffered a brief outage on October 2, for which Mathew compensated every player with NGN 100 K (USD 75.48) in virtual cash, a sum that exists only inside the game.

The explosive growth has also exposed the fragility of a game built quickly and scaled overnight. An exploit allowed some players to generate vast sums of virtual money, flooding the in-game economy with hacked naira. Mathew reset the fraudulent balances, restored legitimate ones and said she was adding features such as income tax to prevent a recurrence. Players mostly joked about the intrusion of real-world financial burdens into their virtual escape.

The game’s success has already spawned imitators. A London Red Bus game appeared within days of Lagos Run, swapping the danfo for a double-decker. A Port Harcourt life simulation followed Lagos Life.

Whether Lagos Life retains its audience beyond the initial curiosity is uncertain. A visit of a few minutes counts toward the total, and viral browser games often lose players once the novelty fades. But the early numbers suggest that the barrier for Nigerian games was access, not demand.

It does seem that when a game is a link, not a download, and when its world looks like the one outside the window, the audience is already there.

West Africa’s Mobile Money Giants Lose Cash Cow To Strict Fee Cap They Can’t Fight

By Staff Reporter  |  October 5, 2026

Banks, fintechs and mobile money operators across West Africa will be forced to route all interoperable electronic money transfers through a single central bank platform from November 2, and they will be allowed to charge no more than 0.8% for transfers above a daily threshold of CFA francs 8 K (~USD 13.70).

The rules, published by the Central Bank of West African States (BCEAO) on October 2, mark the most aggressive intervention yet in a mobile money market that processed USD 498 B in transactions across West Africa in 2025, according to GSMA data. They represent a direct challenge to the business models of dominant operators such as Orange Money and Wave, which built their franchises on closed networks and transfer fees of around 1% or more.

The BCEAO, which oversees monetary policy for the eight-nation West African Economic and Monetary Union (WAEMU), had initially launched the platform, known as PI-SPI, on September 30, 2025, with free person-to-person transfers as its flagship selling point. One year later, that promise has been revised. Transfers of CFA francs 8 K or less, cumulated per day per user per participant, remain free. Above that, providers may charge up to 0.8% before tax. Receiving money is free without limit.

The central bank says the threshold keeps about 75% of electronic money transactions in the union free of charge. The cumulative nature of the cap is significant. Users cannot split a CFA franc 20 K transfer into three smaller ones to avoid fees. The daily total is tracked across all operations with the same institution.

“The logic of the reform is to protect small users while allowing providers to sustain the infrastructure,” said Tossouve Renaude Martinie, a payments specialist working across banking and mobile money in the region. “PI-SPI is not just a means of moving money. It is a public rail that the private sector must now build on.”

The pricing shift is accompanied by a regulatory mandate. From November 2, all interoperable electronic money transactions within WAEMU must transit through PI-SPI. Cross-border transfers within the union will follow the same pricing rules from June 1, 2027. The platform currently connects 175 institutions and reaches more than 38 million people, according to the BCEAO.

Wave, one of the region’s largest mobile money operators with more than 23 million monthly active users, joined PI-SPI on the September 30 regulatory deadline after a year of absence. The company built its success on a flat 1% transfer fee, and its delayed participation underscored the tension between its low-cost model and a free interoperability rail that could cannibalise its revenue.

Industry analysts expect operators to shift their monetisation strategies toward merchant payments, QR code services and business payment APIs. Ecobank, Standard Chartered, Orange, MTN and TouchPoint have already positioned themselves on the 24 certified business APIs that PI-SPI now offers.

“The real challenge is not connection. It is turning this infrastructure into daily usage,” said Aïssatou Ami Touré, managing director of TouchPoint Financial Services Senegal.

The rules leave several operational questions unanswered, including how providers must calculate fees on the transaction that takes a customer above the daily threshold.

The BCEAO has not specified whether the fee applies to the entire amount or only the portion exceeding CFA francs 8 K. For now, the central bank has drawn a clear line.

Foren Emerges From Leatherback’s Ghost After Crisis & Zedcrest Takeover

By Staff Reporter  |  October 5, 2026

Leatherback, the Nigerian-born, UK-headquartered cross-border payments company rocked by a string of upheavals of late, is now Foren. The name change, announced today, comes two months after Nigerian financial services group, Zedcrest, completed a full acquisition of the startup it first backed in a USD 10 M pre-seed in 2022. It marks the final erasure of a brand that spent two years fighting for its survival.

In November 2023, Nigerian authorities alleged that a shipping company, SDQ Facilitators, had used a Leatherback account to defraud victims of about USD 10 M. The EFCC declared co-founder and CEO Ibrahim Ibitade wanted, and Leatherback’s Nigerian bank accounts were blocked.

The company sued; Ibitade filed a human rights suit, and in February 2025, a Federal High Court in Lagos ordered the permanent forfeiture of over USD 800 K traced to SDQ’s dollar wallet on the Leatherback platform. Ibitade was cleared of wrongdoing, but the reputational damage was done.

He stepped down in October 2024, citing a desire to start a family and “multiple misalignments of goals and visions” with lead investor Zedcrest. By February 2025, he had launched Prune Payments, a direct competitor to the company he founded. Interim CEO Toni Campbell exited in June 2025. Former Cellulant executive Ochebhoya Ekpete took over in August 2025 and immediately pivoted the company from consumer remittances to enterprise infrastructure.

The rebrand is being framed as an evolution. Ekpete says the company spent two years “rebuilding everything a customer relies on but rarely sees” and that “by the time that work was done, we were a different company, and Leatherback no longer described us”.

While Leatherback was not found guilty of anything and the founder was cleared, it appears the company has figured it’s better off moving on from its previous identity, as the association with a fraud investigation can often prove too toxic to shake.

Foren now positions itself as a unified platform for global accounts, cross-border payouts, foreign exchange, and treasury management, targeting businesses rather than individuals.

Zedcrest’s backing gives it the capital and institutional cover to pursue regulatory licences and banking partnerships that a scandal-tainted startup could never secure alone. The company plans hubs in Canada and Kenya to complement its London headquarters and new West African base in Nigeria.