Is Equity Crowdfunding Picking up For Investors and African Businesses?

By Guest Post  |  October 24, 2022

Many in South Africa are familiar with the concept of crowdfunding to kickstart an idea or raise money for a needy cause. While crowdfunding is a billion-dollar global industry, equity crowdfunding is in its infancy in Africa and is an exciting alternative investment disrupting the funding landscape. It offers investors a share in a particular business in exchange for capital for growth. 

Raising capital is difficult for entrepreneurs worldwide, but it is particularly tough for African entrepreneurs who fundraise unsuccessfully using traditional financiers such as banks, as they often don’t have the security required. Yet, there are many examples of brilliant businesses on the continent – they are not only resilient but innovate to harness the potential in various sectors.

I am particularly passionate about entrepreneurship and developing quality entrepreneurs. I am just as keen on the importance of alternative investments for more balanced investment portfolios. I was a pioneer in the Section 12J space in this country and saw the enthusiasm with which South Africans embraced this alternative investment.

After Treasury ended this option to invest in alternative assets, I saw the gap for an equity crowdfunding platform focused exclusively on African businesses. This mechanism is simple and quick to market. If the crowd likes it, they’ll fund the business, and entrepreneurs get some validation up-front for their concepts and have a chance to achieve their goals.

Global equity crowdfunding markets

The worldwide crowdfunding market was estimated to be over $17 billion in 2020, with an annual growth rate of 16% – 17% projected from 2021 – 2026. By 2028, it is forecast to reach $43 billion. 

Equity crowdfunding in the US,Europe and the Orient continues to gain traction, but the concept is quite new in Africa. Crowdfunding volumes in Africa grew 118% since 2015, with almost 90% of capital being raised through foreign-based platforms headquartered in Europe and the United States. Between 2013 and 2016, over 78% of annual African crowdfunding occurred in South Africa, Nigeria and Kenya. 

Diversifying risk while ensuring upside

The venture capital and private equity space is dominated by high-net-worth individuals and family offices. The difference with GoGetta’s equity crowdfunding model is that the minimum investment is as low as R1000, which means that it is accessible to a much broader investor base. More people can get in on the action alongside banks, angel investor networks, venture capital and private equity firms.

Benefits for entrepreneurs

Entrepreneurs have a solution to raise funds other than from traditional sources, and the platform is sector agnostic. However, crowdfunding is about more than just raising capital. The need to pass the muster of the investment committee provides two opportunities to test the business concept – first with the investment committee and, once listed, potential equity investors. 

Entrepreneurs retain their ideas and control over their businesses but are guided and mentored by strong business development professionals to carefully manage costs, timing, marketing and delivery.  Post the fundraise, entrepreneurs will be assisted with reporting to investors.

Eyes on Africa

By 2050, Africa is expected to be the continent with the largest population and consumer base. Although historically, connectivity and other issues were barriers to growth, we are seeing massive adoption as infrastructure improves and mobile and internet penetration continues to rise.

SMMEs are the key to prosperity and growth throughout Africa; they need as many opportunities for sustainable investment as possible. There are unique African problems and subscribing for equity in the businesses that solve these issues should be available to global investors. Africa is a magnificent sleeping giant, and we are ready to awaken her.

Note: This article is contributed by Jeff Miller, founder of Grovest and GoGetta. GoGetta is an equity-based crowdfunding platform that brings venture capital opportunities to investors worldwide and gives Africa’s entrepreneurs the platform to raise capital.

Cover photo by Giorgio Trovato on Unsplash
Africa’s Hottest IPO Broke Fintech Apps, But Jury Is Out On Whether It’s Worth It

By Henry Nzekwe  |  September 17, 2026

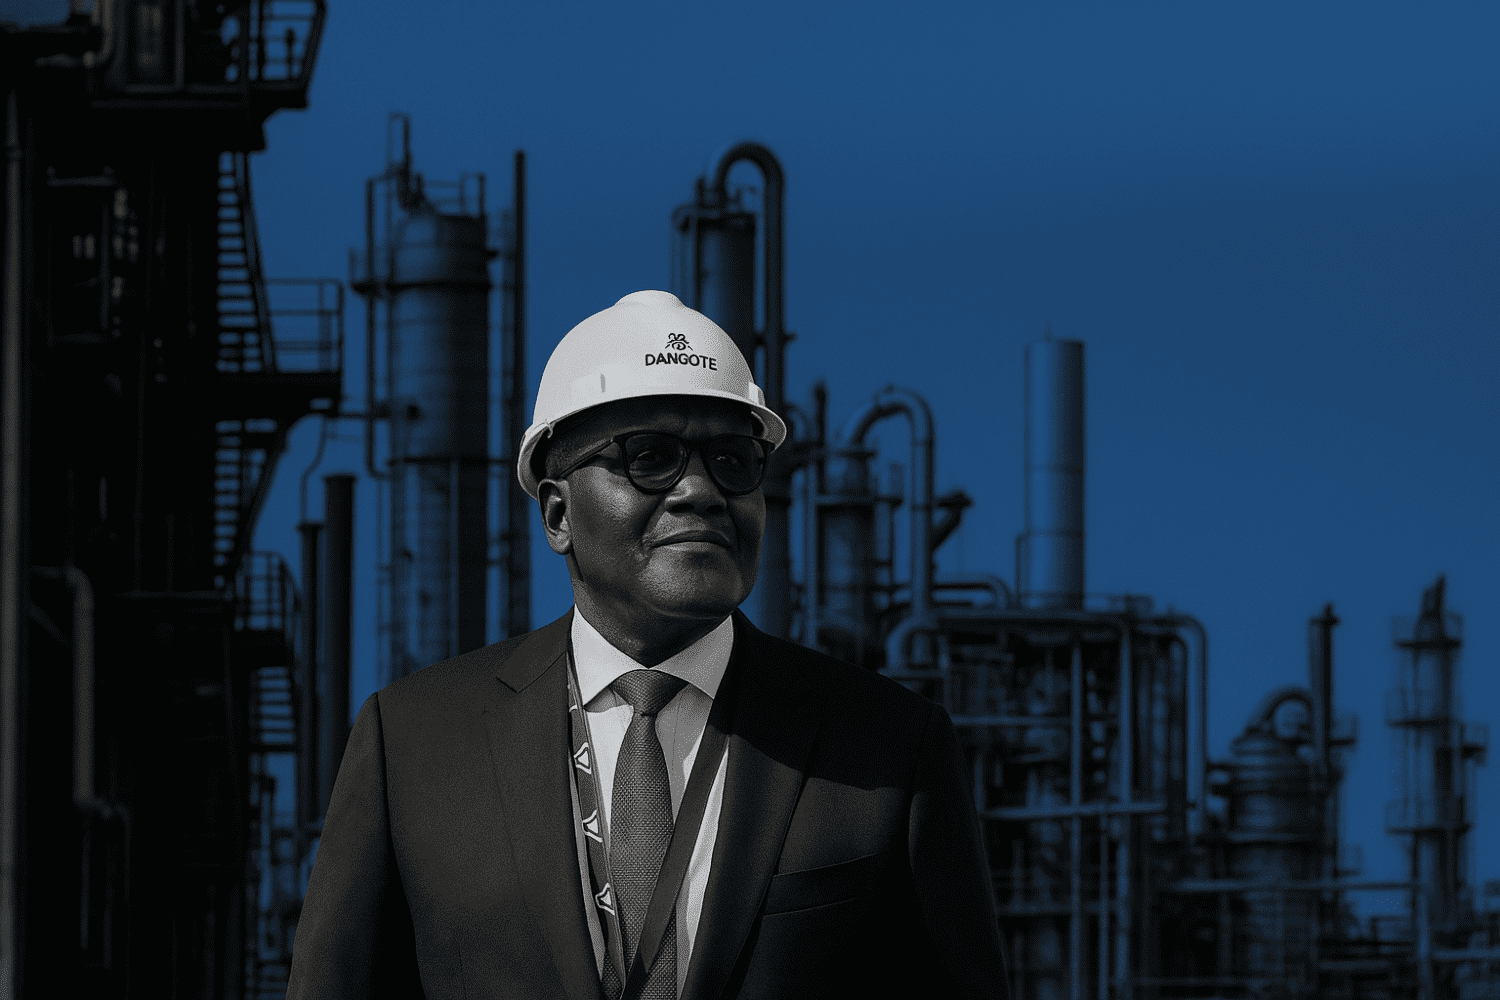
Nigeria’s leading fintechs are high on Africa’s hottest IPO and seeing a surge in users, so much so that some buckled under the weight, but the jury is out on whether the hype is worth it.

Some of the country’s major fintech players, including Bamboo, Cowrywise, Flutterwave, Moniepoint, Paga, and PiggyVest, spent weeks telling their users to buy a piece of Africa’s biggest refinery. When the doors opened on Monday, some of the apps themselves could not get through.

Bamboo, one of the country’s largest digital investment platforms, opened more than 236,000 new accounts in the week before the Dangote Petroleum Refinery’s initial public offering. Traffic on its app surged to ten times normal levels within thirty minutes of the offer going live. “To be very, very honest, our system broke,” Bamboo co-founder Yanmo Omorogbe told Reuters. Cowrywise and InvestNaija reported similar failures.

The disruption has been framed as a success problem. That framing suits the offering’s promoters, who have marketed it as a “people’s IPO” with a minimum buy of ten shares at NGN 525.00, or roughly USD 4.00. Aliko Dangote, Africa’s richest man, told local television he expects ten million Nigerians to buy shares. The Nigerian Exchange recorded NGN 1.5 T (USD 1.12 B) in subscriptions on the first day alone, about 70% of the total offer.

But the numbers in the prospectus tell a more complicated story. For some analysts, the investment case, when separated from the national pride attached to Dangote’s name, raises questions that the app crashes have pushed to the margins. The most detailed public critique comes from Feyi Fawehinmi, a notable accountant and long-time critic of Dangote’s business practices, whose analysis “Is This IPO Halal” has circulated widely among Nigerian market watchers.

***

Fawehinmi’s central argument is that the refinery’s national importance and the merits of buying its shares at NGN 525.00 are separate questions. His findings point to curious discrepancies in reported figures, such that the same six-month period yields materially different pictures of operations, capital spending and financing depending on which section of the prospectus one reads.

The prospectus, Fawehinmi points out, presents USD 1.513 B of cash generated from operations in the reporting accountant’s extract for the first half of 2026, but USD 1.273 B in the historical summary. Cash purchases of property, plant and equipment are shown as USD 162.2 M in one presentation and USD 33.4 M in another.

Furthermore, finance income moves from USD 498.5 M to USD 49.6 M. Both presentations arrive at the same USD 2.106 B profit before tax because the differences are somehow offset elsewhere, but the prospectus does not provide a numerical bridge explaining why the same six months produce materially different pictures of operations, Fawehinmi says.

There’s also the question of whether the profit can last. The refinery swung from a loss in the first half of 2025 to a USD 2.106 B pretax profit in the first half of 2026. But 98.4% of that improvement came from a USD 2.35 B rise in gross profit, driven by product volumes and prices that benefited from exceptional market conditions linked to the Iran war.

Although stable full-capacity operations only began in March 2026, the prospectus estimates a 2026 gross refining margin of about USD 24.20 per barrel but cautions that market conditions can change. Fawehinmi contends investors are being asked to price a company whose recent profitability was forged in a geopolitical crisis, not a steady-state market, tethered to a lofty promise that the refinery would double capacity by 2029, on schedule, through a USD 14.3 B expansion program.

***

Then there is the question of what this refinery means for Nigerians at the pump. On this particular point, which is probably the one Nigerians care about most, Fawehinmi’s broader work on Dangote’s business model is relevant.

The prospectus commits to import-parity pricing, meaning Dangote’s fuel is priced against what it would cost to import, not against the cost of refining it locally. The World Bank found that as of March 2026, imported petrol was about 12% cheaper than Dangote’s ex-depot price. It could thus be deduced that the refinery sold as a solution to Nigeria’s dependence on costly imported fuel is pricing its output in a way that does not necessarily deliver cheaper fuel to the Nigerians buying its shares.

This pattern is especially emphasised by critics who have tracked Dangote’s rise. Academic research on Dangote Cement describes a business built on a Backward Integration Programme that made it possible for him to invest aggressively while competitors faced higher barriers.

Critics have accused the group of predatory pricing and of benefiting from import bans, concessions, and restrictions in sectors where it operates while opting not to transmit the gains of favourable policies to the local market. A study on Dangote’s business model described the relationship between the conglomerate and the Nigerian state as one built on crony capitalism.

Then there is the research supporting the offer. Fawehinmi examined reports from Renaissance Capital, Chapel Hill Denham and CardinalStone, all of which are named in the prospectus as joint issuing houses. CardinalStone’s report discloses that it was communicated to Dangote Refinery and approved for publication by the company, and that the analyst responsible holds personal positions in the refinery’s shares.

Renaissance Capital’s report states it is not independent investment research. Fawehinmi also identifies a calculation error in Chapel Hill Denham’s comparable-company analysis that inflated its peer average from 6.4 to 9.5, reducing its valuation by roughly USD 2.21 B when corrected. CardinalStone’s own comparable-company method values the refinery at USD 27 B, below the IPO valuation, yet it more than doubled its headline target.

The critique also pointed out an overlap of directors and funds across the refinery and multiple other Dangote sister companies as potential governance risks, concluding that none of these means the refinery is a bad investment but that the investment case should be evaluated on its numbers, not on the patriotic appeal of owning a piece of Africa’s biggest industrial asset.

It thus stands to reason that just as some fintech platforms didn’t prove robust enough to handle the demand they spent weeks generating, investors might want to examine whether the prospectus they are subscribing through those apps is any more robust.

Kenya Startup Failures Worsened By Flameout Of Once-Celebrated B2B Star

By Henry Nzekwe  |  September 16, 2026

Twiga Foods raised USD 185 M to fix Kenya’s broken food supply chain. Last month, the company entered administration after nearly three years of job cuts and mounting debt, with creditors now lining up to recover what they can after an implosion that is the latest piece of a broader puzzle in Kenya’s tech scene.

The country’s startup ecosystem has something of a paradox at its core, as it has long been arguably the most stable of Africa’s four largest tech markets, with resilient infrastructure and a more predictable business environment, yet it has produced some of the continent’s most spectacular flameouts.

For one, Kenya has raised more venture capital than any other African market in recent years, yet clear successes of the scale and stature of some of the prominent startups in other top markets have not emerged, while a unicorn startup has also failed to materialise. This is unlike its peers, Nigeria, South Africa, and Egypt, which boast multiple billion-dollar companies. Kenya, despite its relative stability and investor appeal, has found this hard to come by.

Kenyan startups raised USD 984 M in 2025, outpacing Egypt, South Africa, and Nigeria, and accounting for nearly a third of all African venture funding that year. But a closer look reveals a lopsided ecosystem.

Debt made up 60% of that total, or USD 582 M. Equity funding, the kind that typically fuels hypergrowth and unicorn valuations, was less than USD 400 M. Four energy companies, d.light, Sun King, M-KOPA, and BURN Manufacturing, alone accounted for nearly 70% of the country’s venture funding. It could thus be deduced that Kenya is well-placed as a climate and asset-financing hub with a thin layer of other bets on top, not a broad-based startup powerhouse.

That concentration perhaps explains why unicorns remain elusive. Unicorns are typically born from equity-fueled scale, not debt-financed asset purchases. They emerge when consumer internet, fintech, or software companies achieve viral growth and high margins. Kenya’s funding profile tells a different story. Capital flows to solar home systems and electric motorcycles, capital-intensive businesses with long payback periods and modest valuations.

***

The Twiga case illustrates the deeper structural problem. Twiga raised USD 185.4 M from blue-chip investors including Goldman Sachs and the IFC, yet still could not find a profitable path in Kenya’s fragmented retail supply chain. The company tried to scale a capital-intensive logistics model in a market with low margins and informal competitors. When the venture capital tap tightened, the debt became unsustainable.

Twiga is not alone, however. At least seven high-profile Kenyan startups have closed, entered administration, or scaled back in the past 16 months, according to PwC.

Copia Global, a rural e-commerce platform that raised USD 123 M and served over a million households through 30,000 agents, ended up in trouble and entered administration in May 2024 after failing to secure a critical USD 20 M injection. Copia ran an asset-heavy delivery network in low-density rural markets where logistics costs outpaced revenue.

Koko Networks, a clean-cooking company backed by Microsoft’s Climate Innovation Fund and a USD 179 M World Bank guarantee, shut down in January 2026 and laid off all 700 employees after the government blocked its carbon credit sales, cutting off a revenue stream that funded its subsidised bioethanol model.

Lipa Later, a buy-now-pay-later fintech that raised over USD 16 M and reached a valuation near USD 100 M, entered administration in March 2025 after failing to raise fresh funding. Sendy, a logistics startup valued at over USD 80 M, became insolvent in 2023 after a key investor pulled out of a down round.

Gro Intelligence, an AI-powered agriculture data company that raised USD 117 M and reached an USD 850 M valuation, closed in May 2024 after missing payroll and cutting 60% of its workforce. MarketForce, a notable well-funded B2B e-commerce player, also had to close shop after a string of challenges.

There is also the view that the funding environment is not the only issue, as Kenya lacks the kind of domestic capital that cushions startups in other markets. Local institutional investors have largely stayed on the sidelines, leaving foreign VCs to dominate deal flow. That dependency makes the ecosystem vulnerable to global sentiment shifts, as the 2024 funding drop demonstrated. Venture funding to Kenyan startups fell 33% that year to USD 318 M, after political unrest and new taxes spooked investors.

A self-reinforcing cycle appears to be at work. Without local capital, Kenyan startups cannot weather downturns. Without exits, local investors have little incentive to enter. Without equity-heavy scaling, unicorns never materialise. Twiga’s administration is the latest signal that the cycle won’t break on its own.

Brutal Hidden Data Show How Uber ‘Self-Harmed’ & Lost Its Way In Nigeria

By Henry Nzekwe  |  September 15, 2026

A Nigerian Uber driver completed about 130 rides over seven months. A South African Uber driver completed 1,142 in the same window.

That 8.8x gap is where the story of Uber’s Nigeria exit actually begins, according to some troubling new data, which shows Uber lost money on a large share of its Nigerian rides for reasons that had nothing to do with competition from Bolt or inDrive. Rather, it was paying drivers more than riders paid it, on short trips, in a market with roughly one-ninth the per-driver volume of South Africa.

That is the central finding of a new report from Obi, a California-based ride-hailing data aggregator that analysed 20,298 trips across 308 drivers between January and July 2026, the final months of Uber’s 12-year run in Africa’s most populous country. The report, titled “The Real Reasons Why Uber Left Nigeria,” offers the most detailed public accounting yet of how a company that helped create Nigeria’s app-based transport market ended up exiting it.

The numbers show a business that was structurally underwater on short rides. On trips under roughly 20 kilometres, Uber paid drivers more than it charged riders, by as much as 23% on some distance bands. At 5 to 9 kilometres, driver pay exceeded the customer fare by 23 percent. At 9 to 13 kilometres, the gap was 19%. Only past 20 kilometres did the fare finally overtake driver pay.

In other words, Uber was subsidising short trips to keep drivers accepting them. That subsidy might have been survivable in a high-volume market. Nigeria’s was not. Over the seven-month window Obi tracked, Nigerian Uber drivers averaged 130 total rides, or about 3.9 rides per active day. In South Africa, Uber drivers averaged 1,142 rides over the same kind of window, roughly 9.9 rides per active day. That is an 8.8x gap in per-driver activity between the two markets.

Low volume plus a per-ride subsidy is a lethal combination. And Uber had almost no room left to fix it through commissions. Nigerian drivers on both Uber and inDrive were already keeping roughly 80 to 90% of the fare throughout the period Obi measured.

Uber’s own cut was thin before the short-trip subsidy was layered on top. Raising commissions would have provoked the kind of driver backlash the company had already seen in Nigeria in 2017, 2023, and again in March 2026, when drivers across Uber, Bolt and inDrive staged a three-day strike over low fares and high commissions.

Pricing was not the answer either. Uber’s per-kilometre fare climbed 71% between January and July, from NGN 574.00 to NGN 983.00. That is a steep increase by any measure, and it still did not close the gap on short trips. Essentially, the platform raised prices by 71% and still needed to subsidise a large share of its rides, which proved to be a structural hole it couldn’t price its way out of.

The macroeconomic backdrop made everything worse. President Bola Tinubu’s removal of the fuel subsidy and changes to the naira exchange rate sent petrol, imported spare parts and vehicle maintenance costs soaring. Fuel prices in Lagos rose from about NGN 800.00 per litre in late February to between NGN 1.3 K and NGN 1.33 K by mid-April, a 60% jump in six weeks. Drivers absorbed that cost without corresponding fare adjustments on most platforms.

Obi surveyed 93 Nigerian Uber drivers the day after the exit was announced. Their responses back up the trip-level data. Asked why Uber left, 57% pointed to currency and inflation pressure, 51% to regulatory or government issues, and 44% to fares and commissions being too low to sustain. Just 25% cited losing to local competition.

Most drivers had already hedged. 80% were multi-apping before the exit was even announced, with 45% pairing Uber with Bolt, which has over six-times more users in Nigeria than Uber, and 19% with inDrive. Only 20% drove exclusively for Uber. Nearly half, 49%, now expect to lose 50% or more of their monthly income. 11% percent expect to lose more than 75%.

“I bought fuel at NGN 1.4 K per litre,” said Peter Obasi, a ride-hailing operator in Lagos, in an interview with The Guardian Nigeria, as fares displayed on the inDrive platform no longer cover his operating costs.

The driver survey also captured something the trip data alone could not. Despite everything, 71% rated their overall experience driving for Uber as very good and another 26% as good. If Uber returned to Nigeria, 90% said they would drive for it again without hesitation. Just 1% said no.

Uber’s exit is not just a Nigeria story. The company has also left Côte d’Ivoire, Tanzania, and Uganda in the past year. It is redirecting capital toward autonomous vehicles, pledging more than USD 10 B to deploy robotaxis and aiming to operate driverless services in at least 15 cities by the end of 2026. Nigeria’s per-trip economics, where gross bookings per trip lagged far behind Uber’s global average, could not compete with that calculus.

Bolt and inDrive are now absorbing the drivers Uber left behind. Bolt, which entered Nigeria in 2016, had already captured an estimated two-thirds of the ride-hailing market by some measures. InDrive, with its negotiable fares and lower commissions, saw a three-fold spike in driver applications within 48 hours of Uber’s exit announcement. Shuttlers, a local startup known for its bus sharing platform, has also moved to fill the void with its new car sharing service.

The ride-hailing market in Nigeria is valued at around USD 450 M and projected to reach USD 879 M by 2031, with over 200,000 drivers, and growing. But the structural pressures that pushed Uber out have not disappeared.

How Madica Found Five Startups In Africa’s Biggest Funding Blind Spots

By Henry Nzekwe  |  September 15, 2026

Louai Djaffer spent years running Emplotic, a recruitment platform he built in Algeria. Somewhere along the way, the problem he kept tripping over stopped being hiring and became everything that happened after; think payroll, records, the paperwork that mid-sized companies across Francophone Africa still handle by hand.

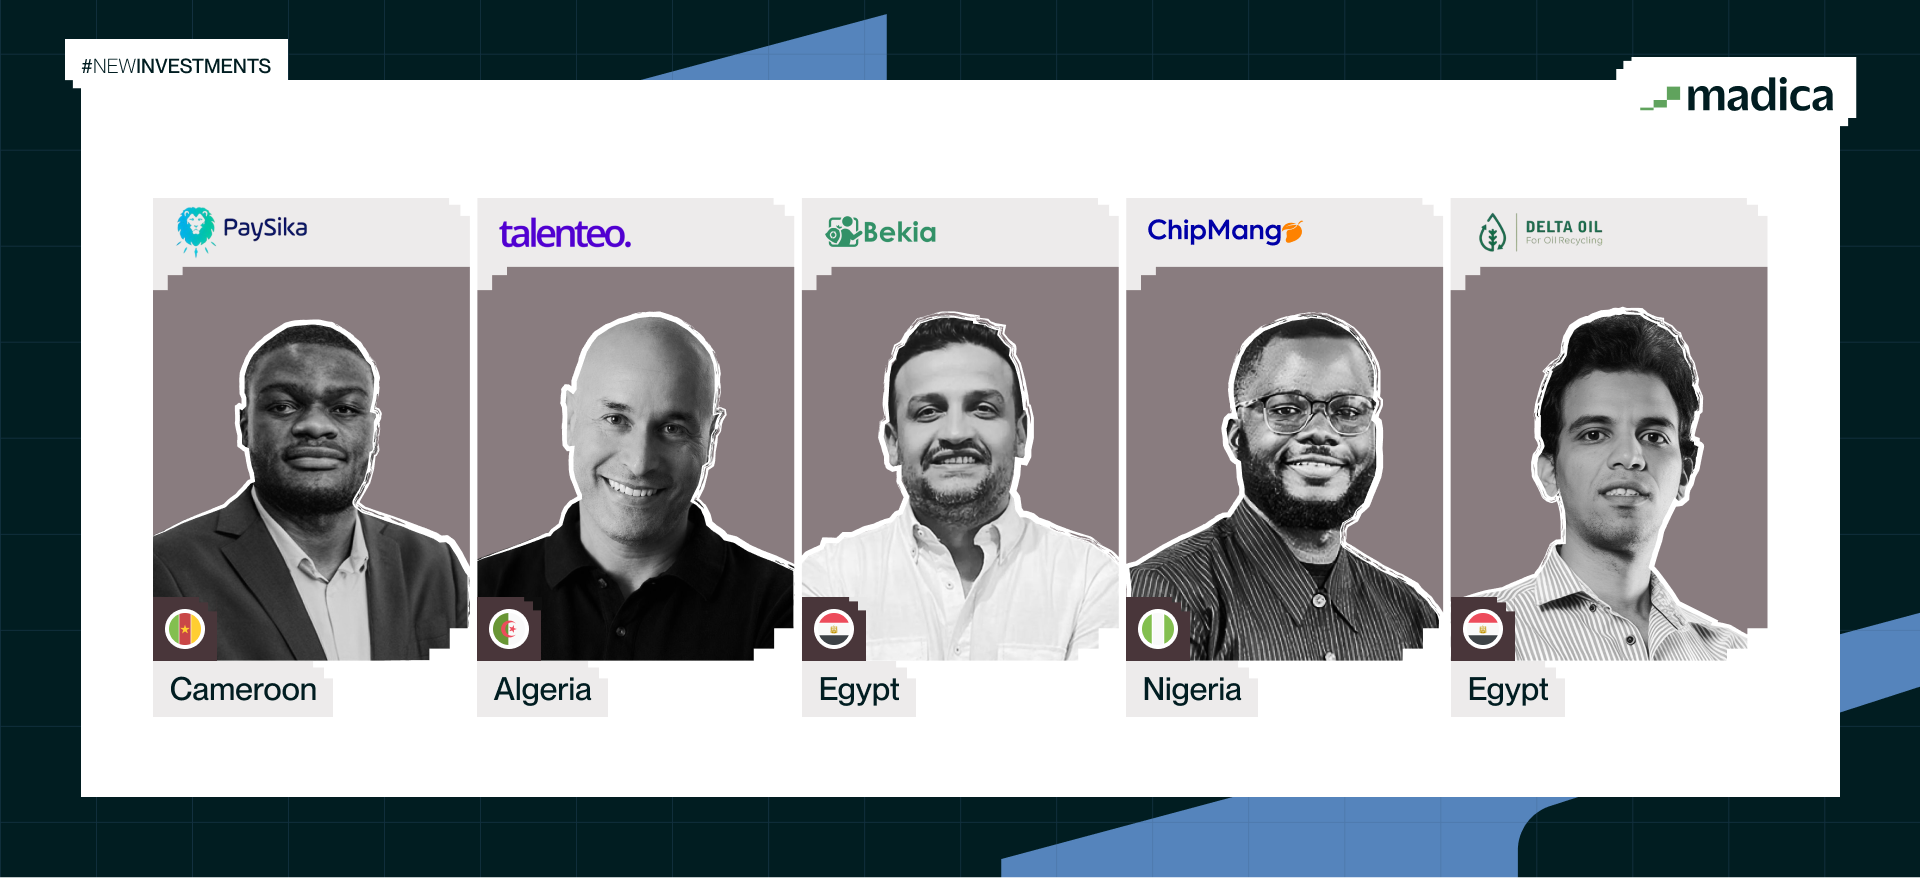
That observation, more than any pitch deck, is what got Talenteo funded. Talenteo is one of five startups Madica announced today, and its first investment in Algeria. The pre-seed investor — the earliest stage of institutional money a company can raise, before it has proven much of anything — also made its first bet in Cameroon, on Paysika, a digital bank for consumers and small businesses across Central Africa. Madica has now written checks in 10 African markets.

African venture capital has long pooled in four places: Nigeria, Kenya, South Africa and Egypt. Founders elsewhere describe a funding desert that shapes everything downstream — how fast they hire, how far they can stretch before revenue arrives, whether they can survive a competitor with a bigger war chest.

“We’ve been very impressed with founders like Louai and Roger and Stezen, who have depth of experience in their various sectors and are solving huge pain points, and are only limited by access to funding compared to their counterparts in the Big 4 markets,” Emmanuel Adegboye, who heads Madica, told WT.

Paysika‘s founders, Roger Nengwe and Stezen Bisselou, are targeting a problem Adegboye described as “significant” not just in Cameroon but across the CEMAC region, the six-nation currency bloc. Their neobank, a bank without branches, run through an app, issues virtual and physical cards that work for international transactions.

The five bets are deliberately scattered. In Nigeria, ChipMango, which recently closed a USD 1.9 M seed round, designs semiconductors and teaches chip engineering. In Egypt, Delta Oil collects used cooking oil and sells it abroad as feedstock for renewable fuel, while Bekia pays households and businesses for recyclable waste. None of these look like the fintech-heavy portfolios that dominated African venture for a decade.

Adegboye frames the timing as continuity rather than a shift. “Madica’s thesis has always been to catalyse funding into markets, sectors and founder profiles that are typically underfunded in Africa,” he said. He named Senegal, Côte d’Ivoire and Uganda as next in line.

The funding climate complicates that ambition. African startup funding remains well below its 2021–2022 peak, and later-stage rounds are taking longer to close. Adegboye insists the downturn hasn’t changed what counts as investable but then describes changes that sound like it has.

Madica now spends more time building co-investment networks, so founders can line up follow-on money earlier. It pushes cash-flow discipline and regular investor updates. And in sparser markets, it now wants “slightly more track record” before backing a company.

For a pre-seed fund, that’s a notable bar. The whole premise of pre-seed is to fund founders before track record exists. Madica hasn’t abandoned that — Talenteo and Paysika were backed largely on their founders’ operating histories — but the bar has moved.

On founder profiles, Adegboye pointed to one group the market continues to underfund. “Female-led companies still get a very small share of venture funding compared to their male counterparts, even though male-founded startups don’t perform any better,” he said. Madica aims for at least half its portfolio to include a female co-founder, a target he said it has met or exceeded.

The operational question is whether a small team can genuinely support founders spread across 10 markets and four sectors. Adegboye’s answer is that most of the programme was built remote-first, with mentorship and expert access delivered virtually, and a mentor roster chosen to reflect that spread. Twice a year, Madica flies its founders somewhere in person; the next gathering is in Cape Town in November, timed around the Africa Early Stage Investor Summit.

Each company gets up to USD 200 K and 18 months of support. Whether that is enough to build a semiconductor business in Lagos or a recycling network in Cairo is a question the portfolio will answer in public, over the next few years, in markets where the next check has historically been the hardest one to find.

The Friends-Turned-Founders Building The Missing ‘Paper Trail’ That Haunts Africa’s Remote Workers

By Henry Nzekwe  |  September 14, 2026

Jennifer Echenim was working remotely for international companies not that long ago, earning money that arrived in fits and starts through a patchwork of platforms.

Withdrawing it meant routing funds through a friend, converting to stablecoins, and navigating peer-to-peer exchanges to access naira. Each step cost money, time, and documentation she thought was unnecessarily complicated.

The real trouble surfaced later, when she moved to the UAE. Opening a local bank account required proof of income, and the financial records her employment history had generated were not recognised by the systems she encountered there. The problem was not getting paid, as it turned out, but proving she had been, because while the money had arrived, the pesky paper trail had not.

“The financial records from my employment history were not recognised by the systems I encountered there,” Echenim says. “So I began thinking more deeply about it.”

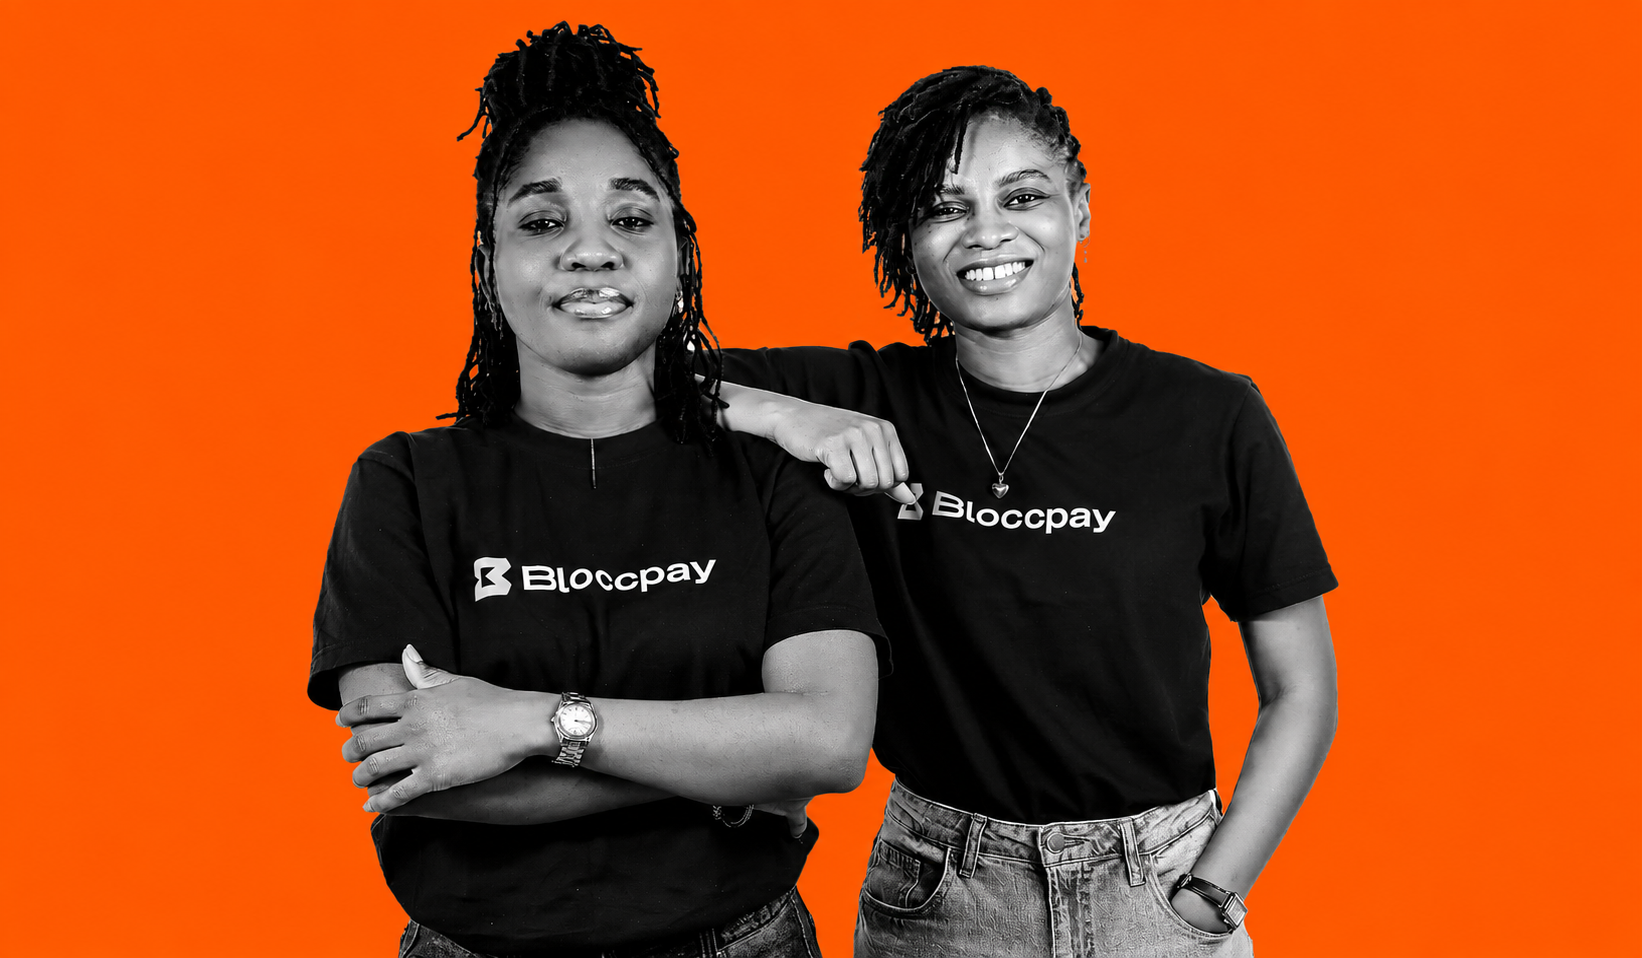
That experience led her, alongside friend-turned-co-founder Ajoke Asunmonu, who had sometimes assisted Echenim with workarounds for her pay headaches, to build Bloccpay, a stablecoin-powered payroll platform for cross-border workers and the businesses that employ them.

The company is now in private beta across Nigeria, Kenya, Ghana, and South Africa, with business customers primarily in the US and UK. Its gross transaction volume grew sevenfold quarter-on-quarter in Q2 2026, and by mid-year it had matched its total volume for all of 2025.

***

An estimated 15 to 20 million African workers now earn across borders. Research from Harvard Business School puts the cost of moving that money at 8.7% to 12.6% of transaction value, well above the 3% target set by the UN. Cutting those costs by half could generate between 900,000 and 1.1 million remote jobs across the continent and add USD 3 B to Africa’s remote work exports.

But Bloccpay’s founders argue the payment itself is only half the problem, emphasising that the other half, what happens after the money lands, is equally critical.

“Traditional employment produces that record as a byproduct,” Asunmonu says, referring to the payslips, tax documents, and recurring credits that salaried workers accumulate. “Independent and cross-border work produces nothing equivalent.”

Ajoke Asunmonu

Asunmonu calls this missing layer “financial identity.” Every invoice raised and payment received on Bloccpay generates a trail showing who paid whom, how much, when, in what currency, and through what channel.

Over time, those records build into a documented history of a worker’s earnings that can be used to apply for a loan, rent a home, apply for a visa, or file taxes. The platform is also planning a feature that lets users upload invoices generated outside Bloccpay, so their history lives in one place.

It is a straightforward idea with an uncomfortable implication. Existing payment platforms, including the ones Echenim used, are designed to move money from point A to point B. Once the transaction clears, the job is done.

“What they weren’t building was the layer underneath,” Echenim says. “The record of the transaction, the documentation it creates, and the financial history it builds over time for the person receiving the money.”

***

The technical machinery behind Bloccpay is more complicated than the pitch suggests. The platform settles transactions in stablecoins like USDC and USDT and runs multichain across Stellar, Base, BSC, and Solana, routing around the high Ethereum fees that made Echenim’s own payments expensive.

Stablecoins are digital tokens pegged to currencies like the US dollar, designed to hold a steady value. They allow money to move across borders without the foreign exchange losses that traditional rails impose.

Africa already has the highest stablecoin ownership rate globally at 79 percent. But while the rails are mature and the cost problem is largely solved on the sending side, the receiving side is where it gets hard.

“Moving that into a bank account or mobile money is where the real work sits,” Echenim says. “Every corridor is its own piece of work. Local partners, local settlement times, local failure modes. Nigeria doesn’t work like Kenya.”

Jennifer Echenim

That operational reality has changed how the company thinks about expansion. “We used to talk about adding countries,” Echenim says. “Now we talk about corridors, because a country isn’t live until money lands the way people there actually get paid.”

The founders are equally blunt about what they got wrong early on. Echenim, had lived with the problem and spent six years building on blockchain, says her engineering instinct was to map every point of friction and abstract it away. What she did not map was where compliance sat. Some of those friction points, she says, “exist for a reason, and you have to design around them rather than through them.”

Asunmonu’s correction came at 3am on December 2, 2025, when a customer needed to pay contractors for the previous month. Bloccpay only supported future-dated payroll. The customer was ready to go back to spreadsheets and manual transfers.

“We had built for the version of payroll that exists in a diagram, not the one that exists in a company,” says Asunmonu, who spent some time at Flutterwave managing enterprise payments accounts, seeing where cross-border flows break at scale.

The team shipped backdated payroll and automatic prorated calculations off the back of that call. “They aren’t edge cases,” she says of the messy realities of real-world payroll. “They’re most of it.”

***

The hardest assumption to prove wrong, both founders agree, is institutional recognition. A bank or consulate will not accept a new kind of income record because the company explaining it is persuasive. “They accept it when it’s familiar, when enough of it exists, and when it resembles documentation they already trust,” Asunmonu says. “Recognition follows the record, not the other way around.”

That is a function of time and volume, and Bloccpay is early on both. The platform is a recipient of a USD 100 K Stellar Community Fund Build Award and a member of the Circle Alliance Program. 

It has matched a full year of 2025 volume in the first half of 2026. One customer started at around USD 1.5 K a month and now runs USD 22 K, growing roughly fourteenfold as they moved more of their payroll onto the platform.

“Aggregate growth can be new sign-ups,” Asunmonu says. “Expansion like that only happens when a business decides to trust you with more.”

For Echenim, the more pointed lesson is about the market itself. “The thing I’ve felt most isn’t about being a woman,” she says. “It’s about building for a market people have already decided isn’t commercially interesting.”

That assumption, she says, shapes everything. How much capital is available. How much explaining you have to do before anyone engages with the product. How often you are asked whether the volumes are really there.

“We’ve had to prove the market exists before we could argue we’re the right people to serve it,” she says. “Most founders only have to do the second part.”

Asunmonu frames the challenge differently. “It has shown me how uneven access can be. Funding, networks, and access to the rooms where decisions are made are not equally distributed, and you feel that as a woman building in a technical space.”

Bloccpay’s bet is that as hiring becomes more global, the financial systems of the countries where workers live will eventually have to recognise income earned across borders.

Time will tell whether that recognition arrives because the records become too voluminous to ignore, or whether the founders run out of runway waiting for institutions to catch up. For now, they are building the records and hoping the recognition follows.

MNT Halan’s Cairo Listing Flies In Face Of African Fintech IPO Exodus

By Staff Reporter  |  September 11, 2026

On Tuesday, MNT Tech Holding for Financial Investments, an arm of Egyptian fintech unicorn MNT-Halan, submitted a formal application to list 1.6 billion shares on the Egyptian Exchange’s main market. The filing caps months of speculation about the company’s public market ambitions and sets up a potential IPO that could value its domestic operations at between USD 900 M and USD 1 B.

The move comes as Africa’s largest fintech players race toward public listings in a remarkable synchronised wave. OPay has hired Citigroup, Deutsche Bank and JPMorgan for a US IPO targeting a USD 4 B valuation, while also weighing a secondary listing in its primary market, Nigeria. PalmPay is preparing a Hong Kong listing. Airtel Money has chosen London, where it could be valued at roughly USD 10 B. All three are Nigerian-linked businesses, and all three are listing abroad. MNT-Halan is the only one heading to a local bourse.

It raises questions that should worry policymakers from Lagos to Nairobi as to why Africa’s most successful fintech companies, built on African consumers and transaction volumes, taking their equity stories to New York, Hong Kong and London instead of staying home,

MNT-Halan’s decision to list in Cairo offers one possible answer. The company, founded in 2018, has grown into a vertically integrated fintech platform offering micro-business lending, payments, consumer finance, and e-commerce. It now serves more than 7 million customers in Egypt alone and has disbursed over USD 10 B in loans since inception.

In June, Al Ahly Capital, the investment arm of the National Bank of Egypt, led a funding round that lifted the company’s overall valuation to USD 1.4 B. The IPO would cover only the Egyptian business, leaving operations in the UAE, Turkey and Pakistan private.

The listing is also a test for the Egyptian Exchange. The benchmark EGX index is up over 23.6% year-to-date, and local fintech Valu saw its shares jump 852.4% on its first day of trading last year. But the exchange still lacks the depth to compete with global venues.

Moreover, considering MNT-Halan’s peers elsewhere, for instance, a survey found that 76.5% of Nigeria-funded startups hold dollar capital, making exchange rate instability a critical factor in listing decisions. Companies generating revenue in naira but seeking dollar exits face a currency mismatch that local markets cannot easily resolve. The Nigerian Exchange has recorded zero startup IPOs.

MNT-Halan is betting that Egypt can offer something different. The company holds more than 25% of the country’s microfinance market and has positioned itself as the seventh-largest financial institution in Egypt by reach. Its deep local roots, combined with a domestic investor base that has already demonstrated appetite for fintech stocks, may make a Cairo listing more viable than it would be for a Nigerian counterpart. The Egyptian government, meanwhile, has been actively supporting digital transformation and broadening access to financial services through technology-driven platforms.

Terra Industries’ First Commercial Deals Stoke Race For Nigerian Lithium Amid Concerns

By Staff Reporter  |  September 11, 2026

Terra Industries’ commercial division is barely a week old and already paying for itself. The Nigerian defence-tech startup disclosed today that it has closed USD 2 million in contracts to protect lithium mining operations in Nigeria.

The company will deploy 20 sentry towers and four Iroko drones across two mining sites, providing surveillance, real-time threat detection, and response through ArtemisOS, its autonomous command-and-control layer. More sites are expected to come online as the operators expand. 

The contracts are a quick validation of Terra’s new commercial push, led by Todd Stiefler, the Palantir alumnus appointed director of commercial in August. The division was built to sell autonomous security systems to private infrastructure operators across Africa, the Gulf, South America and South Asia.

Until now, Terra’s work has been split between government clients and commercial operators, but the new unit formalises the push into private sector security. The company says its systems already protect assets worth about USD 11 B, mostly in energy and mining.

Lithium is a strategic mineral for Nigeria. In May, authorities arraigned 15 Chinese nationals and nine Nigerians over alleged illegal mining in Nasarawa State. The government is trying to attract investment into battery-material processing, but artisanal and organised illegal operations have made securing these assets a national priority.

Terra is selling itself as the technological answer to a problem the state has struggled to police. The company says its in-house manufacturing of airframes, propellers, battery packs, and software allows it to cut hardware prices by up to 55% compared to international competitors.

The new contracts, however, put the sovereignty debate in sharper relief. Terra often reiterates that its mission is to give the Global South the technological edge needed to secure its future. But its funding comes from 8VC, the firm with ties to foreign intelligence actors founded by Palantir co-founder Joe Lonsdale, and its commercial division is now led by a Palantir veteran.

The lithium mines Terra is now protecting sit at the centre of Nigeria’s resource sovereignty ambitions. Who controls the data flowing through those sentry towers and drones could be consequential. Mining security data includes movement patterns, operational vulnerabilities, and real-time surveillance feeds, intelligence that could be as valuable as the lithium itself.

Terra has not disclosed the names of the two mining companies, nor the specific locations of the sites. The company says deployments will expand as each operator brings additional sites online. For now, the contracts are a commercial win and a political test. Terra has proven it can sell. Whether it can deliver sovereignty, on its own terms, is still unproven.

South African VC Returns Rival Developed Markets As Exits Surge Counters Scepticism

By Staff Reporter  |  September 11, 2026

One of the perennial gaping holes in African venture capital’s growth story, exits, is finally starting to close in South Africa.

New data shows 226 realised exits since 2009, returning more than ZAR 2.9 B (~USD 175 M) to investors at a 2.45x multiple. That performance matches or exceeds US and European benchmarks, upending a decade of LP reluctance based on a perceived lack of exit history.

For years, global backers passed on African markets, branding them too risky with no track record for getting money out. They often cite a lack of exit history and, as a result, are hesitant to commit. The data, however, tells a different story.

A pair of new studies from the SA SME Fund, Endeavor South Africa and SAVCA have pulled together a comprehensive picture of South African venture capital exits. The numbers tell a story that doesn’t match the narrative that has dominated LP due diligence calls for the better part of a decade.

Between 2009 and 2026, South African fund managers reported 226 realised exits. The capital-weighted realised returns ranged from 2.01x to 2.45x invested capital. For every rand invested in exited deals, the reported portfolio returned ZAR 2.45 in realised cash proceeds before fund-level costs, fees and taxes.

Compare that to the numbers the industry treats as gospel. The US sits at 2.0 to 2.3x. Europe at 1.7 to 2.1x. The UK at 2.2x. South Africa matches or beats every one of them.

“African VC does not have an exits problem,” said Wura Kayode, founder and CEO of FundFlow.VC, in her analysis reacting to the findings. “It has a perception problem.”

The data bears that out. Of the 226 exits analysed, the majority were profitable. Losses and write-offs occurred at expected levels for venture capital investing. The median realised investment was modestly profitable. And like venture markets everywhere, a relatively small number of high-performing investments drove a significant share of total value creation, mirroring the power-law return profile observed internationally.

The South African story is particularly interesting in how the exit landscape has shifted. For most of the past decade, a South African tech founder looking to sell had to hope a foreign buyer came knocking. That has changed.

Domestic mergers and acquisitions, led by the country’s banks, have emerged as a major exit route. Nedbank bought payments fintech iKhokha in a ZAR 1.65 B deal. Capitec acquired WalletDoc. TymeBank swallowed SME lender Retail Capital. Lesaka Technologies took over payments group Adumo. Mastercard is pursuing a deal for BVNK. Motorola Solutions bought RapidDeploy. Ticketmaster acquired Quicket. And Optasia listed on the JSE.

“Between 2015 and 2020, the businesses that exited were all sold to international companies,” said Endeavor South Africa managing director Alison Collier at a briefing on the research. “That changed in the early 2020s. Now we’re seeing many more local corporates looking to acquire”.

SAVCA investment data suggests the emergence of a second investment cycle from 2019 onwards, characterised by a marked increase in new deal activity. More than 1,100 companies have received VC funding since 2016. With a median holding period of around six years, much of the capital deployed in recent years has yet to reach typical exit maturity. The first wave of related exits is only beginning to emerge from 2024 onwards.

There are caveats, however. The research reports only the portion of exit value attributable to the reporting fund manager’s equity stake, meaning the actual market valuations at exit were often larger. Data collection relied on fund manager self-reporting, and 43 confirmed profitable exits did not disclose exit values, meaning the reported aggregate proceeds almost certainly understate actual realised value.

But the broader point stands that South Africa’s venture capital ecosystem is producing realised returns comparable to more mature international markets.

How A ‘Tiny’ Trade Four Years Ago Shook Africa’s Biggest Bitcoin Company

By Staff Reporter  |  September 4, 2026

Africa Bitcoin Corporation, the continent’s first listed company to adopt bitcoin as a treasury reserve asset, was days away from a landmark secondary listing on London’s Aquis Growth Market. Instead, its founder and CEO Warren Wheatley, his wife Tatum Keshwar-Wheatley, and chief investment officer Akshay Karan are now banned from South Africa’s financial services industry for 20 years.

The Financial Sector Conduct Authority dropped its enforcement action on 30 August 2026, revealing that the three executives coordinated trades over just four days in September 2022, when the company was still called Altvest Capital and listed on the Cape Town Stock Exchange.

According to the FSCA, they created an artificially inflated share price and a false impression of demand. The regulator imposed a combined ZAR 10 M in penalties: ZAR 5 M on Wheatley and his company WGW Capital, ZAR 3 M on Keshwar-Wheatley and her firm, and ZAR 2 M on Karan. All three have been debarred for two decades.

The trades happened in September 2022, just four months after Altvest’s initial listing. At the time, the stock was thinly traded, meaning relatively modest transactions could swing the price significantly. The executives have disputed the findings, arguing the amounts involved were tiny and that they were merely testing whether tax was being applied correctly. The FSCA rejected this, saying the issue was not the amounts but the harm caused and the intent behind the trades.

The company’s board learned of the FSCA decisions on 30 August. By the next day, Wheatley and Karan were on precautionary leave, Keshwar-Wheatley’s consulting services were suspended, and Stafford Masie, an existing executive director, was installed as interim CEO. The company has been at pains to clarify that the FSCA made no findings against any entity within the group, only the individuals.

Masie struck a measured tone in his first public remarks. “We are sympathetic to what Warren, Akshay and Tatum are experiencing,” he said. “They have played an important role in building an incredible business.” But his priority, he added, is to “hold the line, providing stability, protecting what has been built” while the three challenge the FSCA’s decision.

The irony is that the company’s entire pitch to London investors was built on the credibility of its leadership. Africa Bitcoin Corporation holds 5.53 bitcoin on its balance sheet, worth about ZAR 6.68 M, and lends to African small and medium-sized businesses. It is listed on the JSE, A2X, the Namibian Stock Exchange, and the OTCQB in the US.

The London listing was meant to be the capstone of an ambitious expansion, giving UK and European investors direct access to what the company calls the world’s first bitcoin-backed SME growth accelerator. That pitch now has a hole in it.

South Africa has licensed more than 300 crypto asset service providers and is building one of the continent’s more robust regulatory frameworks for digital assets. The regulator has been conducting supervisory inspections and establishing engagement forums with the crypto industry. Debarment is one of the most consequential tools in its arsenal, and it has now used it against the founding team of Africa’s most visible bitcoin company.

Wheatley, through his company email, told ITWeb that he will not litigate the matter in public. But the Financial Services Tribunal will hear his case. For now, the company is in damage control mode, trying to convince investors that the entity itself remains sound even as its founders are cast out of the industry they built.

As Uber Quits Nigeria, A Plucky Startup Just Launched A Timely Alternative

By Henry Nzekwe  |  September 4, 2026

Barely days after Uber shut down its operations in Nigeria, a local mobility company launched a service that looks a lot like what Uber left behind, but with a twist.

Shuttlers, the technology-enabled shared mobility platform known for its bus service, announced the launch of Shuttlers Pod on Friday, a scheduled door-to-door car service for commuting to work, events and other destinations across Lagos.

The service matches three to four riders travelling the same route, picking each up from their doorstep and dropping them at their exact destination, with the option to book the vehicle privately. Every trip comes with a named driver, a fixed fare and a guaranteed pickup, with no surge pricing or roadside negotiation.

The timing is hardly coincidental. Uber’s exit after 12 years in Nigeria left a vacuum in the market for scheduled, predictable urban transport. The company’s departure was part of a global restructuring that saw it also exit Uganda, as it pivots aggressively toward autonomous vehicles and robotaxis. But in Lagos, where the average commuter spends more than 30 hours a week trapped in traffic, the need for reliable mobility has not diminished. Shuttlers Pod looks like an attempt to fill that gap on its own terms.

The service applies Shuttlers’ scheduled bus model to private vehicles, replacing the traditional bus stop with door-to-door pickups and drop-offs. Shuttlers claims each Pod trip costs roughly 50% less than typical ride-hailing fares, enabled by its advance-booking and fixed-pricing model.

The company says its existing bus service already saves commuters between 60% and 88% on transport costs compared to ride-hailing, while reclaiming eight to 12 hours from gridlock every month. Pod extends that logic to smaller vehicles and more personalised trips.

Shuttlers is no newcomer. Founded in 2016, the company recently surpassed 10 million completed journeys and became Nigeria’s first private mobility operator to be listed on Google Maps Transit. It serves more than 600,000 monthly trips across more than 1,000 itineraries in 400 routes, operating more than 430 buses daily across Lagos, Abuja and Port Harcourt. The company reports a 99% trip completion rate and a 99.94% incident-free record since launching.

Nigeria’s ride-hailing sector is valued at around USD 450 M and projected to reach USD 879 M by 2031, with over 200,000 drivers. Uber left a growing market it could not profit in on its own terms. Every remaining platform inherits the same fuel, maintenance and affordability squeeze that made Uber’s position untenable.

Bolt has emerged as Nigeria’s most downloaded mobility app, overtaking Uber and inDrive, while inDrive and local platform LagRide continue to operate. But none of them offer a scheduled, fixed-price ride from door to door, booked in advance, which is what Shuttlers Pod promises.

Nigeria’s cost of living is rising faster than incomes. With that reality, the smartest way to move people is through shared mobility, said Damilola Olokesusi, CEO and co-founder of Shuttlers.

“We’ve spent the last decade making scheduled, shared transport reliable and affordable, and Shuttlers Pod brings that same thinking to scheduled private and shared trips that are safe, premium and affordable, from your doorstep to exactly where you need to be,” she said.

For now, Shuttlers Pod is open for waitlist sign-ups. Whether Lagos commuters, still adjusting to life without Uber, will embrace a service that asks them to plan ahead rather than summon a ride on demand is the ultimate question. But in a city where traffic is the only certainty, advance planning might be exactly what works.