Thank you for signing up for our free newsletter. By entering your email id you agree to receive our free newsletter and other promotional communication.
South Africa’s Gig Economy Becomes A Bargain With AI Skills Shortage Looming
By Staff Reporter
|
March 31, 2026
South African freelance talent is costing local businesses up to 81% less than the global rates on platforms like Upwork, but a new report suggests the country’s gig economy is not just a cheap alternative but also undergoing a structural shift where artificial intelligence is redrawing the map of who gets hired.
The 2026 State of the South African Freelance Economy report, published by local marketplace Freelance Locals, analysed platform data from 2,102 registered professionals and 180 posted projects. It found that South African software developers charge a median rate of ZAR 350.00 per hour, roughly USD 18.60 at current exchange rates.
The global median for similar work on Upwork ranges from USD 50.00 to USD 100.00 per hour. That translates to savings of between 47% in digital marketing and 81% in software development for companies hiring locally.
But the cost advantage is only part of the story. The report’s AI displacement risk model, applied to all 180 projects, found that only 4% of posted work falls into categories highly exposed to automation. These are roles like generic content writing or basic data processing. Another 59% were classified as AI-augmented, where human judgment remains essential, but AI tools can speed up delivery.
The catch is that supply is not keeping up with demand. While 8.9% of client project briefs explicitly required AI competency, only 5.3% of freelancers on the platform offered AI-related skills in their profiles or service listings. That 3.6 percentage point gap represents a window for early adopters. The report projects AI proficiency will shift from a competitive advantage to a baseline expectation by late 2027.
South African freelancers are also decentralising. The platform recorded professionals across all nine provinces, with emerging nodes in towns like Witbank, Thohoyandou, and Bethlehem. Two-thirds of all projects posted allowed fully remote delivery, meaning location is increasingly irrelevant for both talent and employers.
The local supply base operates within South African regulatory frameworks—SARS, FICA, POPIA—eliminating cross-border compliance risks. For startups building lean teams, the combination of cost efficiency, regulatory alignment, and a 73% share of freelancers with five or more years of experience offers a clear alternative to hiring offshore.
The report’s findings arrive as South African businesses across sectors report persistent difficulty filling critical technical roles despite high overall unemployment. For a generation of workers in smaller towns, the freelance economy may offer a path around the geographic barriers that have long defined access to formal employment.
Feature Image Credits: Proinvoice
Newcomers Are Tinkering With New Models To Replace Uber In Nigeria
By Henry Nzekwe
|
November 12, 2026
The scramble to replace Uber in Nigeria is being fought over who absorbs the cost of a trip, and the new entrants are making bets that Uber itself could not sustain.
Uber ended operations in Nigeria on September 2 after twelve years, leaving behind a market worth about USD 450 M in 2025 and projected by Ken Research to reach USD 982 M by 2032. Bolt and inDrive moved quickly to absorb riders and drivers, but a cluster of newer and local players is now testing structurally different models. Loop, FastDrive, SimpliRide and Shuttlers are shaping up as not merely cheaper versions of Uber but experiments in who pays when the fare does not cover the journey.
The most aggressive of these is Loop, which launched in Port Harcourt and Delta State in October and says drivers keep 100% of their fares, paying the platform through a subscription rather than a per-trip commission. FastDrive, founded by Okechukwu Mathew and launched publicly on October 15, takes a related route. Drivers set their own per-kilometre price within limits, pay no percentage commission, and owe a flat NGN 1 K (about 74 cents) daily fee after their first two rides.
On a strong day, the appeal is straightforward. A driver on a 25% commission who grosses NGN 40 K (~USD 30.00) hands over NGN 10 K (USD 7.43). On FastDrive, the same driver pays less than a dollar, provided the rides arrive. But the risk has not disappeared. Under a commission model, the platform earns less when the driver earns less. Under a subscription or a daily fee, the driver owes the platform whether the day is good or bad. A fuel queue, a police checkpoint, a breakdown, a slow Monday, and the fixed cost is still due. The model that looks most driver-friendly on a busy day can be the least forgiving on a quiet one.
inDrive’s recent move is the clearest admission that pure negotiation has a ceiling. The company built its Nigerian business on letting riders name a fare and drivers accept, reject or counter, charging a service fee of about 10%. It insists the bidding model is intact.
“Our model is the same. We didn’t change overnight. We just introduced the One Click option, which lets you skip bidding if you are in a hurry,” the company says. But One Click removes the negotiation and lets inDrive set the price. Fares on One Click run roughly 40% to 50% higher than the recommended fares on the basic ride category, an observation of the app reflects, though the option may be a way to help drivers earn more without leaving them to riders who bid below acceptable levels.
***
Shuttlers is not competing inside that same on-demand frame. The company has run scheduled shared buses in Lagos, Abuja and Port Harcourt since 2016, completing more than 10 million journeys and operating over 430 buses daily. In September, shortly after Uber’s exit, it launched Shuttlers Pod, a door-to-door car service that carries three to four commuters who book in advance and share the vehicle, with a fixed fare and no surge pricing or roadside negotiation.
Pod trips cost roughly 50% less than typical ride-hailing fares, enabled by advance booking and shared occupancy. “Nigeria’s cost of living is rising faster than incomes,” chief executive Damilola Olokesusi said at the launch. “With that reality, the smartest way to move people is through shared mobility”.
The challenge these entrants are trying to surmount is the one that broke Uber. A report by Obi, a California-based price and trip data aggregator, found that Uber paid drivers more than it charged passengers on trips shorter than roughly 20 kilometres, with the gap reaching 23% on journeys between 5km and 9km. Nigerian Uber drivers averaged 130 rides over the first seven months of 2026, against 1,142 for Uber drivers in South Africa, an 8.8-fold gap in per-driver volume. “Low per-driver volume plus a per-ride subsidy is a bad combination: there’s no scale to absorb the loss,” the report said.
Fuel has not helped. Petrol has risen from about NGN 830.00 a litre to roughly NGN 1.4 K, a near-70% increase in the single largest operating cost, while platform commissions on the established apps have stayed between 20% and 35%. Bolt’s Nigeria driver guide lists a 20% commission, and the Amalgamated Union of App-Based Transporters of Nigeria has demanded a 10% cap and a fare review, staging a strike in October that shut down the Bolt and inDrive apps in Lagos.
Bolt, which held the largest share of Nigeria’s market by the time Uber left, recorded a 92% week-on-week increase in Nigerian driver registrations after the exit. inDrive saw app installs surge 96%, according to local reports. But Ayoade Ibrahim, co-founder of the drivers’ union, warned that reduced competition over time could lead to less favourable terms for both riders and drivers, and that the platforms that last will be the ones that can hold a fare high enough for drivers and low enough for riders while still funding support, insurance and compliance.
That is the unresolved question at the centre of Nigeria’s ride-hailing reset. Subscriptions make drivers pay upfront while daily fees make them pay regardless. Meanwhile, One Click quietly concedes that negotiation alone underprices the work and shared scheduled rides avoid the problem by selling a different product. None of these models has yet demonstrated that it can carry the full weight of on-demand mobility at scale in a market where fuel, inflation and currency have already broken one global operator.
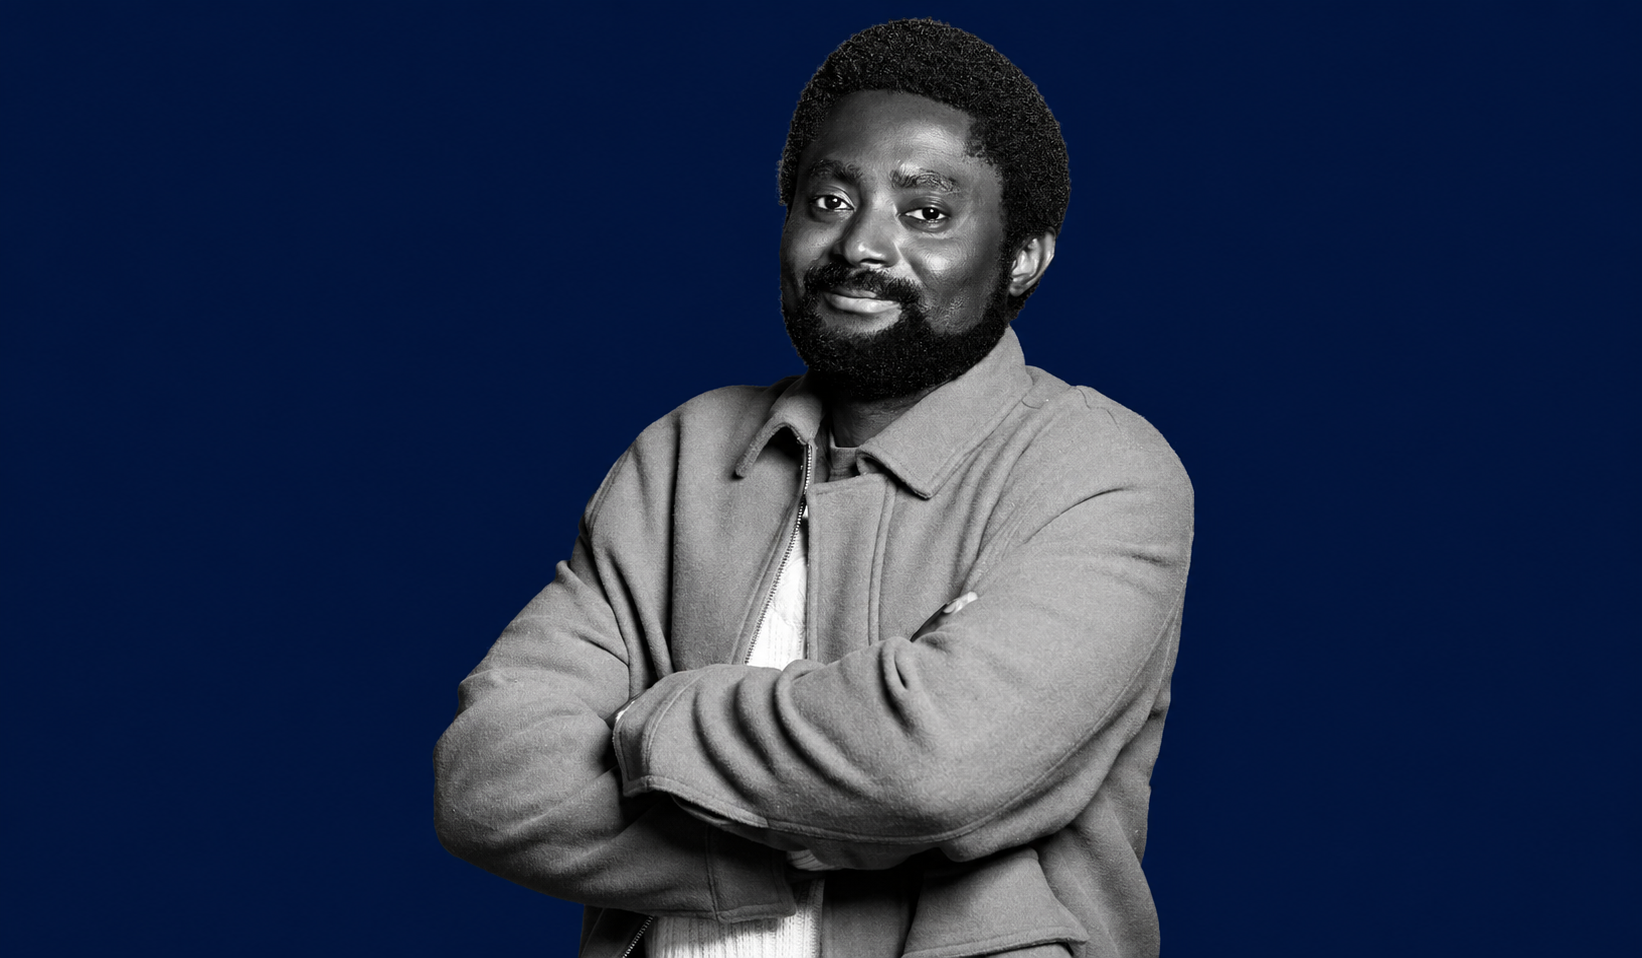
The Unlikely Rise Of A Sickle Cell Survivor Behind A Data Centre & Tech City In Nigeria’s Overlooked Region
By Henry Nzekwe
|
November 11, 2026
The meeting nearly ended with Ugi Augustine Ugi thrown out of the room. It was 2016, and he had come to tell the Calabar Carnival Commission that its biggest annual event was leaving money on the table. Why, he asked, did a festival that drew 100,000 people a day still depend on government funding every year? Why not merchandising, a streaming economy, commercial sponsors?
“They were not ready for that conversation,” Ugi tells WT. Nearly a decade later, his company runs the carnival’s digital registration, voting and stakeholder systems.
That persistence runs through Nugi Group, the company Ugi founded in 2016 in Calabar, a port city in Cross River State in southern Nigeria. It also explains a business that has grown by taking on problems others avoided, often in places others ignored.
Ugi was born with sickle cell anaemia. The illness shaped his first ambition. He wanted to become a doctor because he wanted to help people like himself. “Medicine made sense to me as a child because of what I was living with,” he says.
The pivot came in secondary school at the West African Peoples Institute in Calabar, where he was a laboratory prefect. In 2004, a telecoms engineer arrived to install computers. Ugi kept asking questions about the internet and how the systems worked. Those conversations opened a door that medicine could not close. He later realised he had not abandoned the original impulse. “I still wanted to solve problems and improve people’s lives,” he says. “Technology simply became the tool I chose to do it.”
By 2006 he was learning web development on a partial scholarship and working in a cybercafé. His parents, both civil servants, were not impressed. Technology, in their view, was a path to becoming a secretary, he said in a previous interview in which he also revealed that he entered a televised game show on his father’s phone, won NGN 20 K (around USD 155.00 at the time) , and used his share to pay for a programming course. He never collected the certificate after a dispute over e-books, but he kept the knowledge.
***
Nugi nearly did not survive its early years. The company grew to 23 employees, then shrank to five as clients paid late and deals collapsed. “The most dangerous thing an early-stage company can do is grow its headcount before it’s grown its revenue discipline,” Ugi tells WT.
The near-death experience hardened the company. Every hire, product and partnership, he emphasised, had to justify itself. There were other low points, including a major health setback that forced him to pause almost everything. He wrote about that period in a memoir, Blood of the Phoenix.
What Nugi built instead was a business anchored in government contracts, an unusual path for a Nigerian tech company seeking scale. It took on revenue administration, land management and citizen services for Cross River State.
The founder says its systems helped the state grow internally generated revenue, the taxes and fees the state collects itself rather than federal handouts, by 60.6% to NGN 36.3 B between June 2023 and May 2024. By December 2024 the figure had reached NGN 46 B. More than 7,500 land files have been digitised, and certificate-of-occupancy processing has been cut to 21 days for government land.
The numbers are looking up, though the causal chain is harder to verify. Revenue can rise because software closes leakages. It can also rise because enforcement tightens, tax rates change, or inflation pushes nominal receipts up. Nugi’s biggest client is also its biggest concentration risk given that state budgets tend to move with oil receipts and political priorities. A change of governor can change a vendor’s fortunes overnight.
Ugi is aware of the scepticism. He points to Cally Air, the state-owned airline, as an example of what he means by government needing expertise rather than cash. “Five aircraft, no naira of government funding, yet flying on goodwill to build a sustainable, independent business model,” he says.
Cally Air is owned by the Cross River State government, and the state procured its fleet. Ugi says the government gave goodwill, introductions and access to partners, while Nugi brought the engineering and commercial structure. He notes that the distinction between government money and government goodwill is a fine one, and it defines both the risk and the opportunity of his business model.
***
Nugi did not raise venture capital. Ugi says it was both a constraint and a choice. “We were based in Calabar, building technology for government and businesses. We were not a consumer startup chasing millions of users, so the funding ecosystem was not really designed for us,” he says, while also implying that the constraint became a discipline. “You cannot spend 18 months figuring out whether something works while burning someone else’s money.”
In 2024, he turned Nugi Tech into Nugi Group, adding education, agriculture, media, infrastructure and real estate. The thesis, he says, is overlooked talent and overlooked opportunities. He points to Terra Grid, a surveying and mapping business built around a brilliant, young surveyor he met in Calabar, at a time when the World Bank valued Nigeria’s land systems at more than USD 300 B. “People look at technology, agriculture, construction, media and real estate and see diversification,” he says. “I see the different parts of an ecosystem.”
The ecosystem is anchored by a plan for a technology city in Akpabuyo, 23 minutes from Calabar airport, with a Tier IV data centre at its core. Tier IV certification means 99.99% uptime, the kind of reliability banks and cloud providers need to host critical systems locally. Nugi says the facility will draw power from a nearby hydro turbine, an 80-megawatt solar farm, Cross River’s gas reserves and the national grid as backup. It is also exploring a subsea cable landing in Akpabuyo.
The gap between software contracts and capital-intensive infrastructure is vast. A data centre of that specification demands financing, engineering talent and power reliability at a scale Nugi has never operated. Ugi says the wider city is a nine-year project. “Lagos already had many people solving Lagos problems,” he says. “Cross River had gaps that needed people willing to build.”
At 40, he frames success in terms of legacy rather than achievement. “I want to create opportunities for other people,” he says. “I was once a young boy in Calabar trying to figure out what was possible. If what we build makes that path easier for the next person, that means more to me now than simply building another company.” The harder question is whether the path Nugi is building can outlast the political goodwill that helped clear it.
M-Pesa’s Dominance and Kenya’s digital payments landscape
By Ray Munene
|
November 10, 2026
Around the world Kenya is largely known as the home of innovations in digital payments.
This is mainly due to Safaricom’s flagship offering, M-Pesa. Since its launch in 2007, M-Pesa has allowed more Kenyans to swiftly send and receive money through the convenience of their mobile phones. In March 2026, exactly 19 years after M-Pesa’s launch, Safaricom announced that the mobile money platform had hit the milestone of 40 million customers.
In a research paper on mobile money payments, the World Bank described the service as follows: “M-PESA’s original core offering was the P2P payment – enabling customers to send money to anyone with access to a mobile phone. It opened up a market for transactions which previously were handled largely informally – through personal trips, friends, and public transport networks.”
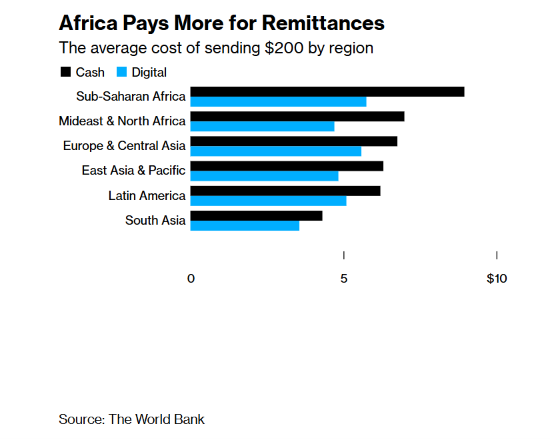
Africa still remains the region with the highest fees for sending money.
Source: The World Bank / Bloomberg
Just as M-Pesa has transformed the financial landscape in Kenya, it is also an expensive product from a consumer point of view. This has led to increased competition from banks, neobanks and fintechs. The banking sector, through various Kenyan Banks has tried to curb M-Pesa’s market dominance through various offerings. I&M Bank removed all charges for bank-to-mobile-wallet transfers. Loop DFS has been hailed for maintaining free transfers before it was rebranded by NCBA and the charges were reintroduced.
In 2009, TEAMS (The East African Marine System), connecting Mombasa with Fujairah, greatly reduced the cost of internet access. This opened up access to the digital space, and this transition saw the financial needs of the population expand from simple P2P payments to digital commerce, BNPL solutions, stock market trading, overseas money transfers and offshore investments. Safaricom itself has also noted the growing needs and has developed new products. In a statement, Safaricom noted “investment and wealth management through Ziidi MMF, Ziidi Trader, credit services like Fuliza and KCB M-PESA.” . It continued to state, “business solutions such as Lipa na M-PESA, Pochi la Biashara and Global Pay.”
Indecisive government action:
In July 2022, the Asset Recovery Agency sought court orders prohibiting Flutterwave from doing business in Kenya. In March 2021, following a US$170 million Series C funding round, Flutterwave officially became a unicorn, surpassing the billion-dollar mark. Iyinoluwa Aboyeji, Adeleke Adekoya and Olugbenga Agboola founded the company in 2016. Flutterwave’s mission was to become a payment gateway that would revolutionise the speed of transactions within Africa. The Asset Recovery Agency claimed that Flutterwave had breached the country’s anti-money laundering laws. The firm’s funds in Kenya, amounting to $43 million, were frozen.
ARA dropped the charges after a couple of months, coinciding with a new government taking over just a few months earlier. Flutterwave CEO Olugbenga Agboola later made a public plea for a renewed licence, promising to expand the company’s footprint in Kenya.
In addition to this, the Central Bank of Kenya issued a directive pausing banks from doing business with Flutterwave and Chippercash. The CBK directed banks not to deal with the two entities due to a lack of proper licensing. The directive read in part: “It has come to the attention of the Central Bank of Kenya (CBK) that Flutterwave Payments Technology Ltd and Chipper Technologies Ltd have been engaging in the money remittance business without licensing and authorisation by CBK.”
Market entrants:
Newer players have recently pivoted to digital currencies and stablecoins, thereby avoiding regulations by central banks and oversight authorities. Kenya’s President assented to the Virtual Asset Service Provider Bill, and it officially became law on 4th November 2025. The law placed numerous requirements on companies planning to venture into the space. Under the requirements that took effect from November 2026, a stablecoin issuer needs a minimum capital of ksh 300 million. A virtual wallet provider needs a minimum capital of ksh 150 million. This sets a precedent as the first of its kind in East Africa.
Kenya’s bank-to-bank solution:
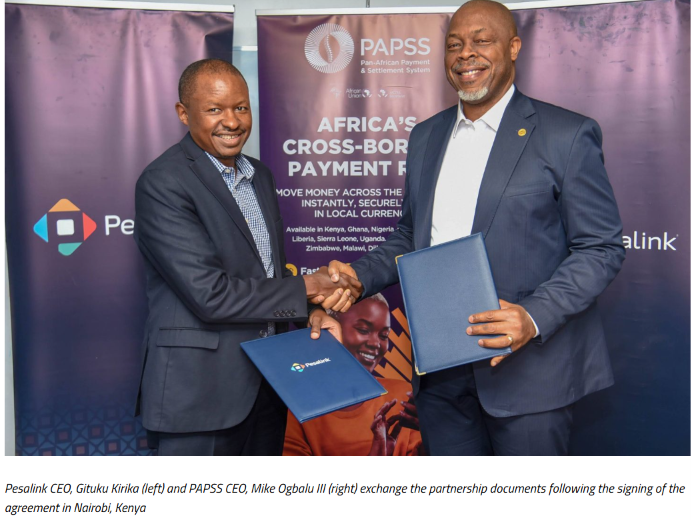
The Kenya Bankers Association (KBA) through its subsidiary, Integrated Payment Services Limited owns PesaLink, an instant payment network . The instant payment service recently announced a partnership with the Pan-African Payment and Settlement System (PAPSS). The partnership aims to “ease cross-border payments and speed up regional financial integration.”
courtesy Afrexim Bank
PesaLink has been acknowledged at home as having lower rates than Safaricom’s M-Pesa. The bank-to-bank system also enjoys the support of Kenya’s banks, as the nation’s major banks are connected via PesaLink.
Kenya’s financial landscape is constantly evolving and M-Pesa’s relevance is slowly being eroded thanks to cheaper digital solutions in the market. What sets M-Pesa apart is it’s domination of mobile money payments, In contrast, the battle for instant account transfers is being led by PesaLink.
The AI Bank Promising To Fix Nigeria’s Money Problems Has A Lot To Prove
By Staff Reporter
|
November 9, 2026
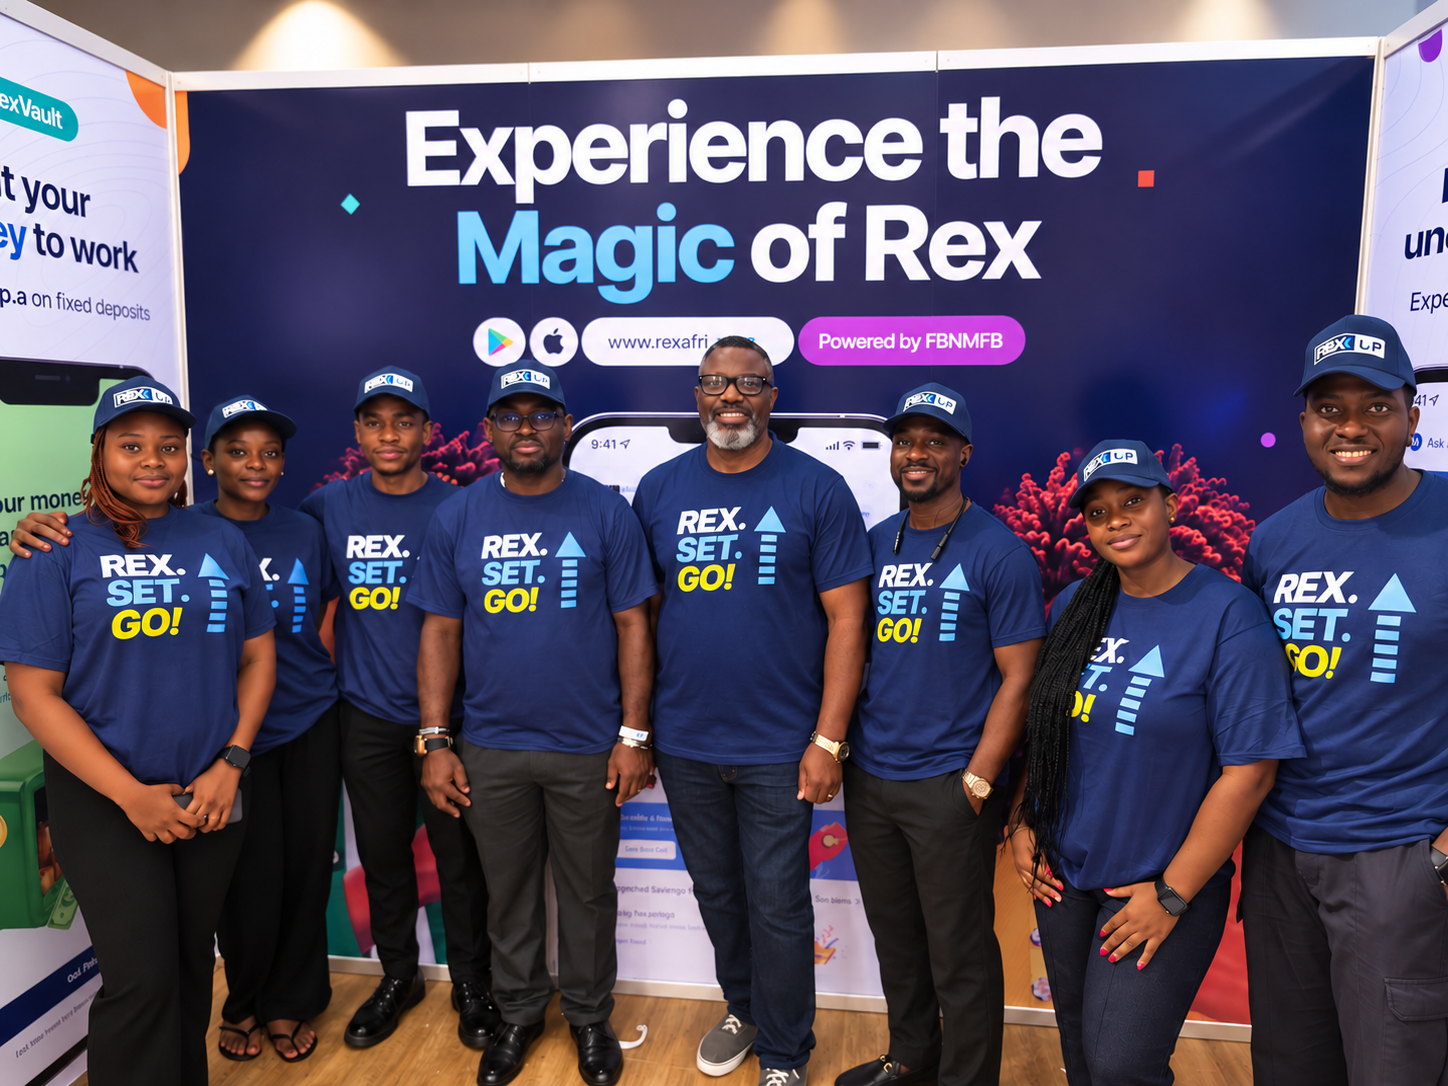
Nigeria’s newest bank has a simple pitch. Rex Africa says it is the country’s first “AI-native” lender, built around artificial intelligence from the ground up rather than bolted on to an existing model. The company, which launched in late October 2026, offers savings, credit, payments and an AI financial agent called Rex Atlas that reads transaction history and offers conversational guidance on spending and saving.
On paper, it addresses a real gap. EFInA’s 2026 survey found that formal financial inclusion rose to 73% of Nigerian adults, yet only about 25% are financially healthy, meaning most banked Nigerians still lack real financial security. Rex is betting that intelligence, not just access, can close that gap.
But the launch materials leave basic questions unanswered. The company says it operates through Rex Microfinance Bank, yet its website shows no CBN licence number, as one publication pointed out. Its app store listing names RexCredit Limited as provider and Rex Financial Technologies Ltd as copyright holder, and records show it began life as Savyt in 2021 with a reported seed round of about USD 370 K. The same observation notes that the app has also been live since March 2024, which makes the October launch look more like an AI-led relaunch than a new bank.
Deposit protection is another gap. NDIC covers up to NGN 2 M (~USD 1.48 K) per depositor at microfinance banks, against NGN 5 M (~USD 3.7 K) at commercial banks, so a Rex saver with a large balance is only partly insured. Atlas also advises on borrowing while Rex sells loans through RexFlex, a tension the company has not addressed. And the site carries no privacy policy or terms, leaving unclear how Atlas uses customer data or whether it trains models on it.
Rex has not published customer numbers, deposits, loan books or default rates, and says only that it has attracted thousands of individuals and hundreds of businesses. It also offers investment guidance without saying what registration it holds for that, and no Nigerian rule yet sets a standard for AI that advises ordinary people on money. None of this means Rex cannot deliver. But for a firm asking customers to hand over their financial history, the burden of proof sits with the company.
Besides, Rex is entering one of Africa’s most crowded and well-capitalised retail banking markets. Fintech apps, not traditional banks, already dominate Nigerian smartphones. OPay is installed on 69% of devices surveyed by KPMG and Orange, PalmPay on 29%, Moniepoint on 14%, and Kuda on 8%. The best-performing legacy bank app, Access Bank, sits at 16%. These rivals are not standing still. Kuda has spent years building AI into advice and fraud tools, and Moniepoint processed NGN 412 T (USD 3-5.4 B) in payments in 2025.
The legacy banks are also mounting a costly counteroffensive. Nigeria’s ten largest lenders increased IT spending by 30.8% to NGN 177.91 B (USD 131.8 M) in the first quarter of 2026 alone, with Zenith Bank nearly doubling its technology budget to NGN 43.83 B (USD 32.4 M). That money is going into cloud infrastructure, cybersecurity and AI, precisely the ground Rex claims as its own.
Rex, by contrast, is a microfinance bank, not a commercial bank, operating under a different licence class with different limits. Competing with OPay’s balance sheet and Zenith’s IT budget will require far deeper pockets.
The regulatory backdrop adds another layer of execution risk. The Central Bank of Nigeria has upgraded fintech and microfinance licences to national status, raising minimum capital requirements to NGN 5 B (USD 3.7 M) for national operators. It has also set a January 2027 deadline for banks and fintechs to store payment transaction data on local servers, a costly compliance burden for smaller players. These are not minor operational details for a young microfinance bank trying to scale an AI platform.
Rex’s timing is sound because the financial health gap is real and policymakers are talking about it. But the gap between access and outcomes is exactly where fintechs and legacy banks are already fighting hardest.
Founder Yinka Odeleye says banking “should go beyond moving money to understanding customers”. That is a credible thesis. The harder question is whether a microfinance bank with limited capital can out-execute rivals that already own the customer relationship, the distribution and the technology budget. In Nigeria’s banking market, being first to a label is far easier than achieving durable scale, and it remains to be seen whether AI’s novelty alone would be enough.
OPay Seeks To Revive Terminated IPO Amid Crunch Talks To Appease China
By Staff Reporter
|
November 5, 2026
OPay, the Nigeria-focused fintech backed by SoftBank, pulled its USD 304 M New York listing hours after pricing it last week. The reason was an eleventh-hour inquiry from a Chinese regulator, despite the company having no operations or revenue in mainland China.
On the surface, the withdrawal looks like a decisive blow to one of Africa’s most anticipated tech listings. But according to Bloomberg, three people familiar with the matter say the discussions are not over. Talks between OPay and Chinese authorities are ongoing, though it remains unclear whether the regulatory concerns can be resolved. Insiders suggest the IPO is not dead, only halted and contingent on a negotiation that few outside the deal can see.
OPay is incorporated in the Cayman Islands and headquartered in Singapore. Nigeria accounted for 88.1% of its revenue in 2025. Its only link to China is founder Zhou Yahui, who also founded Kunlun Tech and was part of a consortium that acquired a stake in Opera in 2016.
Before the listing, OPay’s legal advisers concluded it did not need approval from the China Securities Regulatory Commission because it had no mainland revenue and its operating assets sat outside China. The prospectus nonetheless warned that uncertainty remained over how Beijing’s overseas listing rules could be interpreted. That uncertainty has now materialised. Chinese regulators are asserting jurisdiction over a company that, by the letter of its own filings, should fall outside their remit.
The stakes extend beyond OPay’s USD 4 B valuation. Standard Bank Group, Africa’s largest lender by assets, signed a subscription agreement to invest up to USD 200 M in OPay. Completion is explicitly tied to the IPO closing. If the offering does not complete, the subscription agreement does not proceed to closing. The halted listing therefore freezes a strategic partnership that OPay had framed as a gateway to expanding across the continent. A revival of the IPO would unlock both the public capital and the balance-sheet backing of a major African bank.
OPay’s revenue reached USD 467 M in the first half of 2026, up from USD 197 M a year earlier. Its 50 million monthly active users and dominant position in Nigeria’s digital payments market are not in question. Yet a single regulatory inquiry from a jurisdiction where the company does not operate was enough to stop the clock.
“The withdrawal should not be interpreted as a reflection of its business performance, financial condition, operational integrity or regulatory standing,” OPay said in a statement.
The ongoing talks give OPay a path back. If the matter is resolved, the listing could be repriced and relaunched, and Standard Bank’s investment could still close. If it is not, the message for other Africa-focused founders with Chinese links will be that the reach of Beijing’s regulatory perimeter is longer than their operating footprint. The outcome of the OPay IPO saga could shape how African tech assesses its exposure to forces far beyond its borders.
African Tech’s Offshore ‘Paper Parents’ Face Tough Tax Reckoning
By Henry Nzekwe
|
November 3, 2026
For a decade, the defining ritual of African venture capital has been the “flip.” A startup builds its product, hires its engineers, and finds its customers in Lagos, Nairobi, or Cairo, then incorporates a holding company in Delaware before the first institutional cheque arrives. The structure is often a compliance requirement imposed by investors who want a legal system they understand.
New data from a TLP Advisory report on 100 African tech companies shows just how lopsided this arrangement has become. The United States is the most common destination, with 67% of companies holding a US affiliation. But 81% of those US ties are incorporation and nothing else. There are no American customers, no American employees, and no American licences. The parent exists on paper.
The United Kingdom, by contrast, tells a different story. Of the 32% of companies with a UK affiliation, 47% have an operational presence and 19% hold regulatory licences. The UAE, meanwhile, is almost purely operational. Among its 23% of connected companies, 87% have people on the ground.
For years, this division of labour worked because tax authorities in home markets largely tolerated it. A Delaware parent could sell its shares and book a gain offshore, insulated from Nigerian or Kenyan capital gains tax. That tolerance is disappearing. Nigeria’s Tax Act 2025, which took effect in January, introduced an economic nexus rule. If more than half the value of an offshore holding company is derived from Nigerian assets, the sale of that company is taxable in Nigeria.
Foreign venture capitalists have warned the change could slow investment. “For founders, this means your exit valuation needs to be 20% higher just to give your investors the same net return they expected in 2024,” Segun Cole of Maasai VC toldTechCabal in February.
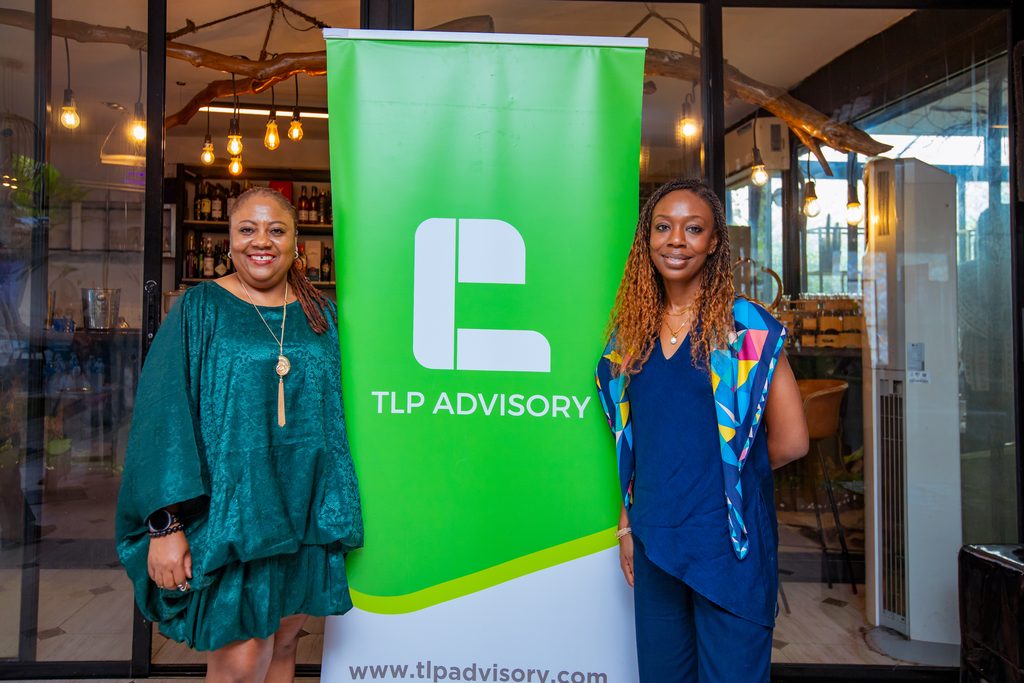
L-R: Odun Longe, Funkola Odeleye, TLP Partners Co-Founders
The shift exposes a vulnerability at the heart of the incorporation-only model. A Delaware parent with no operational substance beyond a registered agent is precisely the kind of structure the new rules are designed to reach. The UK, which already hosts more real activity per affiliated company, is less exposed to that line of attack. A London entity with a licence, a team, and a bank account is harder to dismiss as a tax artifice.
TLP Advisory, a cross-border venture law practice with its origins in Nigeria, is careful not to overstate the UK’s advantage. “A round closed in Delaware and a license in London are both important but they play very distinct roles,” said Odunoluwa Longe, co-founder of TLP Advisory. The advice from Anthony William Catt of the UK Africa Sandbox is blunter: validate before you incorporate. “In the majority of cases our recommendation is a validation step with no entity,” he said.
That logic is about to become less optional. As African governments tighten the screws on indirect transfers and profit shifting, the purely paper parent will lose its appeal. The winners will be jurisdictions that allow a company to be both legally domiciled and economically present. TLP’s findings offer some evidence that the UK, with its combination of common law, tax incentives, and regulatory infrastructure, appears better placed for that future than the US.
Africa’s Hottest IPO Sold Out Online, Giving Tech A Tough Act To Follow
By Henry Nzekwe
|
November 2, 2026
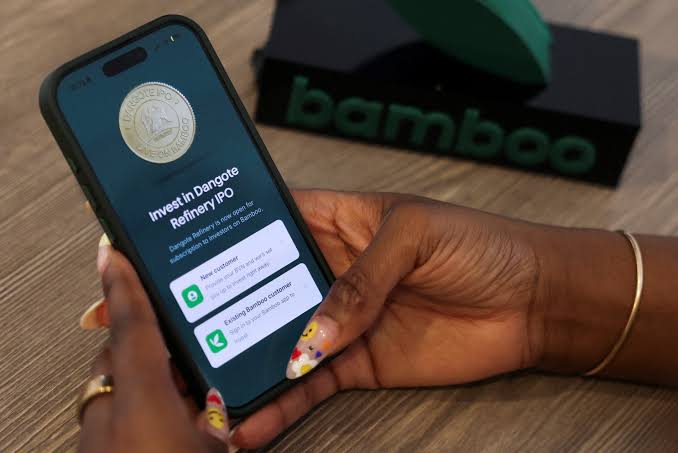
When Dangote Petroleum Refinery opened its USD 1.6 B initial public offering in September, the rush did not begin at bank branches or stockbroker offices. It began on mobile phones.
Within thirty minutes of the offer going live, traffic on Bamboo, one of Nigeria’s largest digital investment platforms, surged to ten times normal levels. The app crashed. So did Cowrywise and InvestNaija. “To be very, very honest, our system broke,” Bamboo co-founder Yanmo Omorogbe told Reuters at the time.
Six weeks later, the scale of what happened on those apps is becoming clear. Exclusive collation data first revealed by Nairametricsshows the offer drew about 1.55 million unique online retail subscribers who placed roughly 2.2 million transactions worth more than NGN 860 B (USD 560 M). Bamboo alone processed more than 600,000 transactions valued at about NGN 99 B, outpacing even legacy names like Zenith Bank, FirstBank, Chapel Hill Denham and the Nigerian Exchange’s own portal. Total retail participation, including offline and association-based purchases, could approach five million subscribers.
That is a striking number in a market where only about 600,000 of roughly six million registered Central Securities Clearing System accounts were active as of late 2025. In a single offer, Nigeria’s fintech apps appear to have onboarded more first-time retail investors than the traditional capital market had activated in years. Bamboo said more than 43% of its new users who subscribed to the IPO were first-time investors.
For Nigeria’s technology ecosystem, the temptation is to read this as a breakthrough. For a decade, venture capital has flowed into Nigerian fintech, commerce and logistics with few credible ways out. Mergers and acquisitions remain the dominant exit route, with 63 deals recorded across Africa in the first half of 2026. Nigeria has never produced a venture-capital-backed IPO. The NGX launched a dedicated Technology Board in 2022, but three years later it has yet to record a single listing. OPay, one of the country’s most valuable fintechs, just terminated a New York Stock Exchange listing amid regulatory hiccups.
The Dangote offer proves that digital distribution can mobilise retail capital at a scale the NGX has never seen, though whether tech companies can tap it is a different matter. The refinery is a mature, cash-generating industrial asset backed by Africa’s richest man and a distribution budget of at least USD 31 M, according to its prospectus. A growth-stage startup cannot replicate that machinery.
More fundamentally, many Nigerian startups are incorporated in Delaware or London, earn naira revenue but raise dollar capital, and their investors expect dollar returns. A 2025 TLP Advisory report found that 53% of founders had not considered an NGX listing because they did not understand how local listings work. A separate TLP analysis estimated that a private tech company valued at USD 100 M could be valued at only USD 60 M on the NGX.
While the Dangote IPO has widened the retail on-ramp, the exit door remains narrow. But the listing has arguably created a template for startups, regulators, and the exchange to study. The NGX has said it is courting technology companies and pushing for dual listings. But until the currency, valuation and structural gaps close, the millions of Nigerians who bought refinery shares through their phones will remain investors in refineries and banks, not in the fintech products they use every day.
OPay’s Scrapped IPO Exposes Gap Between African Fintech Hype & Public Market Reality
By Staff Reporter
|
October 31, 2026
The most anticipated African fintech listing in years ended this week not with a bell, but with a quiet thud. SoftBank-backed OPay withdrew its USD 304 M U.S. initial public offering on Friday after a regulatory inquiry in an unidentified foreign jurisdiction spooked the deal hours after it had priced.
The company, which runs one of Nigeria’s largest digital payments platforms, had sold 16 million American depositary shares at USD 19.00 each, the bottom of its marketed range, valuing it at roughly USD 4 B.
The withdrawal is the most concrete signal yet that the wave of multibillion-dollar valuations assigned to African fintechs in private markets does not always survive contact with public investors. OPay is not a failing startup. It swung from a USD 50.8 M loss in 2024 to a USD 72.5 M profit in 2025, and in the first half of 2026 revenue more than doubled to USD 467.1 M while net income nearly quadrupled to USD 90.9 M. But those numbers, impressive in isolation, carry risks that a private valuation can ignore and a public listing cannot.
The first is the source of the profit. OPay markets itself as a payments company. In reality, just over half of its first-half revenue, about USD 236 M, came from loan financing tied to a Nigerian lending book that originated USD 927.6 M of new loans in six months. It charges annualised interest of 18.3% on 30-day loans and 16.8% on 60-day loans, rates that look attractive against Nigeria’s high inflation but depend on a consumer credit cycle that has not been tested through a full downturn. OPay writes off loans after 120 days, far faster than Nigerian banks’ 360-day standard, a sign of how quickly it needs to recycle capital to sustain growth.
The second is currency. OPay earns almost all of its revenue in naira, which has been repeatedly devalued, and reports in dollars. A weaker naira can erase a U.S. investor’s return even while the local business grows. Nigeria accounted for 89.5% of first-half revenue, leaving the company exposed to a single market’s monetary and regulatory trajectory.
The third is the regulatory fog that ultimately stopped the listing. OPay said the inquiry relates to a jurisdiction it considers “immaterial” to its core operations, Reuters reported, but it did not name the regulator or describe the nature of the investigation. That silence is curious.
OPay operates in Nigeria, Indonesia, Egypt and Pakistan, and its founder, Chinese billionaire Yahui Zhou, has business interests across multiple jurisdictions. Investors were asked to accept an undisclosed regulatory risk in a company valued at USD 4 B. When the inquiry surfaced, the underwriters, including Citigroup, Deutsche Bank, Standard Bank and CICC, agreed with OPay to terminate the underwriting agreement rather than proceed.
The collapse also strands a parallel arrangement with Africa’s largest bank. Stanbic Africa Holdings, a Standard Bank subsidiary, had agreed to buy up to USD 200 M in OPay shares through a private placement contingent on the IPO closing, capped at a 4.99% post-listing stake. That investment is now in limbo, along with a proposed secondary listing on the Nigerian Exchange that was meant to give local investors access to a business that derives nearly nine-tenths of its revenue from Nigeria.
OPay’s withdrawal signals the mismatch between the private valuation of African fintechs and the disclosure, governance and currency risks that public investors price. Airtel Money managed to list in London earlier this month at a USD 7 B valuation, but it did so as a subsidiary of a FTSE 100 company with a long regulatory track record. OPay has no such cover. Until it, and the investors who valued it at $4 billion, can name the jurisdiction that stopped the deal, the valuation remains a number on a prospectus.
OPay’s Lending Business Has Quietly Overtaken Its Payments Empire As IPO Nears
By Henry Nzekwe
|
October 13, 2026
OPay has established its place as Nigeria’s ubiquitous payments app for a good few years now. Its green logo is plastered on the walls of roadside kiosks and the phone screens of millions, with the simple pitch of moving money faster than a bank. But the company’s newly filed IPO prospectus reveals a more consequential transformation. Lending, not payments, is now the engine driving its revenue.
In 2024, transaction-based services accounted for 39% of revenue while lending contributed 35%. By the first half of 2026, that hierarchy had flipped. Loan financing alone generated USD 236.1 M, or 50.6% of total revenue, according to the F-1 filing. Payments revenue fell to 28%. The company originated USD 927.6 M in new loans in Nigeria during the first six months of 2026, roughly three times the amount from a year earlier.
The scale of OPay’s lending machine is such that it now has 6.7 million unique quarterly borrowers, more than seven times the number it had in early 2024. Its non-performing loan ratio stood at 4.3% as of June 30, 2026, down from 4.8% a year earlier.
That improvement is down to the company quietly shifting its credit mix away from riskier consumer loans toward merchant lending. In the first half of 2026, the fintech unicorn disbursed USD 99.0 M in merchant loans across 20,000 transactions, generating USD 8.8 M in revenue. The company said it “tightened risk appetite in consumer loans” and shifted toward merchant loans, which carry a lower risk profile, according to the filing.
Consumer lending in Nigeria is politically sensitive and operationally fragile. Borrowers are often informally employed, repayment discipline is uneven, and regulators are watching. Merchant lending is different. OPay can observe a business’s daily transaction flows through its POS terminals and wallet accounts, giving it real-time visibility into cash flow and a natural collection mechanism.
OPay is also quietly rolling out a buy-now-pay-later product. Its BNPL offering allows active users to access short-term credit for everyday purchases with a two-week billing cycle and a one-week repayment window. For now, the product is small. In the first half of 2026, BNPL transaction volume was just USD 5.0 M across 13.4 million transactions. But the company is clearly testing whether the same infrastructure that powers its lending business can support a consumer credit product that feels more like a payment than a loan.
The timing of this lending pivot is not coincidental. OPay filed for a New York Stock Exchange listing under the ticker OPAY, seeking a valuation that reports suggest could reach USD 4 B. Standard Bank Group’s subsidiary has agreed to invest up to USD 200 M through a concurrent private placement, a signal that institutional capital sees value in OPay’s lending economics.
But the filing also exposes the tension at the heart of the model. OPay’s provision for expected credit losses surged to USD 118.4 M in the first half of 2026 from USD 38.1 M a year earlier. The company is lending more, and it is setting aside more to cover the risk of default. Whether merchant lending genuinely lowers that risk or simply delays it remains the central question for investors. One of its main rivals did run into problems with a startup it had lent a sizeable sum to, for instance.
OPay is betting that the same data advantage that made it a payments giant can make it a lending giant too. The prospectus suggests that bet is already paying off. The risk is that in emerging markets, credit cycles can turn faster than payment networks can adapt.
Tech Giants’ Retreat From Africa Continues As Microsoft Guts Kenyan Engineering Hub
By Staff Reporter
|
October 13, 2026
Microsoft has told staff at its Africa Development Centre in Nairobi that the engineering hub will close, ending a seven-year, USD 100 M bet on building global products from Africa and putting nearly 400 jobs at risk.
The decision, communicated to employees on Monday, marks the second retreat from a dedicated engineering presence on the continent after Microsoft shut its Lagos ADC in 2024. Coming just months after a USD 1 B data centre project with Abu Dhabi’s G42 stalled over payment guarantees, the closure signals a broader recalibration of how US tech giants engage with Africa.
The pattern extends beyond Microsoft. X, formerly Twitter, briefly opened an office in Accra, Ghana, in November 2022, then laid off nearly all of its roughly 20 employees just four days later. Former staff said they were “ghosted” without severance pay for more than seven months, and the company reached a settlement only after about a year of negotiations. Kenya has since given X three months to open a physical office in Nairobi, a demand that remains unmet.
Oracle has taken a different path. The company has not closed its Nairobi office but has cut roughly 21,000 jobs globally, about 13% of its workforce, as it redirects capital toward AI and cloud infrastructure. Oracle’s Nairobi operation, which serves as a hub for East African cloud and AI sales, has not been immune.
The company has not disclosed how many Kenyan staff were affected, but termination emails sent in September 2026 gave employees same-day notice, with severance capped at 26 weeks of base salary. Oracle has simultaneously been advertising roles in Kenya for data centre technicians and AI infrastructure sales, a signal that the cuts are a reallocation rather than a full retreat.
Ride-hailing giant Uber has also pulled back sharply from Africa. The ride-hailing giant shut down operations in Nigeria and Uganda in September, capping a year in which it exited four African markets in roughly twelve months, having earlier withdrawn from Tanzania in January 2026 and Côte d’Ivoire in September 2025. Meanwhile, Meta’s termination of a content moderation contract triggered 1,108 job cuts at Sama’s Nairobi hub in April.
The combined effect is a continent increasingly treated as a market for consumption rather than a site for production. The depth of Western involvement raises questions about whose priorities shape Africa’s digital future.
***
Microsoft’s cash spending on property and equipment, mostly data centres, rose from USD 23.9 B in FY2022 to USD 115.9 B in FY2026. Its workforce, meanwhile, fell by 5,000 to 223,000. Capital is flowing into compute infrastructure, not engineering headcount. The Nairobi ADC, whose teams built global products rather than Africa-specific ones, was exposed. Its work could be done from Redmond or Hyderabad. Median entry-level pay for a Microsoft engineer in Kenya stood at roughly USD 52 K a year, against USD 30 K in Bengaluru.
Kenya’s ICT Cabinet Secretary William Kabogo met a Microsoft delegation on Monday and said he “stressed the importance of retaining local talent, protecting jobs at Microsoft’s Nairobi engineering centre and sustaining investor confidence.” The government and Microsoft agreed to develop a joint action plan covering AI adoption, digital government services and cybersecurity.
For Kenya, the closure undercuts a decade-long effort to position itself as a regional technology hub. It follows the stalled Olkaria data centre, which was to be anchored by a geothermal-powered facility and mentored by ADC engineers. Talks broke down in May over Kenya’s reluctance to commit to fixed annual capacity payments.
Africa accounts for 18% of the world’s population but holds less than 1% of global data centre capacity. The continent’s four largest tech economies have each drafted AI strategies acknowledging dependence on US infrastructure as a security concern.
The Nairobi ADC was launched in May 2019 with a pledge of 500 engineers by 2023. By December 2022 it reported more than 500 engineers in Nairobi. Employees were asked to meet with managers by Friday to discuss exit options, including severance terms. Microsoft has not disclosed the timeline for the wind-down or whether Microsoft Research Africa and the Microsoft Garage, both housed at the ADC’s Dunhill Towers office, are included.