‘Made In Africa’- This Engineer’s Invention Is Mending ‘Broken Hearts’ In Cameroon And Beyond

By Henry Nzekwe  |  December 29, 2018

Marc Arthur Zang was fresh out of grad school when he pulled off something of an unlikely feat. The then 24-year-old who had just completed a Masters Degree Program at the National Advanced School of Engineering, Yaounde, created a ripple when he single-handedly put together a working cardiological device. And this was designed from his only form of instructional aid – random information resources he got off the internet.

Now 29, the young Cameroonian ‘techpreneur’ is credited with the invention of a device that is considered the very first ‘Made-in-Africa’ medical tablet. And when he first rolled out this invention over six years ago, he got ‘tech birds’ both home and abroad chirping nonstop for months.

Zang aptly called his creation ‘Cardiopad’. He specifically tailored the device for the needs of healthcare workers in rural areas who are faced with an enormous challenge when it comes to performing cardiac diagnosis in those places due to the lack of adequate equipment. Cardiopad provides healthcare personnel in conventional communities with the means to perform cardiac tests and send results to cardio specialists via mobile devices.

For a country like Cameroon occupied by nearly 25 million inhabitants, it makes for gloomy reading that the state can only lay claim to a handful qualified and capable heart surgeons.

And the only thing more disturbing than the apparent scarcity of heart specialists in the country is that most of the few available are concentrated in Yaounde and Douala; the country’s two major cities.

This puts people living in the country’s rural communities in a dire situation as they are unable to access prompt response for something as troubling as heart conditions. Due to the severe deficit of specialists in the cardiology field, many locals with various heart ailments are forced to make long trips to avail themselves of heart examinations and consultations. More often than not, the exertions of such arduous journeys are known to even exacerbate the situation by aggravating the ailment.

More so, because of the shortage of capable hands, many of these patients have to join a long waiting list to get proper diagnosis and treatment for heart ailments of varying degrees, even when they make appointments months in advance. Disturbingly, a number of those patients never make it to the examination room as they are unfortunately struck down by the ailment before it gets around to their turn. In addition to losing an uncle to a stroke, putting an end to some of these problems can be thought to have spurred Zang on towards bringing his idea to life.
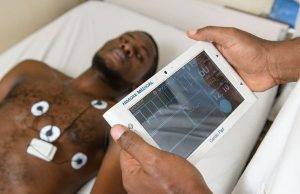
How The Cardiopad Works
Image Source: RisingAfrica

Zang’s Cardiopad is a touch-sensitive medical tablet that allows for heart examinations such as electrocardiogram (ECG) to be carried out in remote, rural locations. And if you think that’s all the device does, think again.

Cardiopad also functions to wirelessly transmit test results to specialists who possess the skills to interpret the variables obtained from the test and recommend treatments. For people living in rural Cameroon, Zang’s creation would come as a breath of fresh air as gone are those days of having to cover several miles to get to urban centers in the name of seeking a medical examination.

As culled from Radio Netherlands which created the earliest buzz on Arthur Zang’s Cardiopad, the young Cameroonian inventor described his invention as the “first fully touch-screen medical tablet made in Cameroon and Africa.” He also expressed the belief that his creation could help save numerous lives while hinting at the accuracy of the device holding steady at an impressive 97.5 percent.

Zang enthused that Cardiopad was borne out of the need to facilitate the treatment of patients with heart diseases across parts of Cameroon and Africa. Since becoming public, the device is known to have proven its mettle in carrying out several cardiac tests with satisfactory results as validated by the Cameroonian scientific community.

And this has only seen Zang’s invention gain even more acceptance as Cardiopad sees use in a number of rural communities including Mbankono; a small village located some 25 kilometers away from Yaounde, the Cameroonian capital.

When he spoke about his creation back in 2014, Zang let his interviewers in on the inspiration behind his invention. From his words in that interview, it could value that Zang was troubled by the dearth of capable hands in the area of cardiology in Cameroon – he even cited figures which suggested that there were less than 50 cardiologists in the country at the time; a poor figure considering the country’s population was somewhere around 20 million.

Zang also revealed that he was well aware of the difficulties associated with getting heart examinations for people living outside Yaounde or Douala as the limited number of heart experts were all holed up in both cities.

According to him, for this set of people, getting the needed medical attention was an expensive and time-consuming ordeal, and follow-ups were even more difficult.

In an effort to help lighten the burden, Zang patented his brainchild – Cardiopad, which comes complete with a full diagnostic kit. With this device, health workers located in rural locations and who are not prototyping skilled specialists in cardiology, are enabled to perform cardiac examinations on patients.

After the examinations, the health personnel could also use the device to send the test results to heart specialists in various parts of Cameroon for diagnosis and recommendation. His creation mainly puts paid to the concerns of many patients with heart ailments who would be otherwise inconvenienced by frequent trips to Yaounde or Douala.
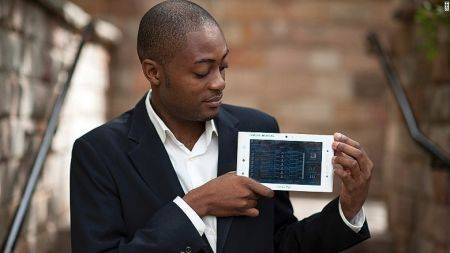
Arthur Zang Holding A Cardiopad
Image Source: CNN

Complete with a diagnostic kit, Cardiopad is something of a miniature EKG, or perhaps even better than the regular device given that is portable and very accurate. And it works in a rather straightforward fashion.

It all begins with attaching a wire set of four electrodes and a sensor to the patient. Then, a signal is transmitted via Bluetooth to the Cardiopad. This signal is essentially a digitized ECG reading of the heart function of the patient. What then follows is the transmission of the information gotten from the procedure to a national data center.


It is through that data center that qualified cardiologists working from health centers in urban areas can receive the ECG, make a diagnosis, and revert to the health worker with appropriate recommendations and prescription instructions. Cardiopad is also furnished with a built-in software which allows the doctor to give a computer-assisted diagnosis.

Zang’s Cardiopad is an original creation, and it makes it possible for doctors to make an accurate diagnosis of patients without necessarily coming in contact with them. And for the patients, it comes as a plus that they no longer have to worry about traveling long distances to get medical attention.

Although each unit of the Cardiopad costs a rather steep USD 1 K to manufacture, it could cost significantly less if some of the electronic components can be sourced locally. Zang currently sources most of the electronic components from China before putting the product together in Cameroon. And this somewhat places a burden on the pricing as electronic components designed for the medical field are known to be quite expensive. Hence, the device current sales price of USD 4 K.

In any case, the Cameroonian entrepreneur is quite optimistic about the prospect of having the product entirely manufactured locally in the future. Once possible, Zang sees the device being put out on sale for around USD 3 K by his company, Himore Medical. And if that figure still made you wince, squirm, or shudder, perhaps it might help to note that similar, yet less portable systems, currently cost nearly triple that amount. Compared to all other devices that perform the same function, Cardiopad can be thought of as a very portable and low-cost alternative.
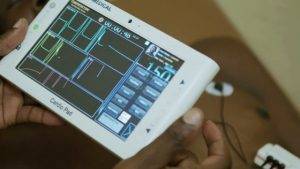
The Cardiopad, Image Source: vimeo.com

What started as a whiff of an idea has now been brought to life by a stroke of genius. Having obtained a bachelor’s degree in computer science from the University of Yaounde in 2007, Zang’s insatiable test for knowledge led him to enroll for a Masters Degree program two years later. And it was during this period that he had his own ‘lightbulb moment.’

In 2009, Zang had just completed his postgraduate course and was keen on applying his knowledge of engineering to the development of solutions in the medical sphere. In his quest to identify which areas a computer engineering application could do a solid to the field of medicine, he began to pick the brains of medical experts both formally and informally.

It was on one of such discussions with a cardiologist who pointed out the challenges that hamper people living in rural areas from getting required cardiac examinations that Zang got his interest piqued. From that moment, he set out to work on a solution.

The young engineer sought out possible solutions to the problems until he stumbled upon what seems to have checked all the boxes. He opted to put together a portable medical solution. But being only a computer scientist with very little by way of medical electronics know-how, he always had his work cut out for him with regards to brushing up on his knowledge.

How he went about that, though, was unconventional and somewhat audacious. As there weren’t many engineering schools where one can learn medical electronics and biomedical engineering in his home country, Zang made the internet his tutor. Essentially, he designed the Cardiopad by teaching himself medical electronics with online resources.

For up to six months, he watched clips and consumed texts on the subject that he had gotten off the internet. Soon, he was beginning to get the hang of it despite how daunting a challenge it seemed initially. Now armed with the required knowledge, Zang came up with a good design for the Cardiopad. His faith in the internet as a useful learning tool appeared to have paid off.

And then came the next hurdle: finding funding for the prototype. This proved quite the stumbling block as banks are not known to jump at the idea of giving out cash on loan to a student without guarantees. So he turned to family and friends.

The mother of the Cameroonian inventor was able to procure a loan worth USD 1.3 K from a bank, and it was with these funds that Zang financed the prototype of the Cardiopad. After building the initial prototype, he took to social media platforms like Facebook to promote his invention, and this helped him raise further funding.


Cameroonian President, Paul Biya, offered the young techie a grant worth USD 30 K to fund the project and with the new injection of capital, Zang manufactured the first 20 devices. After that, he made another video demonstration of the product and submitted it as an entry for an international innovation competition known as the Rolex Awards For Enterprise. And his stock has only risen since then.
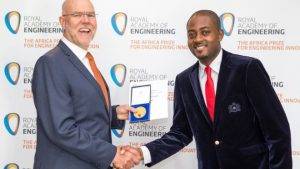
Arthur Zang Receiving His Prize At The Event In Dar Es Salaam
Image Source: BBC

Rolex named Zang amongst four others selected from various parts of the globe as its Young Laureates for 2014. In 2015, he was the recipient of an award in the Applied Technology category. In the year that followed, Zang won a USD 37 K cash prize for his invention having clinched the Africa Prize for Engineering Innovation organized by the UK’s Royal Academy of Engineering at a ceremony in the Tanzanian city of Dar es Salaam.

Additionally, with his new-found fame and acclaim, Zang has also been able to garner up to USD 55 K in funding for the production of 100 medical tablets, with each of Cameroon’s 10 provinces expected to be served by 10 of his devices. The device is also known to have gone on sale in some other countries including Gabon, India, and Nepal.

Going forward, Zang’s Himore Medical has its sights trained on manufacturing a number of other medical devices, including a piece of ultrasound equipment that will be designed for medical examinations in economically-disadvantaged locales.

Arthur Zang’s journey thus far can serve as a lesson to Africa’s teeming entrepreneurial population to make good use of whatever is available to them in trying to come up with solutions to some of the continent’s problems. It also stresses the need to break from the conventional both in approach and thinking.
Trapped Customer Funds At Raven Expose The Ugly Side Of Nigeria’s Fintech Boom

By Staff Reporter  |  November 16, 2026

A single customer complaint has cracked open a wider problem in Nigeria’s digital banking sector. More than NGN 17 M (USD 12.6 K) belonging to a Raven user known on X as Legacy remains stuck after he tried to liquidate a fixed deposit. The platform first returned a message saying “Transfer failed, please try again later,” then cited maintenance for months, and eventually showed a zero spendable balance while still displaying the funds.

Legacy says he put his money into Raven after a public endorsement by Chinonso Egemba, the health influencer widely known as Aproko Doctor, who served as the company’s brand ambassador. That detail has turned a liquidity failure into a public argument about who carries responsibility when a fintech app stops working as advertised.

Raven’s chief executive, Uchenna Nnodim, has told customers that the disruption followed the withdrawal of a banking partner’s operating licence. A portion of customer funds sat with that partner, which cut Raven’s liquidity and its ability to process withdrawals. The partner was Beststar Microfinance Bank, identified in Raven’s own app listing, and its licence was among 46 revoked by the Central Bank of Nigeria effective July 1, 2026.

The company says it is pursuing two recovery paths. It is engaging regulators to recover funds held with the former partner and raising fresh capital to settle customer obligations. It has also split balances on its app so that old funds remain visible but restricted while new deposits sit under a separate “Usable Balance”. Nnodim has said more than 650,000 customers have regained access, but Raven has not disclosed how much money remains trapped, set a repayment date, or provided an aggregate figure for restricted funds.

Aproko Doctor says his ambassadorship ended in 2024 and that he is not an owner, shareholder, employee or representative of Raven. In a statement pinned on X, he said his recommendations reflected his own experience at the time. “When I recommend a product, I am giving my honest view of it at the time I recommend it,” he wrote. “That recommendation cannot guarantee how a company will behave years later. And it does not make me responsible for a business I do not run.” He urged affected customers to file written complaints with Raven and escalate unresolved cases to the CBN’s Consumer Protection Department.

Activist Martins Vincent Otse, known as Verydarkman, rejected that position and pointed to a 2025 post in which Aproko Doctor appeared to promote Raven, contradicting the claim that the deal ended in 2024. “Meaning you are lying,” Verydarkman said in an Instagram video. Legacy has since told Verydarkman that Raven released his money in instalments after the complaint gained traction, but other customers remain locked out.

Separately, the Economic and Financial Crimes Commission has charged a man over an alleged NGN 700 M (~USD 520 K) fraud involving the bypass of two-factor authentication on Ravenpay user accounts between March 2025 and January 2026. The case has no direct link to the liquidity crisis, but it adds to questions about operational controls at a platform that marketed itself as a safe home for savings.

Raven, on its part, has committed to publishing a formal progress update every two weeks on its recovery process and the steps being taken to settle outstanding customer balances. “We will also keep engaging affected customers directly and giving them honest, accurate information about their own cases,” it said in a statement issued today.

As it stands, the CBN’s consumer protection department is the only body with the power to compel a resolution, and for thousands of Raven customers, that inbox is now the last available recourse.

Africa’s AI Startups Face A Cost Trap As Expenses Dwarf Earnings

By Staff Reporter  |  November 13, 2026

African artificial intelligence businesses have attracted USD 1.3 B in disclosed funding over the past decade, but a new industry survey suggests the capital is colliding with a hard economic truth. Building and selling AI in Africa remains a structurally expensive proposition, and the gap between global input costs and local purchasing power is threatening the sector’s next stage of growth.

The report, “AI Made in Africa: Voices from AI businesses across Africa“, published by German development agency GIZ and data firm Briter, mapped 311 AI ventures across the continent. The headline funding figure masks a far leaner reality. The median funding ticket is just USD 225 K, roughly a third of the companies remain entirely bootstrapped, and only 15% are profitable. More than 75% of all capital raised has gone to businesses founded before 2020, leaving newer AI-native startups to operate in a funding environment shaped by an older generation of raises.

The core problem is a price mismatch that runs through every layer of the business. For 65% of surveyed companies, cloud computing, GPUs and AI infrastructure are their largest development expense, and those bills are denominated in US dollars at rates comparable to markets in Europe or the United States. Yet more than half of these businesses price their products below USD 2.5 K a year per customer, roughly USD 208.00 a month. That is a sum that, for many small African enterprises, competes directly with internet access, generator fuel or staff salaries.

The infrastructure deficit behind those costs also poses a headache. Africa holds less than 1% of global data-centre capacity while hosting about 18% of the world’s population, meaning most AI computation for African companies runs on foreign servers.

Moreover, currency shocks amplify the squeeze. The 2023 naira devaluation reportedly drove local cloud bills up by 224% for some Nigerian users, and founders now describe devaluation as a permanent operating risk rather than an exceptional event. A company serving thousands of daily users can spend USD 20 K to USD 50 K a month on third-party AI APIs alone, costs that scale with success rather than flattening out.

Selling into this environment carries its own costs. The survey found that 65% of businesses identify customer trust and AI literacy as their top scaling barrier, ahead of development costs. Many global models perform poorly on African data because they were trained on foreign datasets, forcing companies to spend time and resources demonstrating reliability to sceptical buyers. Government sales, which 44% of the companies pursue, can take 12 to 18 months to close, stretching cash flow for startups that need regular revenue to survive.

The talent market adds another expense. Africa accounts for roughly 1% of the global AI talent pool, and 51% of surveyed founders say senior AI research roles are the hardest to fill. Nearly half have responded by building internal training pipelines, effectively becoming educators as well as technology companies.

The businesses are not asking for sympathy, the report notes, but for patient capital that understands the operating environment, and for public interventions that lower input costs rather than simply celebrating the sector’s growth. Whether that capital and those policies arrive will determine if Africa’s AI economy can move from a promising experiment to a sustainable industry.

Image Credits: AfDB

Newcomers Are Tinkering With New Models To Replace Uber In Nigeria

By Henry Nzekwe  |  November 12, 2026

The scramble to replace Uber in Nigeria is being fought over who absorbs the cost of a trip, and the new entrants are making bets that Uber itself could not sustain.

Uber ended operations in Nigeria on September 2 after twelve years, leaving behind a market worth about USD 450 M in 2025 and projected by Ken Research to reach USD 982 M by 2032. Bolt and inDrive moved quickly to absorb riders and drivers, but a cluster of newer and local players is now testing structurally different models. Loop, FastDrive, SimpliRide and Shuttlers are shaping up as not merely cheaper versions of Uber but experiments in who pays when the fare does not cover the journey.

The most aggressive of these is Loop, which launched in Port Harcourt and Delta State in October and says drivers keep 100% of their fares, paying the platform through a subscription rather than a per-trip commission. FastDrive, founded by Okechukwu Mathew and launched publicly on October 15, takes a related route. Drivers set their own per-kilometre price within limits, pay no percentage commission, and owe a flat NGN 1 K (about 74 cents) daily fee after their first two rides.

On a strong day, the appeal is straightforward. A driver on a 25% commission who grosses NGN 40 K (~USD 30.00) hands over NGN 10 K (USD 7.43). On FastDrive, the same driver pays less than a dollar, provided the rides arrive. But the risk has not disappeared. Under a commission model, the platform earns less when the driver earns less. Under a subscription or a daily fee, the driver owes the platform whether the day is good or bad. A fuel queue, a police checkpoint, a breakdown, a slow Monday, and the fixed cost is still due. The model that looks most driver-friendly on a busy day can be the least forgiving on a quiet one.

inDrive’s recent move is the clearest admission that pure negotiation has a ceiling. The company built its Nigerian business on letting riders name a fare and drivers accept, reject or counter, charging a service fee of about 10%. It insists the bidding model is intact.

“Our model is the same. We didn’t change overnight. We just introduced the One Click option, which lets you skip bidding if you are in a hurry,” the company says. But One Click removes the negotiation and lets inDrive set the price. Fares on One Click run roughly 40% to 50% higher than the recommended fares on the basic ride category, an observation of the app reflects, though the option may be a way to help drivers earn more without leaving them to riders who bid below acceptable levels.

***

Shuttlers is not competing inside that same on-demand frame. The company has run scheduled shared buses in Lagos, Abuja and Port Harcourt since 2016, completing more than 10 million journeys and operating over 430 buses daily. In September, shortly after Uber’s exit, it launched Shuttlers Pod, a door-to-door car service that carries three to four commuters who book in advance and share the vehicle, with a fixed fare and no surge pricing or roadside negotiation.

Pod trips cost roughly 50% less than typical ride-hailing fares, enabled by advance booking and shared occupancy. “Nigeria’s cost of living is rising faster than incomes,” chief executive Damilola Olokesusi said at the launch. “With that reality, the smartest way to move people is through shared mobility”.

The challenge these entrants are trying to surmount is the one that broke Uber. A report by Obi, a California-based price and trip data aggregator, found that Uber paid drivers more than it charged passengers on trips shorter than roughly 20 kilometres, with the gap reaching 23% on journeys between 5km and 9km. Nigerian Uber drivers averaged 130 rides over the first seven months of 2026, against 1,142 for Uber drivers in South Africa, an 8.8-fold gap in per-driver volume. “Low per-driver volume plus a per-ride subsidy is a bad combination: there’s no scale to absorb the loss,” the report said.

Fuel has not helped. Petrol has risen from about NGN 830.00 a litre to roughly NGN 1.4 K, a near-70% increase in the single largest operating cost, while platform commissions on the established apps have stayed between 20% and 35%. Bolt’s Nigeria driver guide lists a 20% commission, and the Amalgamated Union of App-Based Transporters of Nigeria has demanded a 10% cap and a fare review, staging a strike in October that shut down the Bolt and inDrive apps in Lagos.

Bolt, which held the largest share of Nigeria’s market by the time Uber left, recorded a 92% week-on-week increase in Nigerian driver registrations after the exit. inDrive saw app installs surge 96%, according to local reports. But Ayoade Ibrahim, co-founder of the drivers’ union, warned that reduced competition over time could lead to less favourable terms for both riders and drivers, and that the platforms that last will be the ones that can hold a fare high enough for drivers and low enough for riders while still funding support, insurance and compliance.

That is the unresolved question at the centre of Nigeria’s ride-hailing reset. Subscriptions make drivers pay upfront while daily fees make them pay regardless. Meanwhile, One Click quietly concedes that negotiation alone underprices the work and shared scheduled rides avoid the problem by selling a different product. None of these models has yet demonstrated that it can carry the full weight of on-demand mobility at scale in a market where fuel, inflation and currency have already broken one global operator.

The Unlikely Rise Of A Sickle Cell Survivor Behind A Data Centre & Tech City In Nigeria’s Overlooked Region

By Henry Nzekwe  |  November 11, 2026

The meeting nearly ended with Ugi Augustine Ugi thrown out of the room. It was 2016, and he had come to tell the Calabar Carnival Commission that its biggest annual event was leaving money on the table. Why, he asked, did a festival that drew 100,000 people a day still depend on government funding every year? Why not merchandising, a streaming economy, commercial sponsors?

“They were not ready for that conversation,” Ugi tells WT. Nearly a decade later, his company runs the carnival’s digital registration, voting and stakeholder systems.

That persistence runs through Nugi Group, the company Ugi founded in 2016 in Calabar, a port city in Cross River State in southern Nigeria. It also explains a business that has grown by taking on problems others avoided, often in places others ignored.

Ugi was born with sickle cell anaemia. The illness shaped his first ambition. He wanted to become a doctor because he wanted to help people like himself. “Medicine made sense to me as a child because of what I was living with,” he says.

The pivot came in secondary school at the West African Peoples Institute in Calabar, where he was a laboratory prefect. In 2004, a telecoms engineer arrived to install computers. Ugi kept asking questions about the internet and how the systems worked. Those conversations opened a door that medicine could not close. He later realised he had not abandoned the original impulse. “I still wanted to solve problems and improve people’s lives,” he says. “Technology simply became the tool I chose to do it.”

By 2006 he was learning web development on a partial scholarship and working in a cybercafé. His parents, both civil servants, were not impressed. Technology, in their view, was a path to becoming a secretary, he said in a previous interview in which he also revealed that he entered a televised game show on his father’s phone, won NGN 20 K (around USD 155.00 at the time) , and used his share to pay for a programming course. He never collected the certificate after a dispute over e-books, but he kept the knowledge.

***

Nugi nearly did not survive its early years. The company grew to 23 employees, then shrank to five as clients paid late and deals collapsed. “The most dangerous thing an early-stage company can do is grow its headcount before it’s grown its revenue discipline,” Ugi tells WT.

The near-death experience hardened the company. Every hire, product and partnership, he emphasised, had to justify itself. There were other low points, including a major health setback that forced him to pause almost everything. He wrote about that period in a memoir, Blood of the Phoenix.

What Nugi built instead was a business anchored in government contracts, an unusual path for a Nigerian tech company seeking scale. It took on revenue administration, land management and citizen services for Cross River State.

The founder says its systems helped the state grow internally generated revenue, the taxes and fees the state collects itself rather than federal handouts, by 60.6% to NGN 36.3 B between June 2023 and May 2024. By December 2024 the figure had reached NGN 46 B. More than 7,500 land files have been digitised, and certificate-of-occupancy processing has been cut to 21 days for government land.

The numbers are looking up, though the causal chain is harder to verify. Revenue can rise because software closes leakages. It can also rise because enforcement tightens, tax rates change, or inflation pushes nominal receipts up. Nugi’s biggest client is also its biggest concentration risk given that state budgets tend to move with oil receipts and political priorities. A change of governor can change a vendor’s fortunes overnight.

Ugi is aware of the scepticism. He points to Cally Air, the state-owned airline, as an example of what he means by government needing expertise rather than cash. “Five aircraft, no naira of government funding, yet flying on goodwill to build a sustainable, independent business model,” he says.

Cally Air is owned by the Cross River State government, and the state procured its fleet. Ugi says the government gave goodwill, introductions and access to partners, while Nugi brought the engineering and commercial structure. He notes that the distinction between government money and government goodwill is a fine one, and it defines both the risk and the opportunity of his business model.

***

Nugi did not raise venture capital. Ugi says it was both a constraint and a choice. “We were based in Calabar, building technology for government and businesses. We were not a consumer startup chasing millions of users, so the funding ecosystem was not really designed for us,” he says, while also implying that the constraint became a discipline. “You cannot spend 18 months figuring out whether something works while burning someone else’s money.”

In 2024, he turned Nugi Tech into Nugi Group, adding education, agriculture, media, infrastructure and real estate. The thesis, he says, is overlooked talent and overlooked opportunities. He points to Terra Grid, a surveying and mapping business built around a brilliant, young surveyor he met in Calabar, at a time when the World Bank valued Nigeria’s land systems at more than USD 300 B. “People look at technology, agriculture, construction, media and real estate and see diversification,” he says. “I see the different parts of an ecosystem.”

The ecosystem is anchored by a plan for a technology city in Akpabuyo, 23 minutes from Calabar airport, with a Tier IV data centre at its core. Tier IV certification means 99.99% uptime, the kind of reliability banks and cloud providers need to host critical systems locally. Nugi says the facility will draw power from a nearby hydro turbine, an 80-megawatt solar farm, Cross River’s gas reserves and the national grid as backup. It is also exploring a subsea cable landing in Akpabuyo.

The gap between software contracts and capital-intensive infrastructure is vast. A data centre of that specification demands financing, engineering talent and power reliability at a scale Nugi has never operated. Ugi says the wider city is a nine-year project. “Lagos already had many people solving Lagos problems,” he says. “Cross River had gaps that needed people willing to build.”

At 40, he frames success in terms of legacy rather than achievement. “I want to create opportunities for other people,” he says. “I was once a young boy in Calabar trying to figure out what was possible. If what we build makes that path easier for the next person, that means more to me now than simply building another company.” The harder question is whether the path Nugi is building can outlast the political goodwill that helped clear it.

M-Pesa’s Dominance and Kenya’s digital payments landscape

By Ray Munene  |  November 10, 2026

Around the world Kenya is largely known as the home of innovations in digital payments.

This is mainly due to Safaricom’s flagship offering, M-Pesa. Since its launch in 2007, M-Pesa has allowed more Kenyans to swiftly send and receive money through the convenience of their mobile phones. In March 2026, exactly 19 years after M-Pesa’s launch, Safaricom announced that the mobile money platform had hit the milestone of 40 million customers.

In a research paper on mobile money payments, the World Bank described the service as follows: “M-PESA’s original core offering was the P2P payment – enabling customers to send money to anyone with access to a mobile phone. It opened up a market for transactions which previously were handled largely informally – through personal trips, friends, and public transport networks.”

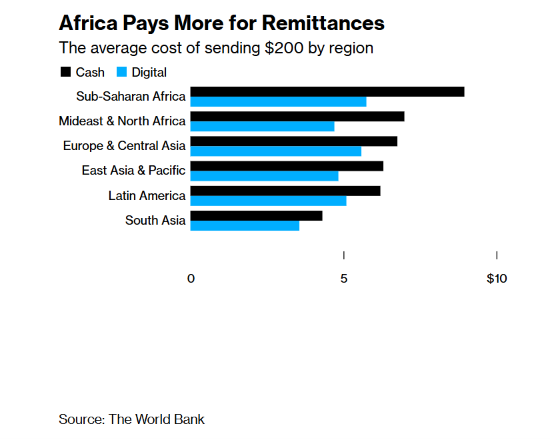
Africa still remains the region with the highest fees for sending money.

Source: The World Bank / Bloomberg

Just as M-Pesa has transformed the financial landscape in Kenya, it is also an expensive product from a consumer point of view. This has led to increased competition from banks, neobanks and fintechs. The banking sector, through various Kenyan Banks has tried to curb M-Pesa’s market dominance through various offerings. I&M Bank removed all charges for bank-to-mobile-wallet transfers. Loop DFS has been hailed for maintaining free transfers before it was rebranded by NCBA and the charges were reintroduced.

In 2009, TEAMS (The East African Marine System), connecting Mombasa with Fujairah, greatly reduced the cost of internet access. This opened up access to the digital space, and this transition saw the financial needs of the population expand from simple P2P payments to digital commerce, BNPL solutions, stock market trading, overseas money transfers and offshore investments. Safaricom itself has also noted the growing needs and has developed new products. In a statement, Safaricom noted “investment and wealth management through Ziidi MMF, Ziidi Trader, credit services like Fuliza and KCB M-PESA.” . It continued to state, “business solutions such as Lipa na M-PESA, Pochi la Biashara and Global Pay.”

Indecisive government action:

In July 2022, the Asset Recovery Agency sought court orders prohibiting Flutterwave from doing business in Kenya. In March 2021, following a US$170 million Series C funding round, Flutterwave officially became a unicorn, surpassing the billion-dollar mark. Iyinoluwa Aboyeji, Adeleke Adekoya and Olugbenga Agboola founded the company in 2016. Flutterwave’s mission was to become a payment gateway that would revolutionise the speed of transactions within Africa. The Asset Recovery Agency claimed that Flutterwave had breached the country’s anti-money laundering laws. The firm’s funds in Kenya, amounting to $43 million, were frozen.

ARA dropped the charges after a couple of months, coinciding with a new government taking over just a few months earlier. Flutterwave CEO Olugbenga Agboola later made a public plea for a renewed licence, promising to expand the company’s footprint in Kenya.

In addition to this, the Central Bank of Kenya issued a directive pausing banks from doing business with Flutterwave and Chippercash. The CBK directed banks not to deal with the two entities due to a lack of proper licensing. The directive read in part: “It has come to the attention of the Central Bank of Kenya (CBK) that Flutterwave Payments Technology Ltd and Chipper Technologies Ltd have been engaging in the money remittance business without licensing and authorisation by CBK.”

Market entrants:

Newer players have recently pivoted to digital currencies and stablecoins, thereby avoiding regulations by central banks and oversight authorities. Kenya’s President assented to the Virtual Asset Service Provider Bill, and it officially became law on 4th November 2025. The law placed numerous requirements on companies planning to venture into the space. Under the requirements that took effect from November 2026, a stablecoin issuer needs a minimum capital of ksh 300 million. A virtual wallet provider needs a minimum capital of ksh 150 million. This sets a precedent as the first of its kind in East Africa.

Kenya’s bank-to-bank solution:

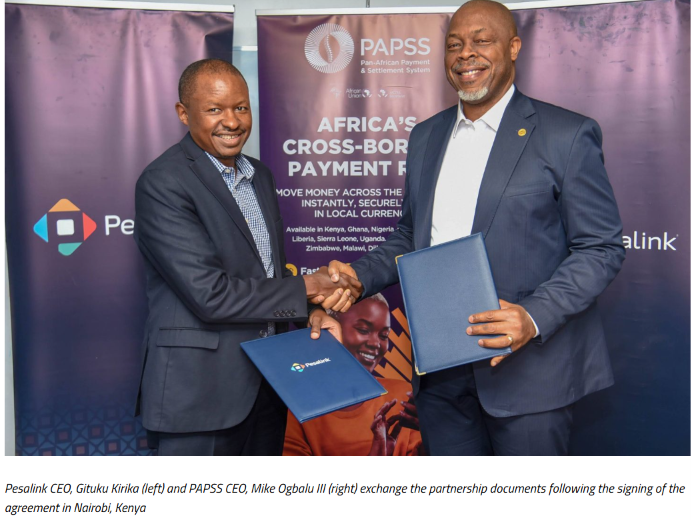
The Kenya Bankers Association (KBA) through its subsidiary, Integrated Payment Services Limited owns PesaLink, an instant payment network . The instant payment service recently announced a partnership with the Pan-African Payment and Settlement System (PAPSS). The partnership aims to “ease cross-border payments and speed up regional financial integration.”

courtesy Afrexim Bank

PesaLink has been acknowledged at home as having lower rates than Safaricom’s M-Pesa. The bank-to-bank system also enjoys the support of Kenya’s banks, as the nation’s major banks are connected via PesaLink.

Kenya’s financial landscape is constantly evolving and M-Pesa’s relevance is slowly being eroded thanks to cheaper digital solutions in the market. What sets M-Pesa apart is it’s domination of mobile money payments, In contrast, the battle for instant account transfers is being led by PesaLink.

The AI Bank Promising To Fix Nigeria’s Money Problems Has A Lot To Prove

By Staff Reporter  |  November 9, 2026

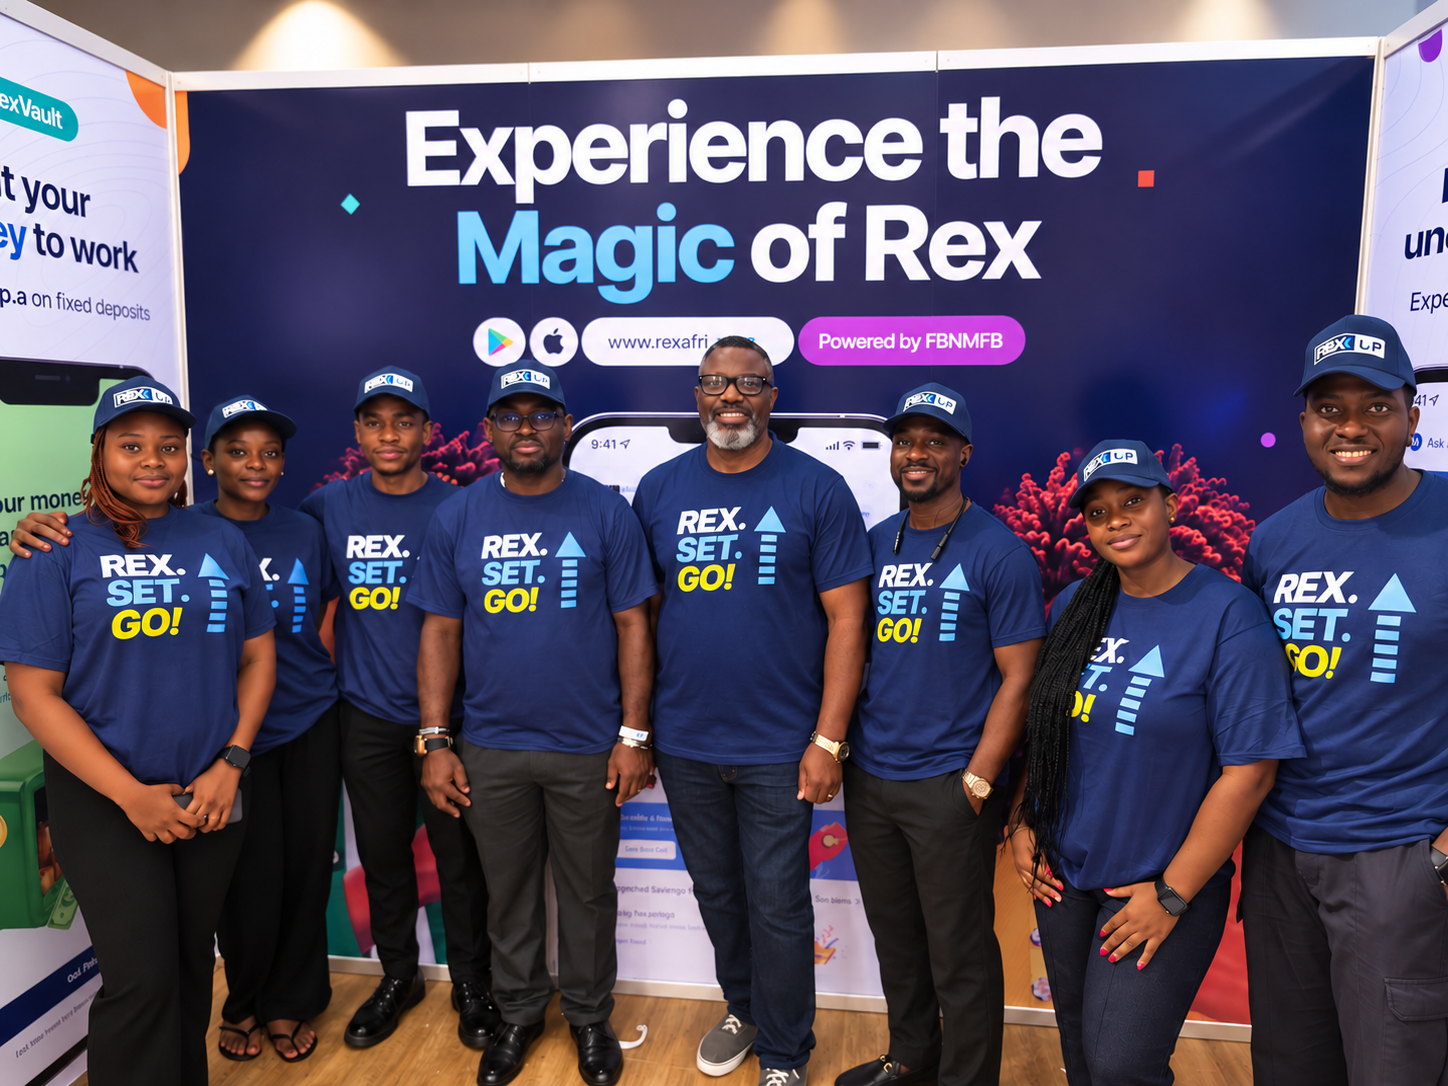
Nigeria’s newest bank has a simple pitch. Rex Africa says it is the country’s first “AI-native” lender, built around artificial intelligence from the ground up rather than bolted on to an existing model. The company, which launched in late October 2026, offers savings, credit, payments and an AI financial agent called Rex Atlas that reads transaction history and offers conversational guidance on spending and saving.

On paper, it addresses a real gap. EFInA’s 2026 survey found that formal financial inclusion rose to 73% of Nigerian adults, yet only about 25% are financially healthy, meaning most banked Nigerians still lack real financial security. Rex is betting that intelligence, not just access, can close that gap.

But the launch materials leave basic questions unanswered. The company says it operates through Rex Microfinance Bank, yet its website shows no CBN licence number, as one publication pointed out. Its app store listing names RexCredit Limited as provider and Rex Financial Technologies Ltd as copyright holder, and records show it began life as Savyt in 2021 with a reported seed round of about USD 370 K. The same observation notes that the app has also been live since March 2024, which makes the October launch look more like an AI-led relaunch than a new bank.

Deposit protection is another gap. NDIC covers up to NGN 2 M (~USD 1.48 K) per depositor at microfinance banks, against NGN 5 M (~USD 3.7 K) at commercial banks, so a Rex saver with a large balance is only partly insured. Atlas also advises on borrowing while Rex sells loans through RexFlex, a tension the company has not addressed. And the site carries no privacy policy or terms, leaving unclear how Atlas uses customer data or whether it trains models on it.

Rex has not published customer numbers, deposits, loan books or default rates, and says only that it has attracted thousands of individuals and hundreds of businesses. It also offers investment guidance without saying what registration it holds for that, and no Nigerian rule yet sets a standard for AI that advises ordinary people on money. None of this means Rex cannot deliver. But for a firm asking customers to hand over their financial history, the burden of proof sits with the company.

Besides, Rex is entering one of Africa’s most crowded and well-capitalised retail banking markets. Fintech apps, not traditional banks, already dominate Nigerian smartphones. OPay is installed on 69% of devices surveyed by KPMG and Orange, PalmPay on 29%, Moniepoint on 14%, and Kuda on 8%. The best-performing legacy bank app, Access Bank, sits at 16%. These rivals are not standing still. Kuda has spent years building AI into advice and fraud tools, and Moniepoint processed NGN 412 T (USD 3-5.4 B) in payments in 2025.

The legacy banks are also mounting a costly counteroffensive. Nigeria’s ten largest lenders increased IT spending by 30.8% to NGN 177.91 B (USD 131.8 M) in the first quarter of 2026 alone, with Zenith Bank nearly doubling its technology budget to NGN 43.83 B (USD 32.4 M). That money is going into cloud infrastructure, cybersecurity and AI, precisely the ground Rex claims as its own.

Rex, by contrast, is a microfinance bank, not a commercial bank, operating under a different licence class with different limits. Competing with OPay’s balance sheet and Zenith’s IT budget will require far deeper pockets.

The regulatory backdrop adds another layer of execution risk. The Central Bank of Nigeria has upgraded fintech and microfinance licences to national status, raising minimum capital requirements to NGN 5 B (USD 3.7 M) for national operators. It has also set a January 2027 deadline for banks and fintechs to store payment transaction data on local servers, a costly compliance burden for smaller players. These are not minor operational details for a young microfinance bank trying to scale an AI platform.

Rex’s timing is sound because the financial health gap is real and policymakers are talking about it. But the gap between access and outcomes is exactly where fintechs and legacy banks are already fighting hardest.

Founder Yinka Odeleye says banking “should go beyond moving money to understanding customers”. That is a credible thesis. The harder question is whether a microfinance bank with limited capital can out-execute rivals that already own the customer relationship, the distribution and the technology budget. In Nigeria’s banking market, being first to a label is far easier than achieving durable scale, and it remains to be seen whether AI’s novelty alone would be enough.

OPay Seeks To Revive Terminated IPO Amid Crunch Talks To Appease China

By Staff Reporter  |  November 5, 2026

OPay, the Nigeria-focused fintech backed by SoftBank, pulled its USD 304 M New York listing hours after pricing it last week. The reason was an eleventh-hour inquiry from a Chinese regulator, despite the company having no operations or revenue in mainland China.

On the surface, the withdrawal looks like a decisive blow to one of Africa’s most anticipated tech listings. But according to Bloomberg, three people familiar with the matter say the discussions are not over. Talks between OPay and Chinese authorities are ongoing, though it remains unclear whether the regulatory concerns can be resolved. Insiders suggest the IPO is not dead, only halted and contingent on a negotiation that few outside the deal can see.

OPay is incorporated in the Cayman Islands and headquartered in Singapore. Nigeria accounted for 88.1% of its revenue in 2025. Its only link to China is founder Zhou Yahui, who also founded Kunlun Tech and was part of a consortium that acquired a stake in Opera in 2016.

Before the listing, OPay’s legal advisers concluded it did not need approval from the China Securities Regulatory Commission because it had no mainland revenue and its operating assets sat outside China. The prospectus nonetheless warned that uncertainty remained over how Beijing’s overseas listing rules could be interpreted. That uncertainty has now materialised. Chinese regulators are asserting jurisdiction over a company that, by the letter of its own filings, should fall outside their remit.

The stakes extend beyond OPay’s USD 4 B valuation. Standard Bank Group, Africa’s largest lender by assets, signed a subscription agreement to invest up to USD 200 M in OPay. Completion is explicitly tied to the IPO closing. If the offering does not complete, the subscription agreement does not proceed to closing. The halted listing therefore freezes a strategic partnership that OPay had framed as a gateway to expanding across the continent. A revival of the IPO would unlock both the public capital and the balance-sheet backing of a major African bank.

OPay’s revenue reached USD 467 M in the first half of 2026, up from USD 197 M a year earlier. Its 50 million monthly active users and dominant position in Nigeria’s digital payments market are not in question. Yet a single regulatory inquiry from a jurisdiction where the company does not operate was enough to stop the clock.

“The withdrawal should not be interpreted as a reflection of its business performance, financial condition, operational integrity or regulatory standing,” OPay said in a statement.

The ongoing talks give OPay a path back. If the matter is resolved, the listing could be repriced and relaunched, and Standard Bank’s investment could still close. If it is not, the message for other Africa-focused founders with Chinese links will be that the reach of Beijing’s regulatory perimeter is longer than their operating footprint. The outcome of the OPay IPO saga could shape how African tech assesses its exposure to forces far beyond its borders.

African Tech’s Offshore ‘Paper Parents’ Face Tough Tax Reckoning

By Henry Nzekwe  |  November 3, 2026

For a decade, the defining ritual of African venture capital has been the “flip.” A startup builds its product, hires its engineers, and finds its customers in Lagos, Nairobi, or Cairo, then incorporates a holding company in Delaware before the first institutional cheque arrives. The structure is often a compliance requirement imposed by investors who want a legal system they understand.

New data from a TLP Advisory report on 100 African tech companies shows just how lopsided this arrangement has become. The United States is the most common destination, with 67% of companies holding a US affiliation. But 81% of those US ties are incorporation and nothing else. There are no American customers, no American employees, and no American licences. The parent exists on paper.

The United Kingdom, by contrast, tells a different story. Of the 32% of companies with a UK affiliation, 47% have an operational presence and 19% hold regulatory licences. The UAE, meanwhile, is almost purely operational. Among its 23% of connected companies, 87% have people on the ground.

For years, this division of labour worked because tax authorities in home markets largely tolerated it. A Delaware parent could sell its shares and book a gain offshore, insulated from Nigerian or Kenyan capital gains tax. That tolerance is disappearing. Nigeria’s Tax Act 2025, which took effect in January, introduced an economic nexus rule. If more than half the value of an offshore holding company is derived from Nigerian assets, the sale of that company is taxable in Nigeria.

Foreign venture capitalists have warned the change could slow investment. “For founders, this means your exit valuation needs to be 20% higher just to give your investors the same net return they expected in 2024,” Segun Cole of Maasai VC told TechCabal in February.

L-R: Odun Longe, Funkola Odeleye, TLP Partners Co-Founders

The shift exposes a vulnerability at the heart of the incorporation-only model. A Delaware parent with no operational substance beyond a registered agent is precisely the kind of structure the new rules are designed to reach. The UK, which already hosts more real activity per affiliated company, is less exposed to that line of attack. A London entity with a licence, a team, and a bank account is harder to dismiss as a tax artifice.

TLP Advisory, a cross-border venture law practice with its origins in Nigeria, is careful not to overstate the UK’s advantage. “A round closed in Delaware and a license in London are both important but they play very distinct roles,” said Odunoluwa Longe, co-founder of TLP Advisory. The advice from Anthony William Catt of the UK Africa Sandbox is blunter: validate before you incorporate. “In the majority of cases our recommendation is a validation step with no entity,” he said.

That logic is about to become less optional. As African governments tighten the screws on indirect transfers and profit shifting, the purely paper parent will lose its appeal. The winners will be jurisdictions that allow a company to be both legally domiciled and economically present. TLP’s findings offer some evidence that the UK, with its combination of common law, tax incentives, and regulatory infrastructure, appears better placed for that future than the US.

Feature Image Credit: Dragos Condrea

Africa’s Hottest IPO Sold Out Online, Giving Tech A Tough Act To Follow

By Henry Nzekwe  |  November 2, 2026

When Dangote Petroleum Refinery opened its USD 1.6 B initial public offering in September, the rush did not begin at bank branches or stockbroker offices. It began on mobile phones.

Within thirty minutes of the offer going live, traffic on Bamboo, one of Nigeria’s largest digital investment platforms, surged to ten times normal levels. The app crashed. So did Cowrywise and InvestNaija. “To be very, very honest, our system broke,” Bamboo co-founder Yanmo Omorogbe told Reuters at the time.

Six weeks later, the scale of what happened on those apps is becoming clear. Exclusive collation data first revealed by Nairametrics shows the offer drew about 1.55 million unique online retail subscribers who placed roughly 2.2 million transactions worth more than NGN 860 B (USD 560 M). Bamboo alone processed more than 600,000 transactions valued at about NGN 99 B, outpacing even legacy names like Zenith Bank, FirstBank, Chapel Hill Denham and the Nigerian Exchange’s own portal. Total retail participation, including offline and association-based purchases, could approach five million subscribers.

That is a striking number in a market where only about 600,000 of roughly six million registered Central Securities Clearing System accounts were active as of late 2025. In a single offer, Nigeria’s fintech apps appear to have onboarded more first-time retail investors than the traditional capital market had activated in years. Bamboo said more than 43% of its new users who subscribed to the IPO were first-time investors.

For Nigeria’s technology ecosystem, the temptation is to read this as a breakthrough. For a decade, venture capital has flowed into Nigerian fintech, commerce and logistics with few credible ways out. Mergers and acquisitions remain the dominant exit route, with 63 deals recorded across Africa in the first half of 2026. Nigeria has never produced a venture-capital-backed IPO. The NGX launched a dedicated Technology Board in 2022, but three years later it has yet to record a single listing. OPay, one of the country’s most valuable fintechs, just terminated a New York Stock Exchange listing amid regulatory hiccups.

The Dangote offer proves that digital distribution can mobilise retail capital at a scale the NGX has never seen, though whether tech companies can tap it is a different matter. The refinery is a mature, cash-generating industrial asset backed by Africa’s richest man and a distribution budget of at least USD 31 M, according to its prospectus. A growth-stage startup cannot replicate that machinery.

More fundamentally, many Nigerian startups are incorporated in Delaware or London, earn naira revenue but raise dollar capital, and their investors expect dollar returns. A 2025 TLP Advisory report found that 53% of founders had not considered an NGX listing because they did not understand how local listings work. A separate TLP analysis estimated that a private tech company valued at USD 100 M could be valued at only USD 60 M on the NGX.

While the Dangote IPO has widened the retail on-ramp, the exit door remains narrow. But the listing has arguably created a template for startups, regulators, and the exchange to study. The NGX has said it is courting technology companies and pushing for dual listings. But until the currency, valuation and structural gaps close, the millions of Nigerians who bought refinery shares through their phones will remain investors in refineries and banks, not in the fintech products they use every day.

Feature Image Credit: Reuters

OPay’s Scrapped IPO Exposes Gap Between African Fintech Hype & Public Market Reality

By Staff Reporter  |  October 31, 2026

The most anticipated African fintech listing in years ended this week not with a bell, but with a quiet thud. SoftBank-backed OPay withdrew its USD 304 M U.S. initial public offering on Friday after a regulatory inquiry in an unidentified foreign jurisdiction spooked the deal hours after it had priced.

The company, which runs one of Nigeria’s largest digital payments platforms, had sold 16 million American depositary shares at USD 19.00 each, the bottom of its marketed range, valuing it at roughly USD 4 B.

The withdrawal is the most concrete signal yet that the wave of multibillion-dollar valuations assigned to African fintechs in private markets does not always survive contact with public investors. OPay is not a failing startup. It swung from a USD 50.8 M loss in 2024 to a USD 72.5 M profit in 2025, and in the first half of 2026 revenue more than doubled to USD 467.1 M while net income nearly quadrupled to USD 90.9 M. But those numbers, impressive in isolation, carry risks that a private valuation can ignore and a public listing cannot.

The first is the source of the profit. OPay markets itself as a payments company. In reality, just over half of its first-half revenue, about USD 236 M, came from loan financing tied to a Nigerian lending book that originated USD 927.6 M of new loans in six months. It charges annualised interest of 18.3% on 30-day loans and 16.8% on 60-day loans, rates that look attractive against Nigeria’s high inflation but depend on a consumer credit cycle that has not been tested through a full downturn. OPay writes off loans after 120 days, far faster than Nigerian banks’ 360-day standard, a sign of how quickly it needs to recycle capital to sustain growth.

The second is currency. OPay earns almost all of its revenue in naira, which has been repeatedly devalued, and reports in dollars. A weaker naira can erase a U.S. investor’s return even while the local business grows. Nigeria accounted for 89.5% of first-half revenue, leaving the company exposed to a single market’s monetary and regulatory trajectory.

The third is the regulatory fog that ultimately stopped the listing. OPay said the inquiry relates to a jurisdiction it considers “immaterial” to its core operations, Reuters reported, but it did not name the regulator or describe the nature of the investigation. That silence is curious.

OPay operates in Nigeria, Indonesia, Egypt and Pakistan, and its founder, Chinese billionaire Yahui Zhou, has business interests across multiple jurisdictions. Investors were asked to accept an undisclosed regulatory risk in a company valued at USD 4 B. When the inquiry surfaced, the underwriters, including Citigroup, Deutsche Bank, Standard Bank and CICC, agreed with OPay to terminate the underwriting agreement rather than proceed.

The collapse also strands a parallel arrangement with Africa’s largest bank. Stanbic Africa Holdings, a Standard Bank subsidiary, had agreed to buy up to USD 200 M in OPay shares through a private placement contingent on the IPO closing, capped at a 4.99% post-listing stake. That investment is now in limbo, along with a proposed secondary listing on the Nigerian Exchange that was meant to give local investors access to a business that derives nearly nine-tenths of its revenue from Nigeria.

OPay’s withdrawal signals the mismatch between the private valuation of African fintechs and the disclosure, governance and currency risks that public investors price. Airtel Money managed to list in London earlier this month at a USD 7 B valuation, but it did so as a subsidiary of a FTSE 100 company with a long regulatory track record. OPay has no such cover. Until it, and the investors who valued it at $4 billion, can name the jurisdiction that stopped the deal, the valuation remains a number on a prospectus.