Africa’s Traditional Savings Groups Quietly Emerge As New Payments Battleground
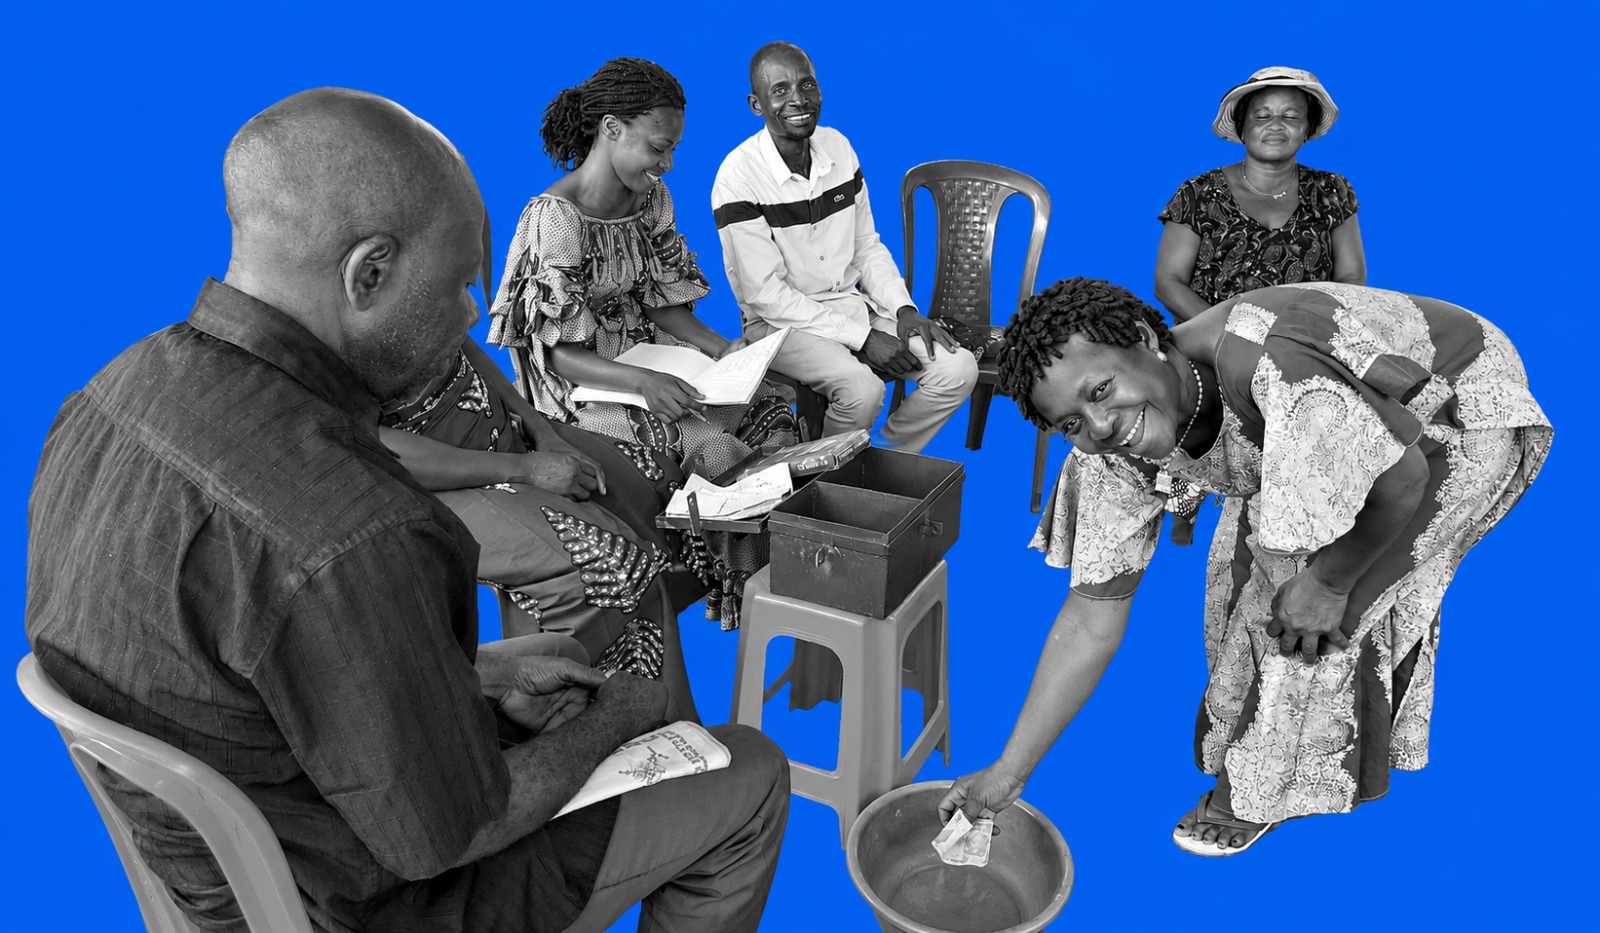
Across Africa, an old financial habit is becoming a new frontier for banks, fintechs, and mobile money providers. Community savings groups, long dismissed as the informal domain of cash-stuffed envelopes and handwritten ledgers, are being pulled into the digital economy at speed. The prize is not just the deposits they hold, but the transaction flows they generate.
The numbers explain the sudden interest. Kenya’s regulated savings and credit cooperative organisations held KES 1.21 T (USD 9.4 B) in assets in 2025, up 12.5% from a year earlier, according to the Sacco Societies Regulatory Authority. South Africa’s 800,000 stokvels manage about ZAR 50 B (USD 2.7 B) annually and count roughly 11 million members. Egypt’s MoneyFellows, which digitises the traditional gameya savings circle, says it has onboarded more than 8 million users.
These pools of money once sat largely outside the banking system. Now they are becoming the connective tissue for a payments market that banks cannot afford to ignore.
The competitive dynamic is most visible in Kenya. Commercial banks are racing to handle cheque clearing, ATM access, and real-time transfers for deposit-taking SACCOs, which are barred from direct access to the national payment infrastructure. Co-operative Bank of Kenya served 110 SACCOs with ATM connectivity in 2025, but Family Bank, KCB, and Equity Bank are expanding their footprints. Safaricom and payment provider Interswitch have entered the Pesalink instant transfer market for SACCOs, a sign that the settlement landscape is widening beyond traditional lenders.
SASRA reported that the number of SACCOs offering digital financial products rose to 267 in 2025 from 236 a year earlier. But the same report warned of cyber risks, and 107 regulated SACCOs still had no USSD connectivity at all. The digitisation race is real, but it is uneven.
***
In South Africa, the battleground is account opening. First National Bank completed the full digitisation of its stokvel accounts in early 2026, removing a long-standing requirement for three signatories to visit a branch together.
“We’ve completed the digital stokvel account journey and now everything, from account opening through to transactions and payouts, can now be done digitally,” said Himal Parbhoo, FNB’s CEO of cash investments. Standard Bank, Nedbank, and Absa offer stokvel accounts, but none have matched FNB’s end-to-end remote onboarding.
The broader significance lies in what happens to the money once it is inside a bank. Stokvel balances are stable and predictable, building through the year before seasonal payouts. For lenders, they are a low-cost source of funding. For members, formal accounts offer security. The trade-off is that community savings are being slowly absorbed into the same institutional structures they were designed to bypass.
Egypt offers a different model. MoneyFellows, which raised USD 13 M in 2025, has built a profitable business by digitising the gameya without requiring users to join pre-formed social circles.
“We’ve managed to crack this model and achieve profitability,” said founder and CEO Ahmed Wadi. “What makes this even more transformative is that we’ve facilitated billions in loans without using working capital.” The platform’s ability to generate credit scores from savings behaviour has turned a cultural tradition into a data asset.
Nigeria is also in the picture as new vigour seeps in after some previous stop-start endeavours. Rank, a fintech formerly known as Moni, launched Money Circles in 2026, a digital version of ajo and esusu rotating savings schemes. The company says it has paid out more than USD 100 M to users in the past year.
“For generations, Africans have relied on communal financial structures to build wealth,” said CEO Femi Iromini. “We are bringing these trusted traditions into the modern age by layering cutting-edge technology.”
The race is not without friction. Digitising savings groups requires trust, and trust is not easily coded. Many groups still prefer cash because it is visible. Others worry that formal accounts will expose them to fees or taxes. Regulators, meanwhile, are caught between encouraging financial inclusion and managing new risks.
What is clear is that the infrastructure behind community savings is becoming a market in its own right. Banks want the deposit base, fintechs want the transaction data, and mobile money providers want the payment rails. The savings groups themselves want convenience and security. Whether those interests align or collide will shape how hundreds of millions of Africans save, borrow, and build wealth in the years ahead.
Feature Image Credits: WVI