AI Is Eating Nigeria Faster Than Expected Amid Comforts And Concerns

By Staff Reporter  |  January 23, 2026

Nigeria is embracing artificial intelligence at a staggering pace, with adoption rates that eclipse global averages and a profound shift toward using the technology for economic survival and advancement. However, this rapid integration is unfolding alongside a significant deficit in public understanding, raising questions about the long-term implications of adopting a powerful tool that few claim to deeply comprehend.

A new survey by Google and Ipsos reveals that 88% of Nigerian adults have now used an AI chatbot, an 18-point surge from 2024. The driver is no longer novelty, but necessity. A remarkable 93% of users employ AI to learn new skills, while 91% use it for work tasks. Most strikingly, 80% have used it to explore a new business or career path, nearly double the global rate.

The Nigerian approach is intensely pragmatic, the study demonstrates, as AI is being leveraged as a tool for immediate upskilling, income generation, and navigating a challenging economic landscape.

This pragmatic adoption exists within a notable paradox. Extremely high trust coupled with relatively low knowledge raises concerns. While adoption soars, only 27% of Nigerians say they know “a lot” about AI. Despite this, an overwhelming 94% express confidence in tech companies to oversee AI in the public’s best interest, and 69% trust the government to do the same, figures well above global averages.

This trust extends to policy, with 71% of Nigerians prioritising innovation in fields like medicine over regulation to protect existing industries. Yet, a significant minority, 35%, believes government-imposed limitations are preventing the economy from fully benefiting from AI.

The sector experiencing AI’s most pronounced impact is education. Students and teachers are “super users,” and 91% of the public believes AI is having a positive impact on learning.

Expectations are sky-high, with 95% predicting benefits for university students and educators. This creates a self-reinforcing cycle where skills acquired through AI in educational settings are directly applied to professional and entrepreneurial pursuits.

The survey paints a portrait of a nation making a conscious, collective bet on AI as a catalyst for development. The critical, unanswered question is whether this comfort-first, knowledge-later approach will fuel sustainable growth or create vulnerabilities in a future increasingly defined by technological literacy.

West Africa’s Mobile Money Giants Lose Cash Cow To Strict Fee Cap They Can’t Fight

By Staff Reporter  |  October 5, 2026

Banks, fintechs and mobile money operators across West Africa will be forced to route all interoperable electronic money transfers through a single central bank platform from November 2, and they will be allowed to charge no more than 0.8% for transfers above a daily threshold of CFA francs 8 K (~USD 13.70).

The rules, published by the Central Bank of West African States (BCEAO) on October 2, mark the most aggressive intervention yet in a mobile money market that processed USD 498 B in transactions across West Africa in 2025, according to GSMA data. They represent a direct challenge to the business models of dominant operators such as Orange Money and Wave, which built their franchises on closed networks and transfer fees of around 1% or more.

The BCEAO, which oversees monetary policy for the eight-nation West African Economic and Monetary Union (WAEMU), had initially launched the platform, known as PI-SPI, on September 30, 2025, with free person-to-person transfers as its flagship selling point. One year later, that promise has been revised. Transfers of CFA francs 8 K or less, cumulated per day per user per participant, remain free. Above that, providers may charge up to 0.8% before tax. Receiving money is free without limit.

The central bank says the threshold keeps about 75% of electronic money transactions in the union free of charge. The cumulative nature of the cap is significant. Users cannot split a CFA franc 20 K transfer into three smaller ones to avoid fees. The daily total is tracked across all operations with the same institution.

“The logic of the reform is to protect small users while allowing providers to sustain the infrastructure,” said Tossouve Renaude Martinie, a payments specialist working across banking and mobile money in the region. “PI-SPI is not just a means of moving money. It is a public rail that the private sector must now build on.”

The pricing shift is accompanied by a regulatory mandate. From November 2, all interoperable electronic money transactions within WAEMU must transit through PI-SPI. Cross-border transfers within the union will follow the same pricing rules from June 1, 2027. The platform currently connects 175 institutions and reaches more than 38 million people, according to the BCEAO.

Wave, one of the region’s largest mobile money operators with more than 23 million monthly active users, joined PI-SPI on the September 30 regulatory deadline after a year of absence. The company built its success on a flat 1% transfer fee, and its delayed participation underscored the tension between its low-cost model and a free interoperability rail that could cannibalise its revenue.

Industry analysts expect operators to shift their monetisation strategies toward merchant payments, QR code services and business payment APIs. Ecobank, Standard Chartered, Orange, MTN and TouchPoint have already positioned themselves on the 24 certified business APIs that PI-SPI now offers.

“The real challenge is not connection. It is turning this infrastructure into daily usage,” said Aïssatou Ami Touré, managing director of TouchPoint Financial Services Senegal.

The rules leave several operational questions unanswered, including how providers must calculate fees on the transaction that takes a customer above the daily threshold.

The BCEAO has not specified whether the fee applies to the entire amount or only the portion exceeding CFA francs 8 K. For now, the central bank has drawn a clear line.

Foren Emerges From Leatherback’s Ghost After Crisis & Zedcrest Takeover

By Staff Reporter  |  October 5, 2026

Leatherback, the Nigerian-born, UK-headquartered cross-border payments company rocked by a string of upheavals of late, is now Foren. The name change, announced today, comes two months after Nigerian financial services group, Zedcrest, completed a full acquisition of the startup it first backed in a USD 10 M pre-seed in 2022. It marks the final erasure of a brand that spent two years fighting for its survival.

In November 2023, Nigerian authorities alleged that a shipping company, SDQ Facilitators, had used a Leatherback account to defraud victims of about USD 10 M. The EFCC declared co-founder and CEO Ibrahim Ibitade wanted, and Leatherback’s Nigerian bank accounts were blocked.

The company sued; Ibitade filed a human rights suit, and in February 2025, a Federal High Court in Lagos ordered the permanent forfeiture of over USD 800 K traced to SDQ’s dollar wallet on the Leatherback platform. Ibitade was cleared of wrongdoing, but the reputational damage was done.

He stepped down in October 2024, citing a desire to start a family and “multiple misalignments of goals and visions” with lead investor Zedcrest. By February 2025, he had launched Prune Payments, a direct competitor to the company he founded. Interim CEO Toni Campbell exited in June 2025. Former Cellulant executive Ochebhoya Ekpete took over in August 2025 and immediately pivoted the company from consumer remittances to enterprise infrastructure.

The rebrand is being framed as an evolution. Ekpete says the company spent two years “rebuilding everything a customer relies on but rarely sees” and that “by the time that work was done, we were a different company, and Leatherback no longer described us”.

While Leatherback was not found guilty of anything and the founder was cleared, it appears the company has figured it’s better off moving on from its previous identity, as the association with a fraud investigation can often prove too toxic to shake.

Foren now positions itself as a unified platform for global accounts, cross-border payouts, foreign exchange, and treasury management, targeting businesses rather than individuals.

Zedcrest’s backing gives it the capital and institutional cover to pursue regulatory licences and banking partnerships that a scandal-tainted startup could never secure alone. The company plans hubs in Canada and Kenya to complement its London headquarters and new West African base in Nigeria.

The USD 8 M Bet That Africa Can Win The Space Data Centre Race Without Launching A Single Satellite

By Staff Reporter  |  October 2, 2026

Rama Afullo pitched orbital data centres inside Google and SpaceX. Both said no. So he raised USD 8 M to build what they wouldn’t.

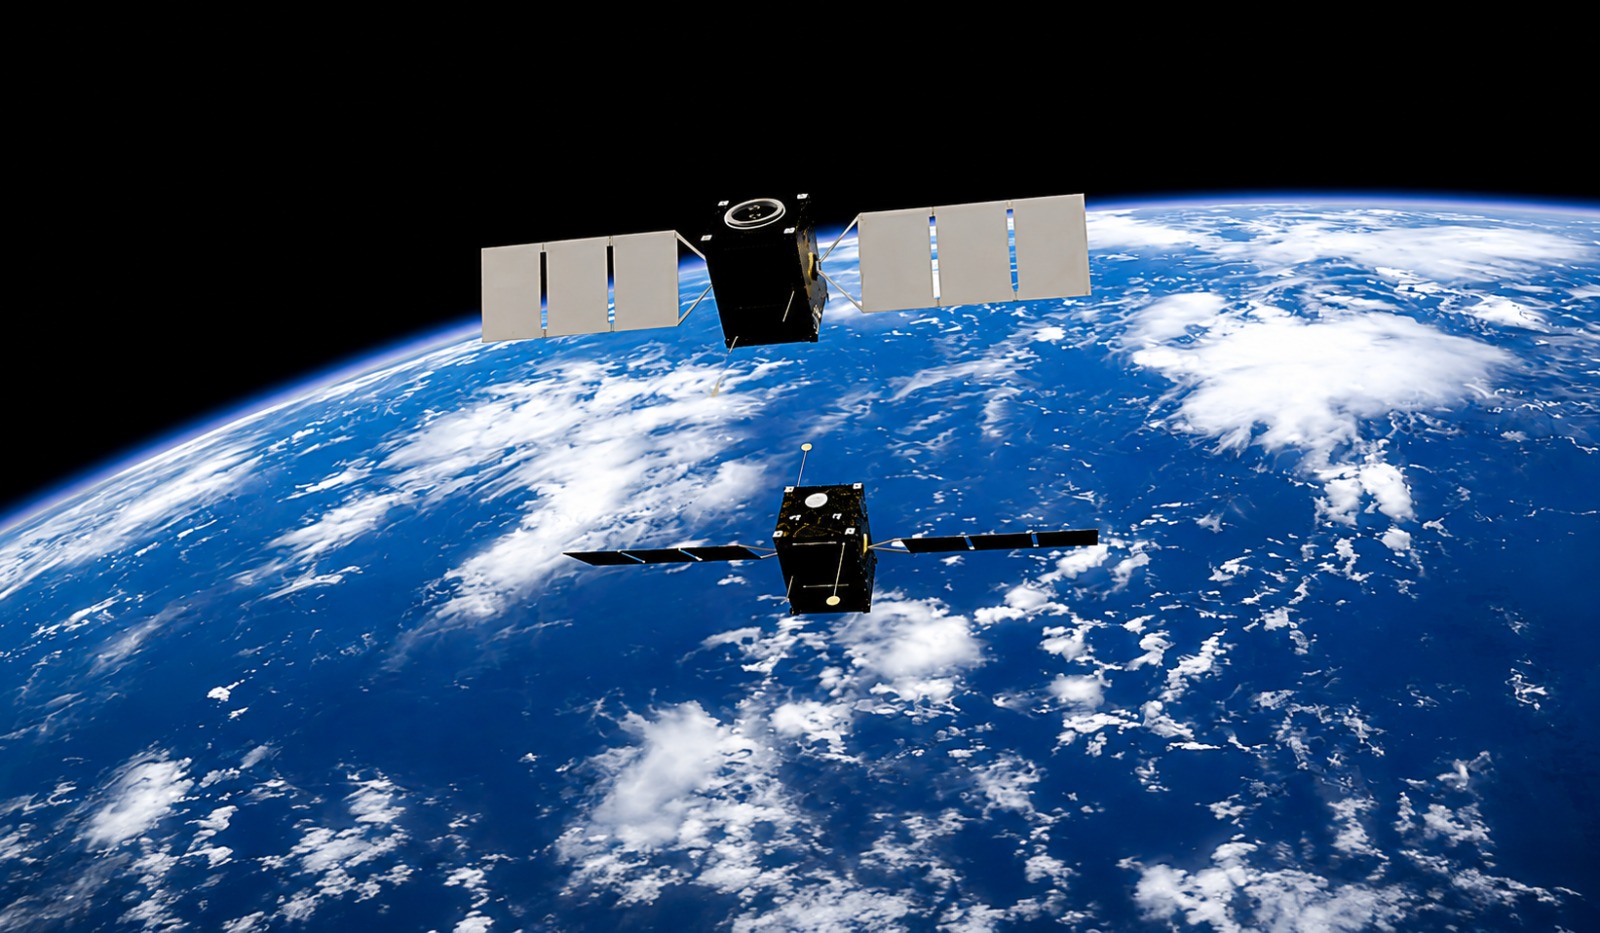
Satlyt, his Sunnyvale and Nairobi-based startup, closed a seed round this week led by Houston’s Non Sibi Ventures, with participation from TLCOM, Antler, Launch Africa Ventures, and others. The company’s software launched Thursday on a SpaceX rocket, riding alongside Google’s first Project Suncatcher prototype.

Most satellites already carry unused computing power. Satlyt’s software turns that idle hardware into a distributed AI network. Instead of building new spacecraft, the company makes existing ones smarter. Afullo compares it to VMware or Snowflake, a software layer that abstracts away the infrastructure. “If SpaceX is the iPhone, we’ll build Android,” he told TechCrunch.

This matters because the orbital data centre race is heating up. SpaceX has pitched investors on up to 1 million AI satellites that could generate trillions in revenue. Google is testing its own hardware. But building data centres in orbit remains brutally expensive.

A 1-gigawatt orbital facility would cost roughly USD 170 B, more than three times a comparable ground-based facility. Space compute currently runs at about four times terrestrial costs. Bain & Company estimates orbital data centres won’t reach commercial scale until the early 2030s and will capture only a modest share of global compute by 2040.

Satlyt sidesteps that capital trap. By focusing on software for satellites already in orbit, the company avoids launch costs, radiation hardening, and thermal management challenges that plague hardware-first approaches. Its earlier deployment of Google’s Gemma model on a Momentus spacecraft cut data transmission sizes by more than 60%, a direct cost saving for operators paying for downlink bandwidth.

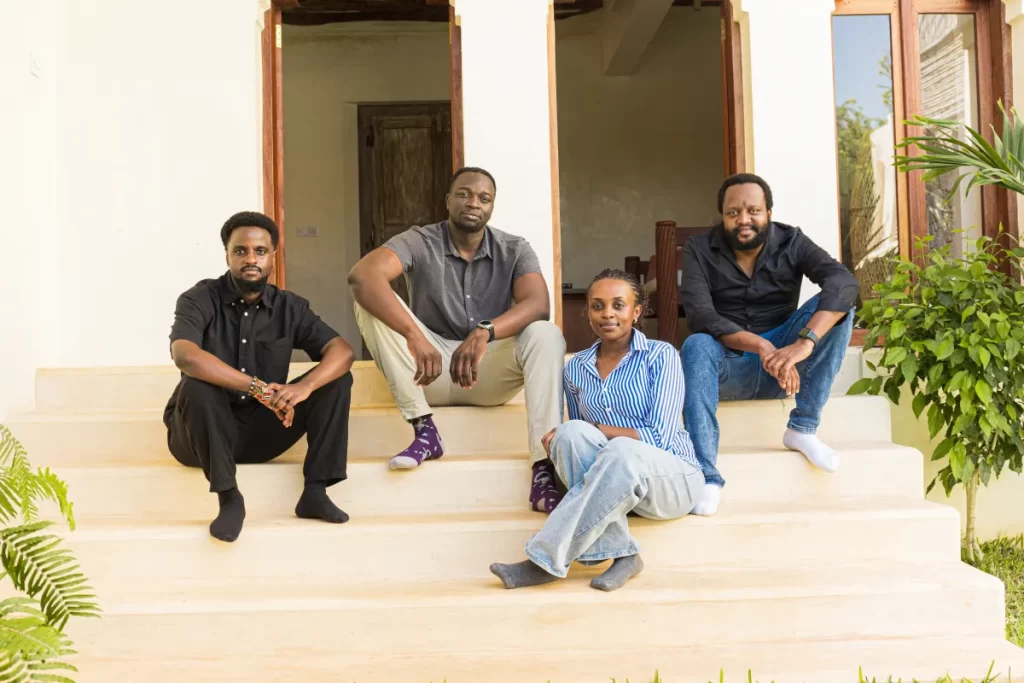
Satlyt team: Leina Moli (Senior Space Software Engineer), Rama Afullo (Founder & CEO), Junn Wangari (Senior Space Systems Engineer), and Nelson Psenjen (CTO)

Satlyt’s leadership team is entirely Kenyan-American, with engineering concentrated in Nairobi. The company has signed memoranda with the Kenya Space Agency and Angola’s GGPEN to deploy AI-driven Earth observation for agriculture, climate monitoring, and disaster response. For a continent that spends billions importing satellite data it cannot process locally, onboard AI offers a path to sovereignty over its own geospatial intelligence.

The risks are real. Satlyt has not yet demonstrated its most ambitious claim, a cloud network spanning multiple satellites. Besides, high-performance GPUs remain scarce in orbit, and the economics of orbital compute may never favour generalised workloads. But Satlyt says it’s going beyond compute to sell efficiency to operators who already own the hardware.

Afullo wants Satlyt’s software on 20% of satellites by 2030. That is an ambitious target. But if the satellite industry follows the trajectory of terrestrial cloud computing, winning will likely be less about building the biggest data centres and more about making the existing ones work harder.

For a continent largely absent from the first space race, that is a more plausible route to relevance than waiting for Starship to deliver a hyperscaler to low Earth orbit.

Electric Bikes Are Quietly Winning Africa’s Delivery Fleets One Battery Swap At A Time

By Henry Nzekwe  |  September 30, 2026

Africa’s delivery riders are making a cold, financial calculation. With petrol prices surging in South Africa and fuel costs consuming up to 40% of a rider’s income in markets like Nigeria, the economics of the internal combustion motorcycle are collapsing. Electric two-wheelers, once dismissed as costly experiments, are now courting the continent’s delivery fleets with a proposition that is less about saving the planet than saving the margin.

The simple pitch is that battery swapping eliminates the upfront cost of ownership and the downtime of charging. ARC Ride, a Kenyan electric motorcycle company, launched its Panther model in South Africa this month at ZAR 22.5 K with a battery-as-a-service model where a full swap costs ZAR 50.00 and delivers up to 110km of range. The company estimates that at the current inland petrol price, its electric bike costs about 30% less to run per 100km than a comparable 125cc petrol motorcycle.

Spiro, Africa’s largest battery-swapping operator, reports that its riders save an average of USD 3.00 per day on fuel and maintenance, while the company earns roughly USD 0.50 per battery swap. In Nigeria, a Spiro rider spends about NGN 125.00 to travel 100 kilometres on electric versus over 3,400 naira on petrol. The company has deployed more than 130,000 electric motorcycles across seven African countries and operates over 2,500 swap stations. “We don’t sell motorcycles; we sell kilometres,” says Spiro CEO Jules Samain.

The model is spreading through commercial partnerships rather than consumer sales. Jumia, Africa’s leading e-commerce platform, has partnered with Spiro in Uganda to electrify nearly half of its delivery fleet in Kampala.

“By introducing electric bikes into our fleet, we are demonstrating that e-commerce can be both convenient and climate-conscious,” says Steven Lamony, Jumia Uganda’s managing director. In Kenya, Roam Air electric motorcycles now power a fully electric cold-chain network with Keep It Cool, cutting fuel and maintenance costs by up to 75% compared to petrol bikes.

But the pivot is not without friction. ARC Ride had to correct launch material that claimed riders would earn “up to 20% more net earnings,” clarifying that the figure refers to a reduction in weekly operating costs, not income. Battery-swapping infrastructure remains concentrated in major cities, and the economics vary by rider. Someone covering 50 kilometres a day will save less than someone covering 150 kilometres.

The direction is evident, regardless. Afreximbank’s development arm has led a USD 75 M equity investment into Spiro, the largest-ever bet on an African electric motorcycle company. Spiro has also partnered with Chinese manufacturer Yadea to expand production and adapt vehicles to African road conditions. In South Africa, Valternative Energy has deployed over 1,000 electric delivery motorcycles and 100 swap stations in under two years, serving Uber Package and Famous Brands.

For fleet operators squeezed by fuel volatility and maintenance costs, the electric motorcycle is becoming more of a lifeline than a green mandate.

Copia’s USD 123 M Collapse Exposes Kenya’s Rural E-Commerce Math Problem

By Staff Reporter  |  September 30, 2026

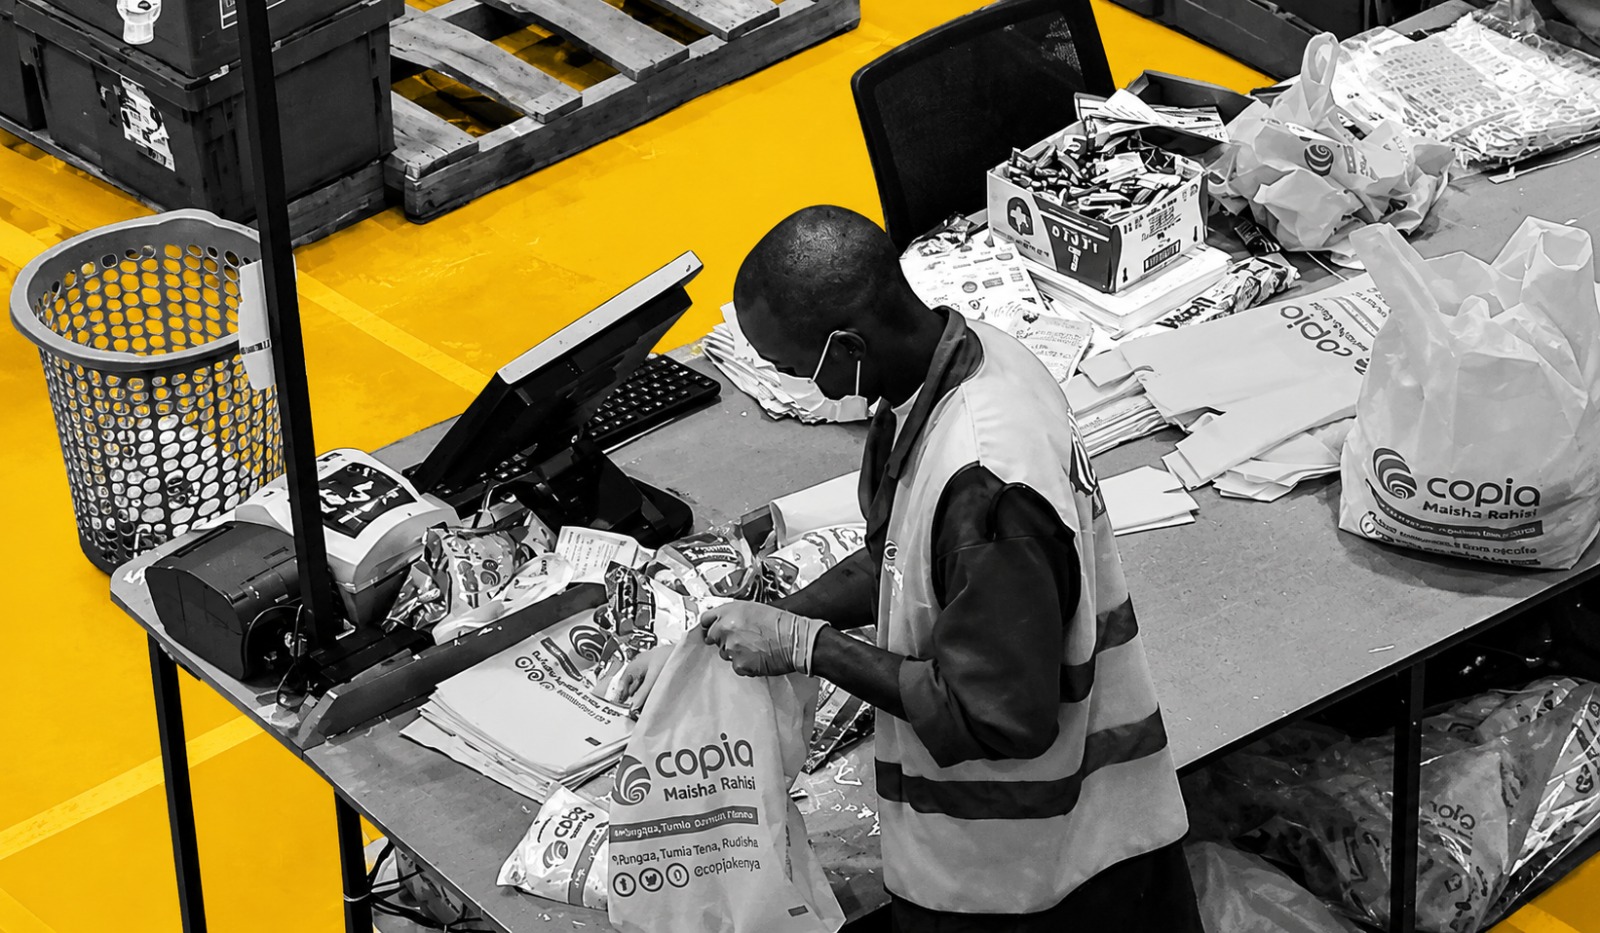
Kenya’s High Court ordered Copia Kenya into liquidation on September 17, ending a two-year administration process that failed to revive a company that raised USD 123 M to solve one of African e-commerce’s hardest problems. The startup’s realisable assets stand at just KES 206.6 M (USD 1.6 M), against liabilities that “substantially exceed that amount,” according to court filings.

The court found no realistic path for Copia to return to operating as a going concern. “I am satisfied that the Joint Administrators have demonstrated, on a balance of probabilities, that the objectives of administration have been exhausted,” Justice Rhoda Rutto wrote in the ruling. The same administrators, Julius Mumo Ngonga and Anthony Makenzi Muthusi of KPMG, have been appointed joint liquidators.

Founded in 2013 by Tracey Turner and Jonathan Lewis, Copia built a 50,000-agent network across Kenya and Uganda, using local shopkeepers as order points and collection centres for rural and peri-urban households. The model was designed for consumers with limited internet access, no formal delivery addresses, and little trust in online-only retail. Copia aggregated orders so that deliveries to a local agent could serve many households at once.

But the underlying arithmetic never worked. Rural last-mile delivery across African markets typically accounts for 35 to 55% of total shipping costs, compared to a global average of about 28%. Copia’s average order value hovered around USD 10.00, while the company carried the full weight of warehouses, depots, delivery vehicles and tens of thousands of agent commissions between manufacturers and consumers.

The startup bet that higher volumes would eventually spread those costs across more orders. That bet never paid off. Copia never turned a profit in its 12-year existence. It laid off 350 employees in July 2023, closed its Uganda business in April, and abandoned expansion plans into Nigeria, Ghana, South Africa and Mozambique before entering administration in May 2024 after its parent company failed to raise fresh capital.

More than 1,000 jobs were cut. Investors including Goodwell Investments, Lightrock, DOB Equity and the US International Development Finance Corporation are unlikely to recover anything. Copia’s failure is now part of a broader pattern in Kenya, where 13 venture-backed startups have collapsed or entered administration over the past five years, erasing at least USD 717 M in investor capital.

Kenya’s startup funding environment has tightened sharply. Startups in the country raised about USD 126 M in the first half of 2026, down from USD 227 M a year earlier, as investors pivoted away from growth-at-all-costs strategies toward profitability and sustainable unit economics.

What makes Copia’s collapse particularly striking is what happened next. Barely a month after the company entered administration, Turner and former CEO Tim Steel registered Stahili, a new e-commerce platform promising cashback, discounts and mobile data rewards.

Corporate filings show Stahili is wholly owned by Copia Holding Company, the same US-registered entity linked to Turner and the now-defunct Copia Global. The new venture is positioned as a leaner, digitally native alternative that does not build expensive last-mile delivery networks

Crypto Regulations Put South Africa’s Top Banks In Conflict Over Payments

By Staff Reporter  |  September 30, 2026

A quiet but consequential battle is unfolding in South Africa over the future of cross-border payments, and the stakes are far higher than the usual regulatory squabble.

At its core, a coalition of crypto firms and now a major digital bank is fighting draft rules from the National Treasury and the South African Reserve Bank (SARB) that would effectively ban South African companies from using crypto assets or stablecoins for cross-border payments.

The coalition, which goes by the acronym CATASTROPHE (Crypto Asset Taskforce for Advancing Sound, Technology-Neutral Regulation for Opportunity, Prosperity and a Healthy Economy), has been joined by GoTyme Bank, a digital bank with over 13 million customers. It argues that regulation should target financial activities, not the technology used to perform them.

The proposed rules are part of a broader overhaul of South Africa’s exchange control system. The draft Crypto Asset Manual, published in August 2026, would require all cross-border crypto transfers to be routed through authorised dealers and reported to SARB’s Financial Surveillance Department. Individuals would retain allowances of ZAR 2 M (USD 122.8 K) and ZAR 10 M (USD 614 K), but companies would get nothing. A salaried professional would have more freedom to move money across borders than an exporter paying a supplier.

The industry says this is already causing damage. VALR CEO Farzam Ehsani told Moneyweb that ZAR 2.2 B ~(USD 134 M) in potential foreign investment has been placed on hold because of the uncertainty. He warns that prohibiting corporate crypto payments “is likely to drive transactions underground or offshore”.

The banks, for their part, are not united in opposition. Absa, one of South Africa’s largest banks, sees the rules as overdue clarity, though it acknowledges they would “naturally limit immediate opportunities”. This split reveals the tension as incumbent banks are comfortable with rules that constrain a competing settlement rail, even as a digital challenger like GoTyme breaks ranks to back the crypto industry.

Reserve Bank Governor Lesetja Kganyago has framed the issue as one of fairness. “If we have these rules, we cannot simultaneously have weak regulatory frameworks for crypto assets alongside a rigorous system of reporting and permissions for everyone else,” he said at the central bank’s annual meeting.

South Africa is among Africa’s largest crypto markets, with an estimated USD 35 B in annual on-chain volume. Nearly 8 million South Africans used crypto platforms in the first half of 2025. The country liberalised parts of its exchange control regime earlier this year, then moved to pull crypto back under strict capital flow rules.

The public comment period closed on September 30. The industry has signalled it may pursue a legal challenge if its objections are ignored. The outcome will determine whether South Africa regulates crypto as a technology or as a financial activity, and whether its businesses can compete globally using the payment rails of the future.

A Nigerian Entrepreneur’s Unusual Bet On A Blockchain Phone No One Knows They Need

By Henry Nzekwe  |  September 28, 2026

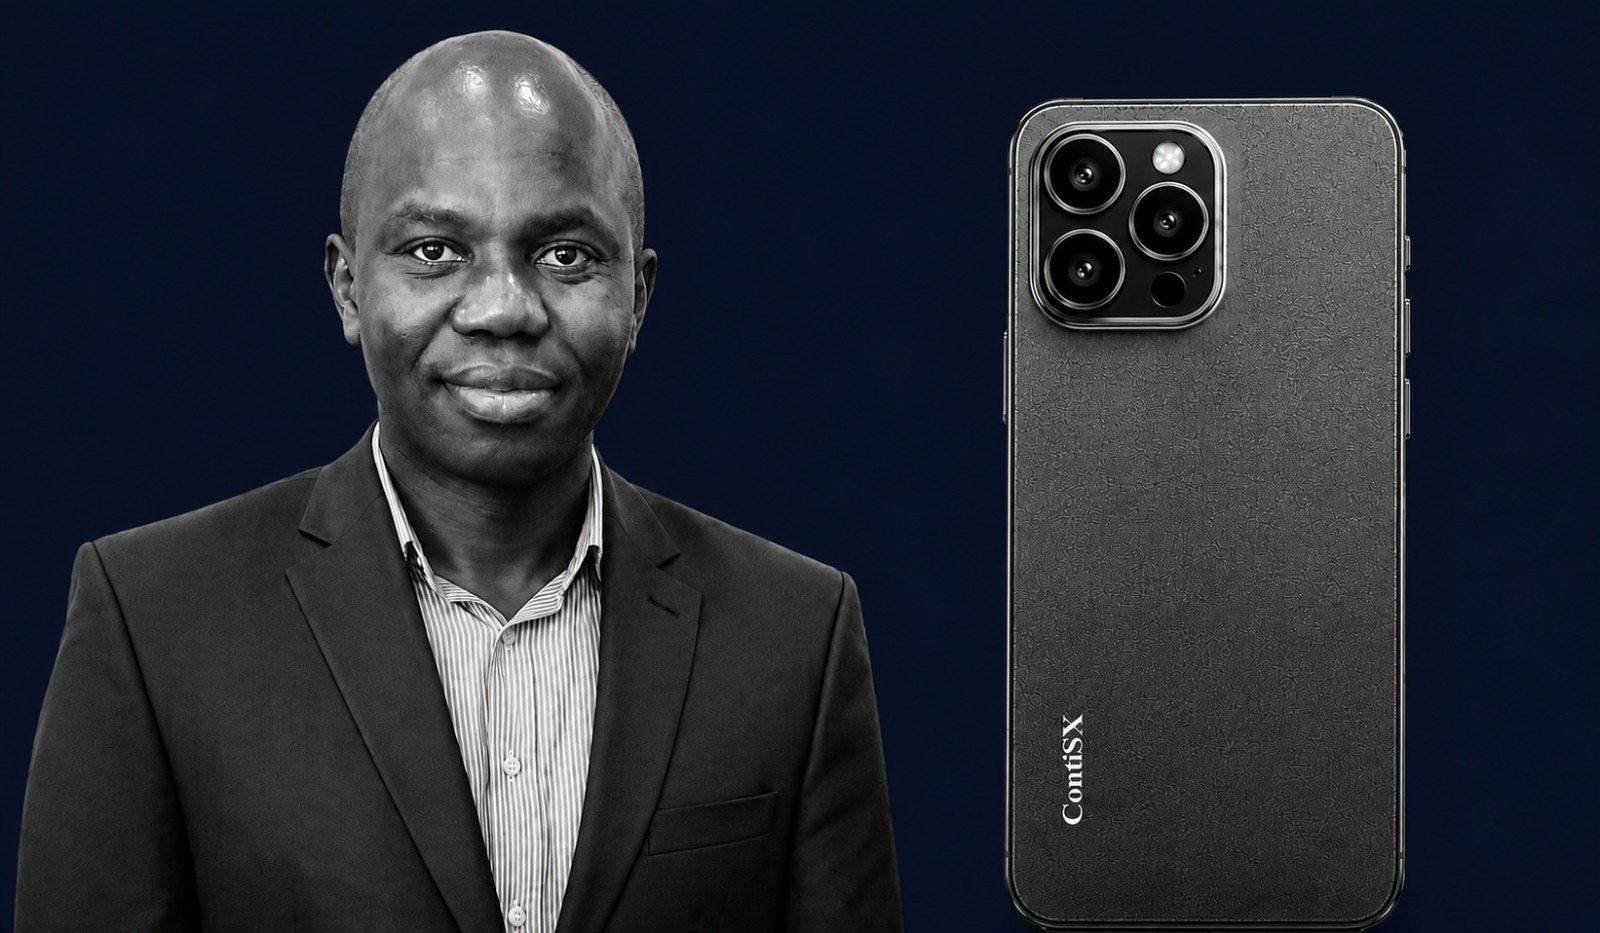
Ndubuisi Ekekwe has spent his career building things that end up inside other people’s products. At Analog Devices, he helped design the accelerometer that went into early iPhones, as his colourful biography captures. Other feats attributed to him include a PhD research project in wafer-level chip packaging that still earns him U.S. government royalties, two doctorates, four master’s degrees, and a patent on medical robotics microchips that the U.S. government acquired rights to.

Now the storied educator cum entrepreneur is rolling out a phone he developed; a peculiar kind which he calls Africa’s first blockchain phone. Ekekwe’s ContiSX Securities Exchange Plc has opened preorders for the ContiSX Phone, a blockchain-native handset priced at NGN 550 K, around USD 400.00 at current rates.

Shipments are scheduled to begin October 19, the same day Ekekwe plans an event at the State House Banquet Hall in Abuja’s Presidential Villa. The phone runs neither Android nor iOS. It cannot install WhatsApp, Instagram, or Facebook. It is a walled garden, and Ekekwe is betting that Nigerian institutions will pay to live inside it.

The pitch

The device’s core proposition includes encrypted messaging, voice, and video calls at the blockchain level, with cryptographic keys isolated in a dedicated secure enclave and biometric authorisation on device. ContiSX says the phone’s encryption is guaranteed against eavesdropping and tampering. The company has not published independent security audit results.

The phone’s real hook is what it connects to. ContiSX received Approval-in-Principle from Nigeria’s Securities and Exchange Commission in April 2026 to establish a full-service securities exchange targeting equities, bonds, ETFs, and commercial paper. The AIP is an early-stage regulatory clearance, and it does not yet permit full operations. ContiSX had initially targeted a September 2026 launch and has since pushed to October.

For one year after purchase, preorder customers get zero-rated data access to ContiSX’s exchange and central securities depository. Ekekwe says the company has prepaid participating Nigerian telecommunications companies to cover those data costs.

“When we launch ContiSX Securities Exchange, you will not need data to buy stocks, FGN bonds and other investment products within our ecosystem,” Ekekwe wrote on LinkedIn. “Our philosophy is Investment Inclusion, and we want to remove barriers that prevent citizens from participating in capital markets.”

The market reality

Nigeria’s smartphone market is brutally price-sensitive. The average selling price in Q1 2026 was USD 134.00, up just 2% year-on-year. Phones below USD 150.00 account for more than 60% of volumes. Roughly 90% of devices sold in the country are imported. Omdia forecasts African smartphone shipments could decline in 2026 amid rising memory costs and currency volatility.

At NGN 550 K, the ContiSX Phone costs roughly four times the average selling price. It is not competing with Tecno and Infinix but with mid-range Samsung and Apple devices, which collectively hold a significant share of the Nigerian market.

But Ekekwe’s target buyer is not the mass market. It is Nigerian institutions, government agencies, and businesses that value sovereignty over cost. The phone ships with ContiSX Shield for security alerts, Boardroom for corporate governance, and a Business Suite covering accounting, payroll, and inventory management.

The regulatory backdrop has shifted in Ekekwe’s favour. In July 2026, President Bola Tinubu signed an executive order establishing a Virtual Asset Council chaired by the Central Bank of Nigeria, with the SEC as vice-chair. The order explicitly aims to close gaps that unregistered operators have exploited, while enabling “responsible innovation” through a CBN regulatory sandbox.

Whether Ekekwe can convert that goodwill into a functioning exchange with actual issuers, investors, and financial institutions is the open question. Ekekwe has spent decades building components that other people put their names on. This time, the name on the box is his, and he’ll be hoping for tailwinds.

AvadaPay: The Best Payment Provider for Digital Platforms in Africa

AvadaPay: The Best Payment Provider for Digital Platforms in Africa

By Partner Content  |  September 28, 2026

You’ve built the platform. Customers can register, place an order, book a service, subscribe, request financing, or use whatever product sits at the center of your business.

Now they need to pay.

Whether you’re building a SaaS product, a marketplace, a mobility platform, a digital lending product, or another online service, payments are essential to the customer experience. But they’re rarely the reason the product exists.

This leaves many digital platforms with a decision to make: spend engineering time connecting payment methods, setting up collections and payouts, and adding transaction notifications. Or work with a payment partner that already has that infrastructure.

Building these capabilities in-house takes development time and ongoing maintenance. Using several providers can create even more integrations and systems to manage.

AvadaPay offers a simpler setup, making it easier for digital platforms to manage collections, payouts, and Bulk SMS via a single integration.

About AvadaPay

AvadaPay is a payment platform helping businesses accept and manage digital payments across African markets. Through a single integration, digital platforms can connect to local payment methods, manage collections and payouts, track transactions, and use Bulk SMS for customer communication.

This makes AvadaPay particularly useful for platforms launching in or expanding across Africa, where payment methods and customer preferences can differ significantly between markets.

As Maurice Bisungo, Key Accounts Manager at AvadaPay, explains:

“Digital platforms already have a lot to build and manage. Having a payment partner that can take care of collections, payouts and the supporting infrastructure gives teams more room to focus on their product and customers.”

With the payment infrastructure taken care of, businesses can focus their engineering resources on the platform and customer experience they’re actually building.

One Integration to Local Payment Methods

Customers pay with the methods they already trust, and those methods change from market to market.

According to the GSMA, around $1.4 trillion moved through mobile money in Sub-Saharan Africa in 2025, roughly two-thirds of the global total.

A platform entering Kenya needs M-Pesa. In other markets, customers may reach first for MTN Mobile Money, Airtel Money, Orange Money, or another local payment method.

‘’One thing we see across African markets is how strongly payment preferences differ from one country to another. Making familiar local payment methods available gives customers an easier experience and helps platforms adapt as they enter new markets,” says Winnie Odede, Regional CEO, AvadaPay East Africa:

AvadaPay offers businesses different ways to make these local payment methods available to customers. For online payments, platforms can integrate AvadaPay’s API directly into their website or app, generate payment links or use STK Push. For in-person collections, merchants can accept mobile money payments using a unique QR code that customers scan, enter the amount and authorize from their phone.

Collections In. Payouts Out.

Plenty of platforms need money to move in both directions.

A marketplace collects from buyers and pays sellers; a mobility platform collects from riders and pays drivers; and a lending platform disburses loans and collects repayments.

AvadaPay supports both collections and payouts, allowing businesses to build payment flows around how their platform actually works.

And because both run through the same platform, businesses get a single view of the money moving in and out.

Payments Need Communication Too

Then there’s everything that happens around the transaction:

Payment received.

Your OTP is 4821.

Your payout has been processed.

Your payment is due.

AvadaPay also offers Bulk SMS for OTPs, payment confirmations, transaction alerts, reminders, onboarding messages, and other customer communication.

That means businesses can set up the payments and the messaging around them without adding yet another provider to the stack.

Build Once. Expand Further.

The value of this approach becomes even clearer when the next market appears on the roadmap.

Without regional payment infrastructure, expansion can mean starting the integration process again: new payment methods, new connections, new technical work.

As Florien Maniraho, CEO of AvadaPay Rwanda, explains:

“Expanding into a new market should not mean rebuilding your payment infrastructure from the beginning. If the foundation already connects you to the local payment methods you need, your team can spend more time on launching and growing the product.”

AvadaPay provides local payment methods, collections, payouts, Bulk SMS, and transaction visibility through one integration across supported African markets.

For a new platform, that’s far less to build before the first payment comes in.

For an existing platform expanding into Africa, it means adding the local payment methods customers expect without starting from scratch.
Airtime Lending Turf War Rocks South African Fintech Quietly Dominant In Nigeria

By Staff Reporter  |  September 25, 2026

A regulatory turf war between two Nigerian agencies briefly cut off airtime credit for an estimated 40 million mobile subscribers in April, exposing how a single South African fintech had quietly become critical infrastructure for Nigeria’s poorest phone users.

The Federal Competition and Consumer Protection Commission (FCCPC) extended its Digital, Electronic, Online or Non-Traditional Consumer Lending (DEON) regulations to cover airtime credit services in April 2026. The Nigerian Communications Commission (NCC), which licenses value-added service providers, was not consulted. Caught between the two regulators, MTN Nigeria, Airtel Nigeria, Globacom and 9mobile suspended their airtime lending products on April 15.

The Federal High Court in Abuja issued an interim injunction on April 24 restraining the operators from cutting off access to Nairtime Nigeria Limited, Optasia’s local subsidiary. Services were fully restored on June 24. But the financial damage was already done.

Nigeria accounted for approximately 14% of Optasia’s group revenue in its 2025 financial year. By the second quarter of 2026, that figure had fallen to under 4%. Optasia’s H1 2026 revenue still grew 58% to USD 185.3 M, driven by expansion in Ghana, Pakistan, Indonesia and Congo-Brazzaville. Chief Executive Salvador Anglada said the group had delivered growth “across all parameters” despite the Nigerian disruption.

The broader investment signal is harder to dismiss. Foreign capital inflows into Nigeria’s telecom sector fell to USD 7.24 M in the first quarter of 2026 from USD 80.78 M a year earlier, according to the National Bureau of Statistics. The Association of Licensed Telecommunications Operators of Nigeria (ALTON) disputes the figure, noting operators invested NGN 2.13 T in capital expenditure in 2025 and plan NGN 1.86 T for 2026. But the timing of the regulatory clash coincides with the sharpest quarterly drop in recorded foreign telecom investment in recent years.

The Federal High Court in Lagos delivered a landmark judgment on July 20, ruling that the FCCPC can regulate competition and consumer protection in airtime lending but cannot issue telecommunications licences. That authority remains exclusively with the NCC. Justice Ambrose Lewis-Allagoa summarised the principle in a single line: “Concurrency means coexistence, not displacement”.

President Bola Tinubu had already moved before the judgment. In June, he directed the FCCPC to dismantle Optasia’s 12-year dominance and approved nine Nigerian fintechs to compete in a market estimated at NGN 3 T in annual transaction value. The FCCPC argued the exclusive arrangement facilitated capital flight while contributing minimally to local tax revenues or employment.

Optasia rejects the monopoly framing. Its Nigerian subsidiary, Nairtime Nigeria Limited, is “fully locally incorporated, locally staffed and locally led,” the company said. Anglada has called the suspension “a little bit aggressive”.

Meanwhile, the Wireless Application Service Providers Association of Nigeria has appealed the July 20 judgment, asking the Court of Appeal to suspend enforcement of the DEON regulations pending determination. ALTON has called for a formal coordination protocol between the FCCPC and the NCC. The NCC has yet to publicly stake out its position.

Airtime credit is not a niche product, offering a lifeline to millions of Nigerians who borrow a few hundred naira in airtime when their balance runs out. It is how traders, artisans and workers at the base of the economy stay connected when formal credit is unavailable. When the service goes dark, they feel it immediately.

In the same vein, when the regulatory environment goes dark, investors feel it for years. and it’s unlikely that Nigeria can afford another regulatory turf war in a sector it wants to lead globally.

Feature Image Credits: Cardtonic

The Kiosk That Taught Kenya To Trust Digital Money Is Dying

By Henry Nzekwe  |  September 24, 2026

It’s not uncommon to hear that Kenya’s mobile money revolution has about as much to do with technology as with hundreds of thousands of small shops, kiosks, and street corners where a generation of Kenyans learned to trust digital money, one deposit and withdrawal at a time. That network is now shrinking.

Communications Authority of Kenya data show registered mobile money agents fell 5.6% between March and June, from 602,470 to 568,463. The decline came even as mobile money subscriptions climbed to 54.01 million, pushing penetration to 101.3%. More Kenyans are using mobile money than ever, but fewer are using agents to do it.

The two numbers tell the same story from opposite ends. Mobile money is succeeding so thoroughly that it is beginning to make its own physical infrastructure redundant. For nearly two decades, agents were the human API connecting cash to digital wallets, especially where bank branches were scarce. Now smartphones, interoperability, and merchant payment systems are letting customers bypass that step entirely.

Central Bank of Kenya data show active agents processed 212.45 million cash-in and cash-out transactions worth KES 682.46 B (~USD 5.26 B) in June alone. That is still a lot of money moving through the agent network. But the direction of travel is changing.

The value of cash handled by agents fell by a record KES 430.3 B (USD 3.3 B) in the first eleven months of 2025, the sharpest drop in Kenya’s history. The Central Bank attributed the decline to shifting usage patterns rather than reduced relevance, noting that users increasingly consolidated transfers into fewer, higher-value payments and adopted merchant payment channels instead of withdrawing cash.

***

The economics of being an agent are also getting harder at exactly the moment the network has grown more crowded. Safaricom’s M-Pesa agent base expanded 11.4% to 333,011 in the year to March 2026. Total commissions paid to agents rose just 0.3% to KES 37.4 B (USD 288.6 M) over the same period. Average annual commission per agent fell 10% to KES 112.2 K (USD 866.41), or roughly KES 9.353 K (USD 72.20) a month.

The commission pot is growing at 1.3% while the agent count grows at 20%. That dilution is the quiet crisis beneath the headline decline. “The average agent is now generating gross revenue of less than KES 10 K per month,” noted one analysis of Safaricom’s half-year disclosures. “For a standalone shop paying rent and electricity, this is statistically a loss-making venture.”

When M-Pesa launched in 2007, agents were the only way to convert cash into digital value. Interoperability between networks since 2022 has weakened the lock-in that once made a single agent’s location a competitive moat.

Merchant payment systems like Lipa na M-Pesa and Pochi la Biashara now let customers pay directly from their wallets without withdrawing cash first. Pochi la Biashara revenue grew 86% in the year to March 2026, while withdrawal revenue actually declined 0.7% even as total M-Pesa revenue grew 14%.

Agents are processing more transactions for less money. Total M-Pesa transaction volume grew 26.5% in the same half-year period, but transaction value grew only 5%. More small transactions mean more time serving customers and more liquidity rebalancing trips, without a proportional increase in commission income.

Some agents are adapting. A growing number now offer agency banking services for institutions like Equity Bank, KCB, and Co-operative Bank alongside mobile money, and others operate both M-Pesa and Airtel Money outlets to widen their customer base.

The Central Bank’s planned 57% cut in mobile money transfer fees by 2028, part of its National Financial Inclusion Strategy, will further compress the commission pool unless transaction volumes rise enough to compensate. Analysts at FSD Kenya estimate that 90,000 agents could close, mainly in sparsely populated regions.